
Instant payments
Safe and fast ways to send money without a bank account
Safe and fast ways to send money without a bank account. With Comun, Remittances and P2P with clear costs and a transfer fee starting at 2.99 USD up to applicable limits.
8 min read

15 Aug 2025

Did you know it is possible to send money without having a bank account? The lack of access to financial services is a problem that negatively affects the quality of life of thousands of immigrant workers in the United States.
For example, according to a recent survey, the rate of the Latino community in the United States without a bank account dropped from 15% to 10% over the last two years. However, it remains high compared to the national average of 4.5%.
While having a bank account facilitates financial transactions such as transfers, in-store payments, and online purchases, there are now alternatives that allow you to access banking services without needing an account.
Below, you will discover how to transfer money from one card to another without an app or bank account, as well as the safest and simplest methods available to you.
Sending Money Online
Not having a U.S. bank account is not an obstacle to sending money domestically or internationally, as there are methods widely used among immigrant workers who regularly send remittances and conduct other transactions using prepaid cards and cash payments.
International Money Transfer Providers
This is one of the most popular ways to send money without a bank account due to the accessibility, variety of payment methods, and broad coverage typically offered.
International money transfer providers are companies that specialize in facilitating money transfers from one country to another. The key features of these services include:
- Specialization in international money transfers, unlike traditional banks, which have certain limitations, such as high commissions, unfavorable exchange rates, extensive delivery time, and participation of intermediaries that increase costs.
- More affordable fees.
- Various sending methods.
- Multiple Money Transfers Locations
How to Send Money Without a Bank Account Through an International Transfer Platform
Comun allows you to send money to your loved ones for a modest transfer fee starting at USD 2.99 up to the applicable limits. It is very simple; just follow these steps:
1. Open your account with Comun; it will only take a few minutes!
2. Choose the most convenient delivery method for your recipient, such as cash pick up at a physical store like Oxxo, Grupo Elektra, 7 Eleven, and more.
3. You may also send money directly to a bank and have it picked up at one of its branches.
4. Track the delivery directly in your Comun mobile application.
Comun is an excellent option for our community, as it provides Spanish-language service, which is highly appreciated by the immigrant community. Open your account today and start sending money without complications.
What Information Do You Need to Send Money Without a Bank Account?
To send money without a bank account, you only need the following information about your recipient:
- Full name of the recipient, exactly as it appears on their official ID.
- Recipient’s phone number.
- If the transfer is made to a bank account, you will also need:
- Recipient’s address.
- Bank account number, depending on the receiving country.
P2P Services
P2P (peer-to-peer or person-to-person) services allow immediate money transfers between individuals without intermediaries. These options are useful for everyday needs such as paying rent, shared services, splitting transportation costs, and sending money to your relatives in the US or internationally.
How to Send Money Without a Card Using P2P Services
- Choose a reliable provider, such as Cash App or Venmo.
- Enter the recipient’s phone number in the mobile app.
- Confirm the transaction and track it.
Sending Money by Mail
Other alternatives involve sending a cashier’s check, a certified check, or a money order through the postal service.
Cashier’s Check
This type of check is issued with the bank’s funds. The customer must pay in cash or directly from their account, and the check is made payable to the recipient.
Certified Check
This check is issued using the customer’s funds. The issuer must have a bank account so that the bank can verify the availability of funds. The recipient may cash the check directly at a bank branch.
Money Order
Another way to send money without a bank account is by using a money order, which is a type of prepaid payment order. To do so, you will need to:
1. Go to a post office or authorized retailer, such as USPS or Walmart, to purchase a money order.
2. Write the beneficiary’s name in the “pay to the order of” section.
3. Write your name in the “purchaser” section.
4. Sign in the space designated for the purchaser, generally on the front of the document.
5. Keep the receipt with the serial number.
6. Pay the amount to be sent plus applicable service fee.
7. Send the money order via regular or certified mail.
8. Write the recipient’s address in the center of the envelope and the sender’s address in the upper left corner.
9. Purchase a postage stamp at the post office and attach it to the envelope.
10. Drop off the envelope at the post office.
The recipient may cash the money order at an authorized branch upon presenting valid personal identification.
The downside of this alternative is that it takes longer to arrive, as it relies on a traditional mailing method.
Sending Money With Prepaid Load
There are other options available to send money without a bank account, such as prepaid cards and mobile applications.
Reloadable Prepaid Cards
Reloadable prepaid cards function similarly to debit cards, with the main difference being that they are not linked to a bank account. They also allow you to pay for services and make online purchases.
To send money using a prepaid card, you only need to:
1. Identify an international money transfer service that supports prepaid cards, such as Western Union or MoneyGram.
2. Select your preferred provider and choose the prepaid card option on their website.
3. Enter the recipient’s information, making sure it is compatible with the selected platform.
4. Confirm the transfer and pay the amount plus the applicable service fee.
Done! The recipient will receive the money on the prepaid card as if it were a bank transfer.
Mobile Wallets/Applications
Lastly, you may opt for mobile wallets or applications that offer money transfer capabilities. Some examples include Cash App, Venmo, and Remitly, which provide access to an mobile app you can use to send and receive money.
These applications do not require a bank account and are user-friendly. Some also offer physical cards that function similarly to debit cards.
7 Essential Tips for Sending Money Without a Bank Account
1. Verify the Identity and Information of the Recipient
Ensure that the recipient’s information, such as name, account number, or phone number, is entered correctly. Any discrepancies could prevent the recipient from collecting the funds.
2. Compare Fees and Exchange Rates
Each provider has its own rates depending on the receiving country, amount, and exchange rate. Remember, with Comun you do not pay excessive fees, and you ensure your family receives more for less.
3. Know the Sending Limits
Some platforms have sending limits that should be considered before selecting a service. For instance, Western Union has a daily limit of USD 7,499, while Cash App allows up to USD 7,500 per week for verified accounts.
4. Keep All Receipts and Reference Numbers
Even though these methods are secure, it is important to keep receipts and reference numbers in case a clarification or issue arises.
5. Use Reputable and Secure Services
It is essential to ensure that you use a trusted service. Check online reviews and verify that the provider has an official website and/or physical offices.
6. Be Cautious of Scams
Unfortunately, scams are common around financial services. No legitimate institution will request passwords or verification data. Always access official websites. If in doubt, visit an authorized branch.
7. Consider Delivery Time
Most options allow you to complete transfers in minutes, but some may take several days. Consider this before choosing your preferred service.
Frequently Asked Questions
Is it safe to send money without a bank account?
Absolutely. Comun is backed by leading financial institutions to protect your funds up to the applicable limits. Additionally, you can track your transfer directly through the Comun mobile app.
How much does it cost to send money without a bank account?
Comun offers a transfer fee starting at USD 2.99, regardless of the amount you send up to the applicable limits. Your first transfer is commission-free!
How long does it take for the money to arrive?
Cash is typically available within approximately 1 hour at the selected store or bank branch.
What documents do I need to send/receive money without an account?
You need the full name of your recipient, and they must present official identification.
About Común
Común aims to support the Latino community in the United States. It offers a debit account that can be opened with more than 100 valid Latin American IDs and an app available in Spanish.
Visit Común's website or download the app for free to learn more about the full offer and applicable terms.
Olivia Rhye
Community Partner

Instant payments
What is Cash App and how does it work?
8 min de lectura
What is Cash App and how does it work?
Cash App is a peer-to-peer (P2P) payment app that allows users in the United States and the United Kingdom to send and receive money digitally. Over time, Cash App has expanded beyond transfers and now also offers features such as debit cards, direct deposits, savings tools, and investing options.
If you recently moved to the United States or are exploring digital financial tools, you have probably heard of Cash App. The app is widely used for sending money between friends, paying for purchases, and managing certain financial activities directly from a smartphone.
For many immigrants in the United States, understanding how Cash App works is important because it may appear similar to a traditional bank account, but it is not exactly the same thing.
What is Cash App?
Cash App is a mobile financial app that allows users to send, receive, store, and spend money digitally through their phones. The app is commonly used for:
- Sending money to friends or family
- Receiving payments
- Paying for purchases
- Using a debit card linked to your balance
- Receiving direct deposits
- Buying stocks or Bitcoin
Unlike traditional banks, Cash App primarily operates through its mobile app rather than physical branches.
How does Cash App work?
To start using Cash App, you need to download the app, create an account with a U.S. phone number or email, and link a bank account or debit card. Once the account is set up, you can send or request money by searching for another person by their $Cashtag, phone number, email, or QR code.
Standard transfers typically arrive in 1 to 3 business days to a linked bank account. Instant transfers to a debit card usually carry a percentage-based fee.
How much does Cash App charge? — Fee table
| Service | Typical Cost |
|---|---|
| Standard bank transfer (1–3 business days) | No additional fee |
| Instant transfer to debit card | Percentage-based fee |
| Sending money using linked credit card | Additional fee may apply |
| ATM withdrawals | Fee may apply depending on conditions |
| Account opening | No monthly fee |
Fees and terms may change over time. Always review the official Cash App website before using financial services.
Is Cash App safe?
Cash App uses encryption and security features like Face ID and Touch ID. However, like any P2P payment platform, it is important to use it only with people you know. Once sent, money generally cannot be recovered if the transaction went to the wrong person.
Is Cash App available in Spanish?
Spanish-language support availability on Cash App may vary. The app's primary experience is mainly in English, which can be a limitation for users who prefer to operate in Spanish.
Can an immigrant open a Cash App account?
Cash App has its own eligibility requirements for account opening. Requirements may include a U.S. phone number or email address, and additional verification information may be required. It is recommended to review Cash App's current terms directly.
Limitations of Cash App for Latino immigrants
- Does not support international remittances to Latin America
- Spanish-language experience may be limited
- May not accept Latin American IDs for account opening
- No dedicated 24/7 Spanish-language support
Cash App vs. Común — Quick comparison
| Feature | Cash App | Común |
|---|---|---|
| P2P payments in the U.S. | Yes | Yes |
| Debit card | Yes | Yes |
| Stock and Bitcoin investing | Yes | No |
| Remittances to Latin America | No | Yes |
| Spanish-language experience | Spanish-language support availability varies | Yes |
| Payroll direct deposit | Yes | Yes |
| Open account with Latin American IDs | Eligibility requirements apply | Yes |
| Monthly maintenance fee | Varies by service usage | No monthly maintenance commission |
| Minimum balance requirement | Not always required | $0 |
FAQ
Is Cash App available in Spanish?
The app primarily operates in English. Spanish-language support availability may vary.
Can I send money to Mexico with Cash App?
No. Cash App does not support international money transfers to Mexico or other Latin American countries.
How much does Cash App charge for instant transfers?
Cash App charges a percentage-based fee for instant transfers to a debit card. Verify current fees on the official Cash App website.
Is Cash App safe?
Cash App uses encryption and identity verification. However, P2P transfers are difficult to reverse. Use it only with people you know and trust.
What is the difference between Cash App and Común?
Cash App focuses on domestic payments in the U.S. Común also offers domestic payments but additionally includes remittances to Latin America, full Spanish-language support, and the ability to open an account with more than 100 Latin American IDs.
Común is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank, Member FDIC. Peer-to-peer payments services are provided by Cross River Bank. No minimums, no monthly maintenance commission.

Immigration
What is SSN? Everything you need to know if you are a resident in the U.S.
8 min de lectura
An SSN (Social Security Number) is a 9-digit number issued by the U.S. government. It is required for working legally, filing taxes, and accessing financial services in the United States. As an immigrant, you may apply for an SSN if you have an eligible visa or Green Card — or use an ITIN as an alternative. If you have newly arrived in the U.S., you likely have questions about how to handle certain procedures. Therefore, we will explain what the SSN is, what it is for, how to apply for it, how much it costs, and what the benefits are of having this identifier.
What is the Social Security Number (SSN)?
The Social Security Number (SSN) is a series of 9 digits issued by the Social Security Administration (SSA, or Administración del Seguro Social in Spanish). It is issued to citizens, permanent residents, and eligible temporary residents, in accordance with their immigration status.
Its main function is to serve as a unique identification number that allows the government to track specific data for each person, such as their income, financial information, and employment history. This makes it possible to determine, in each particular case, eligibility to access Social Security benefits such as retirement, disability, among others.
In addition to facilitating access to these benefits, the Social Security card serves as official identification for employment onboarding, driver’s licenses (in some states), and opening bank accounts.
How to obtain the Social Security Number in the United States?
An important point about the Social Security Number in the U.S. is that there are three different types:
- For citizens born in the United States
- For citizens born abroad
- For non-citizens with lawful resident status
In the case of lawful permanent residents, it is necessary to obtain a Green Card or a visa with valid work authorization issued by the Department of Homeland Security (DHS), such as H-1B or L-1.
The process of obtaining the SSN varies depending on immigration characteristics. If you requested the SSN during your visa processing—through the “Application for Immigrant Visa and Alien Registration” form or the DS-260 electronic format, “Immigrant Visa Electronic Application”—DHS will contact the Social Security Administration directly to carry out the process.
Get your SSN in just 4 steps
If you did not request the SSN during your visa process, the first thing you should do is gather the following documentation:
- A valid passport with the Machine Readable Immigrant Visa (MRIV) or a Permanent Resident Card (Form I-551)
- Birth certificate
Once you have gathered the documentation, follow these steps:
- Download and complete the SS-5 application
- Go to an SSA office
- Present the original documents
- Wait 7 to 14 days to receive the Social Security card by mail
What to do if your SSN card is lost?
If your Social Security card is lost, it is important to take security measures immediately to avoid identity theft, fraud, or misuse of your personal data.
Report the theft or loss of this document to the police and then file a complaint with the Federal Trade Commission (FTC).
Afterwards, go to the Social Security Administration, complete the SS-5 form again, and bring the corresponding documents for replacement of the card.
Avoid carrying the card with you unless necessary and keep it in a safe place. Generally, you do not need to present your physical card but rather the number, which does not change even if you replace the card.
5 benefits of having an SSN
If you are still wondering what the SSN is for, you should know that this document provides multiple benefits of different kinds, such as the following:
1. Employment
For permanent residents, the greatest benefit of the SSN is that it grants work authorization, enables income tracking, as well as the payment of taxes and legal obligations. Presenting this document is an indispensable requirement during formal hiring processes in the United States.
2. Credit
The SSN is also typically required to apply for loans and credit from banks and financial institutions in the United States; in this way you can access assets such as real estate, a car, or other types of services.
3. Banking services
Accessing financial services is essential for immigrant workers in the United States, whether to receive wages or send money to their countries of origin. Generally, the SSN is a requirement to access a bank account and credit and debit cards, among other services.
4. Government benefits
There are other benefits available, such as unemployment insurance in the event of dismissal, and access to retirement and Medicare starting at age 65, for eligible permanent residents.
5. Taxes
The SSN functions as the taxpayer’s personal identification number, which makes it easier to file tax returns and report income and expenses. Another alternative for residents who do not have an SSN is the ITIN, issued by the Internal Revenue Service (IRS), which serves to fulfill tax obligations and grants other benefits.
In short, the Social Security Number—beyond being an administrative procedure—facilitates economic and social integration in the United States because it serves to track income and expenses and facilitates access to basic rights such as work, health, and banking, which are essential for integrating into society.
How much does it cost to get an SSN?
It is important to clarify that the Social Security card process does not involve any cost, whether you do it for the first time or as a replacement due to theft or loss.
Stay alert to potential fraud and avoid making payments to unauthorized third parties. If you have any doubts, go directly to your local Social Security office and report any suspicious activity.
Read more: Don’t miss our guide to investment basics for immigrants
Simplify your financial life upon arriving in the United States with Comun
As you can see, the SSN is highly relevant to establishing a stable life in the United States because it facilitates access to work, health services, and financial products that are essential for carrying out daily tasks such as payments and money transfers.
Comun is a financial platform designed to make life easier for immigrants in the United States by facilitating their integration into the financial system from day one.
- Open your account with an official ID from your country of origin
- Receive a Visa debit card and make purchases easily in physical stores and online
- Access a mobile application and manage your finances from the palm of your hand
- Send remittances to your home country for a fee starting at $2.99 USD, up to the applicable limits
- Forget about hidden fees and complicated processes
- Access support available in Spanish and English
With Comun, discover the most accessible way to manage your finances for everyday life in the United States.
Frequently Asked Questions
If you still have questions, consult our Frequently Asked Questions section.
What should I do if someone uses my SSN without permission?
Report immediately at IdentityTheft.gov and place a fraud alert.
How many times can I replace my SSN card?
Up to 3 times per year and a maximum of 10 times in your lifetime.
Is it mandatory to have an SSN to open an account with Comun?
Comun allows you to open an account with official ID from your country.
Financial Education
Exchange Rates and Currency Margins: A Simplified Explanation
8 min de lectura
Introduction: What Is the Foreign Exchange Market?
The foreign exchange (FX) market is the backbone of global trade, since it allows one currency to be exchanged for another. Whether you're traveling abroad, buying international products, or investing overseas, FX plays a crucial role in our financial lives. This article aims to demystify two key FX concepts: exchange rates and currency margins, explaining them in simple terms for new banking customers and anyone unfamiliar with these topics. Understanding these concepts is crucial for customers of Community Federal Savings Bank and other financial institutions that offer banking services.
What Is the Exchange Rate?
The exchange rate is the value of one currency in terms of another. For example, if 1 U.S. Dollar (USD) is worth 0.85 Euros (EUR), the exchange rate is 1 USD = 0.85 EUR. Exchange rates fluctuate based on supply and demand in the foreign exchange market. Several factors influence these rates, including:
- Supply and Demand: If a currency is in high demand, its value increases. Conversely, if there's more supply than demand, the currency's value decreases.
- Central Banks and Government Policies: Central banks, like the Federal Reserve in the U.S. or the European Central Bank, can influence exchange rates through interest rates and monetary policy. For example, higher interest rates offer better returns on investments in that currency, increasing demand and value.
How Do Exchange Rates Affect Us?
Exchange rates impact several aspects of our lives:
- International Travel: When you travel abroad, the amount of foreign currency you get for your money depends on the exchange rate. For Común customers, understanding exchange rates⁴ helps keep your money secure while traveling. Examples of fluctuating exchange rates include: 1 USD = 0.85 EUR or 1 USD = 109.75 Japanese Yen (JPY).
- Cost of Imported Products: Products priced in foreign currencies become more or less expensive depending on the exchange rate.
- International Business and Investment: Businesses dealing with international customers and suppliers, or investing abroad, are affected by exchange rate fluctuations, which influence their costs and revenue.
What Is the Currency Margin (FX Spread)?
The currency margin is the difference between the buy price and the sell price of a currency pair. The buy price is what buyers are willing to pay, while the sell price is what sellers are asking. The spread is essentially the cost of trading currencies.
For example, if the buy price for EUR/USD is 0.84 and the sell price is 0.86, the currency margin is 0.02. This margin is crucial because it represents the transaction cost of exchanging currencies, which is a key consideration for banks and financial institutions.
Why Does the Currency Margin Exist?
Several factors contribute to the existence of the currency margin:
- Market Liquidity: Greater liquidity (more buyers and sellers) generally results in a narrower margin. Lower liquidity leads to a wider margin.
- Currency Brokers and Financial Institutions: These intermediaries set the buy and sell prices, factoring in their profit margins.
- Transaction Costs: The costs of executing trades and maintaining currency inventories are also built into the margin.
How Does the Currency Margin Affect Transactions?
The currency margin impacts the cost of exchanging money. A smaller margin means lower costs, while a larger margin increases the cost. Here are some examples:
- Small Margin: If the buy-sell margin is small (for example, 0.01), the transaction cost is low, making it cheaper to exchange currency.
- Large Margin: A larger margin (for example, 0.05) means higher transaction costs.
To minimize the cost of exchanging currency, consider:
- Comparing Rates: Look for the best exchange rates and lowest margins, especially when using Community Federal Savings Bank banking services.
- Timing: Exchange money when market liquidity is high, typically during business hours in major financial centers.
Real-World Examples:
Understanding currency margins can help you make better financial decisions:
- Traveling Abroad: When exchanging money for a trip, the currency margin affects how much foreign currency you receive. Común¹ account holders can keep their money secure by understanding these margins.
- Online Shopping: Buying products on international websites involves currency conversion, where the margin influences the total cost.
To check the current exchange rate and currency margin, use online currency converters and financial news websites. Financial inclusion matters, and platforms like Común offer tools and support to help Latino immigrants and other users manage their money effectively.
Conclusion: Stay Informed
In summary, the exchange rate determines the value of one currency against another, while the currency margin is the cost of trading currencies. Understanding these concepts is essential for making informed financial decisions, whether you're a new banking customer or new to the world of FX. Stay informed and use this knowledge to navigate the complex world of currency exchange more effectively.
Additional Resources
- FDIC-Insured Banks: Make sure your funds are safe by choosing FDIC-insured banks like Común.
- Support and Security: Común offers customer support and security features to protect your personal information and funds.
- Remittances: For Latino families and immigrants, understanding exchange rates can help send money abroad efficiently.
Understanding exchange rates and currency margins can have a significant impact on your financial transactions. By staying informed, you can make better decisions and optimize your currency exchanges, improving your overall financial health.
Financial Education
Emergency Fund: Guide to Build It and Save in the U.S.
8 min de lectura
How to create an emergency fund and save in the U.S., step by step
If you’re new to the United States or facing financial challenges, it’s very important to have strategies to prepare for any eventuality.
An emergency fund is an excellent way to do this, and it also builds your financial literacy. It’s a cash reserve meant to cover unexpected expenses such as illness, job loss, home repairs, etc.
Having this cushion gives you peace of mind and removes uncertainty about the future, since it provides the liquidity you need to handle the unexpected.
You might think you need to earn a lot to build an emergency fund. Below, we’ll show that even with limited resources, you can start securing a future without financial complications.
What is an emergency fund and why is it key to your financial peace of mind?
Surely at some point during your time in the U.S., you’ve faced financial emergencies that made it hard to cover daily expenses—traffic fines, immigration procedures, illnesses, unemployment, repairs, etc.
An emergency fund is meant to support your finances precisely when those events occur. It’s savings set aside to handle all kinds of unforeseen expenses.
Beyond a stash of money, think of the emergency fund as a way to maintain peace of mind and reduce stress; it helps you preserve financial stability and avoid going into debt.
How much should you save in your emergency fund?
Knowing how to size an emergency fund is the first dilemma for many who aren’t used to long-term saving. While the ideal target is 3–6 months of basic expenses, if your income is limited you can start with small savings goals.
Below is a comparison of how your emergency fund would grow assuming expenses equal to 50% of total monthly income.
Monthly income
Approx. monthly expenses
3-month savings target
6-month savings target
$1,500
$750
$2,250
$4,500
$2,500
$1,250
$3,750
$7,500
$3,500
$1,750
$5,250
$10,500
Where should you keep your emergency fund so it’s safe and accessible?
It’s very important to choose a safe, easy-access place for your emergency fund and keep it separate from the money you use for daily expenses.
Today there’s a wide variety of savings accounts, both from traditional financial institutions and online platforms.
Whatever you choose, the following options are not recommended for storing your emergency fund.
- Cash at home
Whether under the mattress or in a piggy bank, keeping your emergency fund in cash is not a good idea for several reasons. First, there’s the risk of theft or loss. Also, the cash earns no interest and loses value to inflation. Another drawback is low accessibility if you need to cover expenses digitally.
While it’s true that opening a checking account can be challenging for immigrants in the U.S., there are accessible options so you don’t have to keep the emergency fund in cash.
- In high-risk investments
Although investments have advantages, high-risk ones involve sharp fluctuations that could cause losses. They also often require locking funds for a long period.
Simple strategies to build your emergency fund
If you’re new to personal finance, the first thing to know is that an emergency fund isn’t just for high earners. The key is to examine your lifestyle and spend according to a savings plan.
Step 1. Calculate your basic monthly expenses
The first step is to list all your fixed monthly expenses and the amount for each.
Example:
- Rent: $1,300
- Transportation (public or private): $100
- Tuition: $200
- Subscriptions: $50
Then list your variable expenses and calculate a budget. To be more accurate, track all your spending by category.
Example:
- Food: $300
- Leisure: $200
Finally, total your monthly spending. In the example above, monthly expenses add up to $2,100.
Step 2. Set your first goal
At first, reaching 3–6 months of expenses can sound impossible. You don’t have to give up what you enjoy—start with a small amount each month and increase gradually.
Your first savings target depends on your income, your expenses, and the resulting capacity to save.
Step 3. Adjust your budget and allocate a fixed percentage to savings
After doing the math, add “savings” as a fixed expense so you set that money aside every month.
Step 4. Automate with scheduled transfers
Ideally, open a new account so your emergency fund doesn’t mix with daily-use money.
An easy way to fund it is with automatic transfers so you don’t have to remember to move money each time.
Step 5. Review and raise your goal until you reach 3–6 months of expenses.
After a few months of hitting a small goal, reassess your budget and consider increasing your savings as you’re able.
Organize and protect your money with Común
As you can see, an emergency fund provides financial security for unexpected events. It’s also easy to start with small goals and increase gradually until you reach financial peace of mind.
The next step is choosing a safe place to keep your emergency fund secure.
Meet Común, the financial platform dedicated to making life easier for immigrants in the United States!
- Open your checking account at Común with a qualifying official ID from your country of origin.
- Send money to your family with clear, competitive fees.
Común is a financial platform designed to support your first steps toward financial stability in the U.S.
Open your account with Común today and start your emergency fund with a financial ally that truly understands you.
Frequently Asked Questions (FAQ)
If you still have questions, check this section.
Is it better to save for the emergency fund or pay debts first?
Having debts doesn’t prevent you from starting an emergency fund. Just include debt payments among your fixed monthly expenses and set your savings goal accordingly.
What happens if I use the fund and end up with no savings?
If you use your emergency fund for unexpected expenses, that’s fine—that’s its purpose. If you run it down, don’t worry; just start again based on your budget.
When should I use my emergency fund?
Your emergency fund is intended to cover unexpected events like medical bills, appliance breakdowns, layoffs, etc. When that happens, use it—and keep saving afterward.
Financial Education
How to fill out a check in the United States in 5 simple steps (+ Example)
8 min de lectura
Have you ever filled out a check? Although most transactions today are digital, knowing how to fill out a check is essential—especially if you are just beginning your financial life.
According to recent data, one-third of Americans paid by check in 2024, demonstrating that checks still play an important role in the U.S. economy.
You might consider checks an outdated payment method; the reality is that they are useful in specific situations. For that reason, we will explain what a check is, the different types of checks, and how to complete them properly.
What Is a Check and What Is It Used For?
Despite the digital era, checks remain a relevant traditional payment method due to their formality and traceability. They are used for rent payments, purchases, and service payments.
Additionally, checks are a common payment method among the immigrant community, who often use them while adapting to the U.S. banking system.
But what exactly is a check and what are its characteristics? It is a physical document issued by an individual or business (the drawer) to order a bank to pay a specified amount to a third party. For the payment to be processed, the drawer must have sufficient funds in their checking account.
In general, a check contains the following information:
- Name of the drawer, whether an individual or a business
- Name of the payee
- Financial institution where the money will be drawn
- Amount to be paid, both in numbers and in words
- Signatures of the drawer
What Are the Different Types of Checks?
There are different types of checks in the United States. In this case, we will focus on the personal check, although you may choose the option that best suits your needs.
Personal Check
A personal check is a payment order issued by an individual to another individual using the funds in a checking account.
What Is a Personal Check Used For?
The most common uses for personal checks include:
- Rent and utility payments
- Purchase of everyday goods
- Legal agreements requiring documentary support
Certified Check
A certified check serves the same purpose as a personal check but is reviewed and guaranteed by the issuing bank, which verifies that the drawer has sufficient funds and holds them until the check is cashed.
A certified check provides certainty of available funds, making it a more secure method for making and receiving payments.
Cashier’s Check
Unlike a personal check, a cashier’s check is issued directly by the bank, offering greater security for the payee, as the bank is responsible for issuing and safeguarding the funds.
To obtain a cashier’s check, the drawer must visit a bank branch and pay the amount to be transferred. The bank then issues the check in the name of the payee, guaranteeing that it can be cashed using the institution’s own funds and not a personal account.
It is commonly used for high-value purchases such as homes and vehicles.
Money Order
While not strictly a check, it is a traditional payment method with similar functionality.
A money order is a financial instrument that allows funds to be sent via traditional mail using a certified check, which must be purchased and paid for by the drawer at an authorized location.
It allows secure money transfers without requiring a bank account.
How to Fill Out a Check in the U.S.
Before issuing this type of payment order, you must know how to do it properly. Below is an example of how to fill out a check easily, starting from step one:
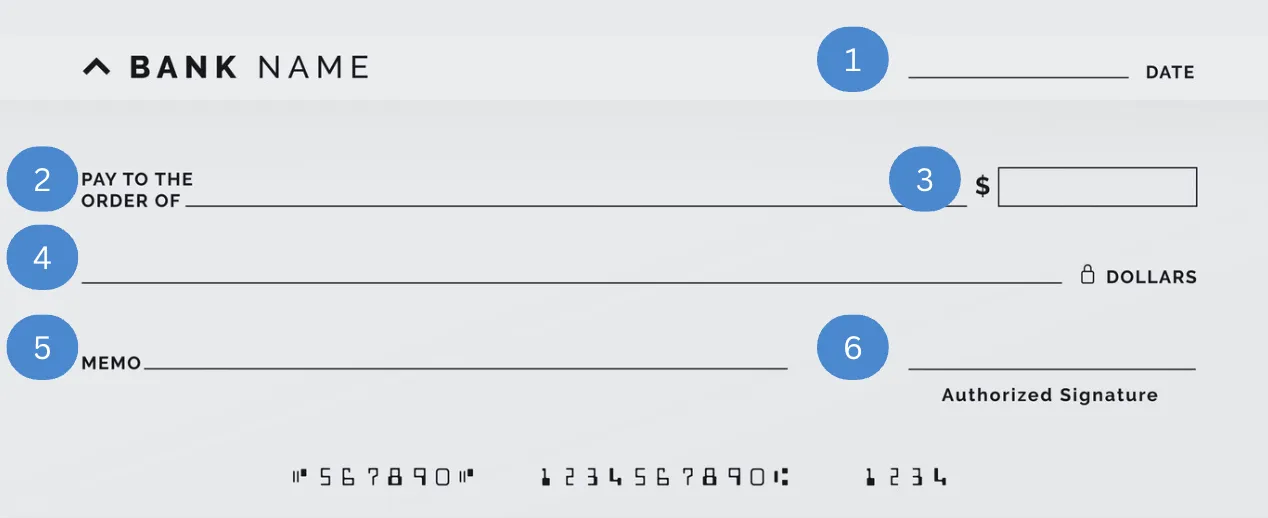
1. Write the Date
Remember that in the United States, the date format is mm/dd/yyyy.
2. Payee’s Name
Write the full name of the person to whom you are issuing the check, exactly as it appears on their official identification.
3. Amount in Numbers
Write the numerical amount clearly.
4. Amount in Words
Write the amount in words, including cents.
5. Add a Memo
You may include a note specifying the reason for the payment.
6. Sign the Check
Sign the check legibly in the space designated for the drawer.
7. Review the Information
Ensure that all information is accurate to avoid issues for the payee when cashing the check.
It is essential to complete checks legibly, without strike-throughs or corrections, as these may invalidate the document.
How to Correctly Write Numbers in Words on a Check
Writing amounts in words may be confusing when dealing with U.S. dollars. The following points should be kept in mind:
- Dollar amounts must be written in full words
- Cents must be written as fractions
- Avoid using dollar symbols or similar notations
- If there is leftover space at the end of the line, draw a line to prevent fraud
- For example, $1,000.75 is written as: One thousand and 75/100 dollars
Cash Checks and Manage Your Money Easily with Comun
As you can see, knowing how to fill out a check is useful for sending and receiving money in the United States. It is a reliable and accessible alternative if you do not have a banking account.
However, issuing and cashing a check can also require significant time and effort. That’s why you can skip the trip to the bank, avoid wasting time or money on gas, and cash your check directly from your phone using Comun—no lines, no questions, no complications.
Discover Comun, the only platform designed to serve the needs of immigrant communities in the United States, with support available in Spanish.
Why Choose Comun?
- Open your account with an official ID from your country
- Access a mobile app specifically designed for immigrants in the U.S.
- Make payments, receive your salary, and manage your finances
- Send money to your loved ones in LATAM for just a $2.99 transfer fee
Frequently Asked Questions
Still have questions about how to fill out a personal check? See our FAQ section.
What if I Make a Mistake Filling Out a Check?
If there are strike-throughs or inconsistencies in the amounts, the check must be voided and a new one used.
How Do I Void a Check?
Write the word VOID in large letters on the front of the check.
What Information Appears on the Back of a Check?
The back of the check contains the endorsement, meaning the payee’s signature for cashing the check.
International Money Transfers
How to make an international money transfer? Costs, times and requirements
8 min de lectura
International money transfers can be sent via bank wire, money transfer apps, or remittance services — each with different fees, speed, and delivery options. With Común, transfers to Latin America start at $2.99, with most arriving within minutes.
For immigrants in the United States, sending money to their home countries regularly is essential. Therefore, it is important to have access to affordable and accessible financial services.
If you want to know how to make an international money transfer, it is crucial to first compare the different providers of this service and choose the one that offers the most advantages for you and your family.
Comun stands out as a popular option among immigrants because it allows them to send money abroad from the United States, offering advantages in terms of cost, speed, and other key factors.
Below, we provide a comparison table that includes Comun and traditional financial institutions in the United States, such as Bank of America and Wells Fargo:
| Comun | Traditional Financial Institutions | |
|---|---|---|
| Fee | Transfer fee starting at 2.99 USD up to applicable limits | From 10 to 45 USD, depending on the bank |
| Intermediary fees | $0 USD | May generate extra fees from intermediary banks |
| Exchange rate | Competitive | Higher margin than official |
| Speed | Instant to a few minutes (average 8) | From 1 to 5 business days |
| Estimated total fee | 2.99 USD transfer fee + exchange rate, with no extra charges (The first transfer has no fee. Subsequent transfers have a fee starting at $2.99 USD, up to the applicable limit. ATM or intermediary charges may apply; check the app for more details). | From 20 to 60 USD, due to fees and less favorable exchange rates |
How Does an International Money Transfer Work?
The first point to understand is the types of bank transfers available, as this determines the final cost of sending an international money transfer.
In the United States, there are two types of international money transfers: through traditional banks or through specialized services for sending money abroad.
International Money Transfers via Traditional Banks
- Supported by official U.S. financial institutions and security measures, including:
- Identity verification (KYC/CIP) and ongoing AML monitoring (BSA).
- OFAC sanctions screening for senders and recipients.
- Consumer protections for remittances under Regulation E (pre-transfer disclosures, cancellation rights, and error resolution).
- Network and messaging security standards (e.g., SWIFT Customer Security Program).
- Multi-factor authentication and encryption for online banking access.
- A U.S. bank account is mandatory
- Operates through the SWIFT code
- Generates higher fees due to intermediaries
- Transfer time may take up to 5 business days
International Transfers via Specialized Applications
- Operates through digital networks connected with banks or physical branches in each recipient country
- Lower fees, as they do not use intermediaries and offer more competitive exchange rates
- Money transfers are completed within minutes or hours
- A U.S. bank account is not mandatory to use these services
Before paying unnecessary fees, make sure to choose the best international money transfer provider and make the most of your money.
Steps and Requirements for Making an International Money Transfer
Below, we outline what is needed to easily make an international bank transfer from the United States, whether you choose a traditional bank or a specialized application for this type of service:
1. Choose a Provider
Some of the traditional banks you can use are Chase, Bank of America, Capital Bank, Citibank, and Wells Fargo. If you don't have a US bank account, you'll need to make sure you have the necessary requirements to open an account, such as a Social Security Number (SSN). For the aforementioned banks, you can present an ITIN instead, along with a government-issued ID.
Another factor to consider is how long an international money transfer takes, as traditional banks usually take longer due to intermediaries involved in the process.
If you prefer a specialized application for international money transfers due to the flexibility they offer compared to banks, an excellent alternative is Comun, which allows you to transfer money from your phone without complications or intermediaries.
2. Create an Account
General Requirements for Opening an Account at a U.S. Bank
- Valid passport or immigration document
- Social Security Number (SSN)
- Individual Taxpayer Identification Number (ITIN)
- Proof of address in the United States
- Some banks require an initial deposit of approximately $25 USD
Depending on the bank, you may open the account online or by visiting a branch for data verification.
Requirements for Opening an Account with Comun
- Mobile phone compatible with Android or iOS
- Email address
- Official foreign identification
- Have a US residential address
In both cases, you will have access to a debit card and a mobile application that will allow you to make international money transfers and other transactions from the palm of your hand.
3. Enter Transaction Details
Once you activate your account, enter the information required for an international money transfer:
- Full name of your recipient, as it appears on their official ID
- Recipient’s phone number
- Recipient’s address (only if sending money to a bank account)
- Recipient’s account number (only if sending money to a bank account)
- SWIFT code (if transferring through a traditional bank)
Then, enter the amount you wish to send.
Comun and other specialized applications also allow cash pickup at physical locations, so your recipient does not need a bank account.
4. Review Costs and Rates
Next, review the international money transfer fees as well as the exchange rate, as these will impact the final amount your recipient receives.
The cost of an international money transfer depends on several factors, which we detail below.
5. Send the Money
Once you confirm that the information entered is correct, authorize the transfer, including any additional fees.
Comun allows you to track your transfers through its application, whether you choose to send money to a bank account or opt for cash pickup at a physical location.
Remember that transfer speed depends on the platform, and traditional banks can take up to 5 business days to complete these transactions.
6. Confirm Receipt
Finally, confirm with your recipient that the transfer was received within the stipulated timeframe. You can generate a transaction receipt directly in the mobile application.
Everything About the Cost of Sending Money Abroad from the U.S.
International money transfers are a common practice among immigrants in the United States.
That is why it is essential to detail the factors that influence the cost of transfers, as well as the best options for sending remittances to your family quickly and without complications.
These are the main factors to consider when calculating the cost of your international money transfers:
- Transfer Fees
International transfers incur a fee, which varies depending on the platform, whether it's a traditional bank or a specialized app.
Another factor that affects the fee level is the method used to send the money. The price can vary depending on whether the transaction is made through a website, an app, or at a physical branch.
International money transfer fees at traditional banks vary depending on the financial institution. Here are some examples:
- Bank of America: $45 USD
- Wells Fargo: from $25 to $40 USD
- Citibank: from $25 to $35 USD
- Truist Bank: $65 USD
On the other hand, some mobile applications offer international money transfer options for less than $3 USD, which is much more beneficial for the economy of foreign workers.
- Exchange Rate
The exchange rate also significantly impacts the final amount your recipient receives. It refers to the value applied by the platform when converting the dollar amount to the local currency.
Traditional banks generally use a lower rate than the official rate. For example, if the Mexican peso is officially 18.00, banks might apply approximately 17.20 MXN.
This means that if you send $300 USD, your recipient could receive about $13 less (240 MXN less), not counting the bank fees, which make the cost even higher.
- Hidden Fees
In addition to international money transfer fees, traditional banks may charge additional fees if intermediary banks are involved in processing the transfer.
We recommend checking all costs involved and choosing a competitive option that does not reduce the total amount your family will receive.
Comun is an excellent alternative for making international money transfers, as your first transfer fee is waived, and subsequent transfers have a fee starting at $2.99 USD per transfer, up to applicable limits, with no hidden fees or intermediaries.
Review our comparison table between traditional banks and Comun at the beginning of this article, and choose the best option for your money.
Want to Make Secure International Money Transfers? Do It Easily with Comun
In this article, we presented how to make an international money transfer from the United States through traditional banks or specialized applications such as Comun, an excellent choice for immigrants.
Comun is the solution for bringing immigrant families closer together through affordable and low-cost remittances.
Why Choose Comun for International Money Transfers?
- Easily open your account with official documentation from your country
- Send money to your family with a transfer fee starting at $2.99 USD, up to the applicable limits.
- Your money will arrive within minutes
- Access a mobile application and Visa debit card for better control of your finances
Discover an easy and fast way to access the financial services you deserve. Open your account with Comun and forget about complications.
What are the main ways to send money internationally?
Bank-to-bank wire transfers, dedicated money transfer apps, and remittance services are the three main options, each with different costs and delivery times.
What should I compare between international transfer options?
The fee, exchange rate, delivery speed, and whether the recipient needs a bank account or can pick up cash.
How does Común handle international transfers to Latin America?
Transfers start at $2.99, with your first transfer at no cost. Delivery options include bank deposit or cash pickup at locations like Elektra and Oxxo in Mexico, with most transfers arriving within minutes.
Frequently asked questions
What's the cheapest way to send money internationally?
It depends on the corridor and amount; always compare the fee AND the exchange rate, since a low fee can hide a worse exchange rate.
Do I need a bank account in the destination country to receive money?
Not always — some services, including Común, offer cash pickup options that don't require a bank account.
How long do international transfers usually take?
It varies by method — bank wires can take days, while modern remittance apps like Común often deliver within minutes.
Are international money transfers safe?
Yes, when using a licensed provider that's transparent about fees and exchange rates before you confirm.
What information do I need to send an international transfer?
Typically the recipient's name, destination country, and either their bank account details or pickup preference, depending on the method.
Does Común charge for international transfers?
Fees start at $2.99 per transfer, with your first transfer at no cost.
Living in the United States
Best Free Online English Courses for Immigrants in the U.S.
8 min de lectura
Some of the best English classes to learn online as an immigrant in the U.S.
Although moving to the United States brings a number of benefits due to the wide range of job opportunities available, it also presents challenges, such as the language barrier, which can limit opportunities for many immigrants who have not had access to formal language education.
While it may seem like a difficult goal to achieve, speaking English can make many aspects of daily life easier — such as getting a job, going to school, or handling important paperwork.
Fortunately, technology allows more people to learn English for free and easily, through platforms and mobile apps that offer lessons from anywhere. Below, we’ll show you some of the best options for immigrants who live or plan to live in the United States to learn English.
5 Reliable Platforms to Learn English from Scratch
For many people, taking in-person English classes isn’t always the best option due to cost, schedules, and transportation challenges. If you face any of these obstacles, you should know about practical alternatives from educational institutions and online platforms — ideal for those who prefer a more academic or progressive learning path.
Below, we present 5 reliable alternatives for learning English online.
British Council
This is one of the most prestigious English teaching institutions worldwide. Its platform offers a variety of courses for beginner, intermediate, and advanced students, segmented by skills: listening comprehension, grammar, writing, and conversation.
It stands out as a very complete option since students can supplement lessons with various materials such as podcasts, videos, and exercises prepared by certified English teachers.
Coursera
Coursera is a platform that offers free English courses in collaboration with prestigious universities, maintaining an academic and professional focus.
This is an excellent option if you’re looking to improve your English to access better job opportunities or refine specific skills to sound more like a native speaker.
BBC Learning English
This platform focuses on teaching English through current content, such as international and cultural news. It’s an ideal alternative for students who want to improve listening comprehension and expand their vocabulary.
USA Learns
This is an official U.S. government platform. It is specifically designed for people who want to acquire basic language skills to handle real-life situations such as visiting the doctor, ordering food, or completing immigration paperwork.
Alison
Alison is another dynamic alternative that offers a variety of free courses across different levels and practical skills. Students can also focus on specific areas, such as business English or preparation for certifications like the TOEFL.
Platform
Type of Course
Level
Main Benefit
British Council
Courses segmented by skills, general English.
From beginner to advanced.
Structured learning units with rich study materials.
Coursera
Academic and professional English.
From intermediate to advanced.
Courses focused on improving professional communication skills.
BBC Learning English
Everyday English.
From beginner to advanced.
Short lessons based on current topics.
USA Learns
Practical English.
Beginner.
Designed to equip students with the skills needed to communicate in everyday situations.
Alison
Business English and official certification preparation.
From beginner to advanced.
Offers the option to earn official digital certificates.
Mobile Applications to Learn English for Free
In addition to the options above, you can also explore other alternatives known for their flexibility in helping you learn English easily.
Mobile language-learning apps let users study anywhere, anytime, and serve as a fun complement to traditional courses.
Duolingo
Duolingo is the most famous and culturally influential app. It uses gamified lessons that unlock progressively as users acquire new skills. It’s ideal for building vocabulary.
Mondly
Mondly focuses on conversational practice and pronunciation using tools like voice recognition and artificial intelligence to interact with virtual characters.
Busuu
Busuu is one of the most comprehensive language-learning apps. In addition to structured lessons based on the Common European Framework, it allows students to interact with native speakers.
Memrise
Memrise focuses on improving listening comprehension and learning new vocabulary through videos of real-life situations presented by native English speakers.
HelloTalk
HelloTalk makes English practice easier by connecting people around the world interested in cultural and language exchange.
How to Choose the Right English Course for You
As you can see, there are many ways to learn and improve your English. Each has different approaches and benefits, so there’s no single “best option” — it depends on your level and specific needs.
Before deciding which online English course is best for you, consider these recommendations:
- Define your goals: be clear about why you want to learn or improve your English.
- Evaluate your current English level: whether you’re a beginner or already advanced.
- Compare platforms and apps: take time to find the one that best fits your needs.
- Review the course duration and format: make sure to organize your time so you can attend classes consistently and on schedule.
- Complement your study with conversation practice: it’s very important to engage with native speakers in real-life situations and different accents.
The most important factor in making language study effective is consistency, regardless of which platform you choose.
Practical Tips to Improve Your English Every Day
In addition to the classes on platforms or the interactive resources in apps, it’s important to incorporate strategies that help improve your confidence and fluency when communicating in English.
Here are some practical tips designed to make life easier for immigrants in the United States.
- Listen to English every day: whether on YouTube videos or movies. The goal isn’t to understand 100%, but to start getting used to the language.
- Practice with friends or coworkers: if you have people you trust, don’t hesitate to ask them for help.
- Apply what you’ve learned in your environment: mentally review your surroundings and try to name the things around you in English.
- Use technology to your advantage: rely on AI-powered tutors or platforms that offer automatic corrections.
Learning English and managing your finances with Comun are key steps to achieving your goals in the U.S.
In this article, we explained why learning English is important if you plan to live in the U.S., and showed you various platforms and apps designed to help you build essential language skills.
Fortunately, the immigrant community in the U.S. has allies dedicated to supporting them through their adaptation and growth in the country.
Discover Comun — the digital platform designed to meet the financial needs of immigrants.
At Comun, we believe every new learning step brings you closer to your dreams: learning English and organizing your money with Comun are steps toward achieving your goals in the United States.
Frequently Asked Questions (FAQ)
What is the best free online English course for beginners?
There are several English course options. If you have no prior knowledge, it’s recommended to start with British Council courses and complement with Duolingo.
How long does it take to learn basic English?
It depends on your consistency. If you dedicate even a small amount of time daily, you should notice improvement within three months.
What’s the best free method for adults to learn English?
There isn’t just one method to learn English. Try combining practice across different language skills using interactive platforms.
Checking account
Debit Account in the United States
8 min de lectura
In this article, we'll walk you through the advantages and requirements of having a debit account in the United States. It's worth noting that the world's financial center is New York, home to the most important payment hubs where the world's top-ranked financial institutions are connected. That's why having an account in the United States is essential if you do business globally.
Why Having a Debit Account in the United States Matters
Here are the advantages of having a debit account in the United States and what it means to have one — among the most notable benefits:
Cost: The cost to open an account in the U.S. is actually minimal, largely thanks to the digital account types available today. This gives you the ability to handle financial transactions smoothly with the people you want to do business with.
Requirements: Requirements are usually basic, as long as you're of legal age and have some form of address documentation. If you're a foreigner, it's possible to open an account in the United States without a long list of requirements or needing to be physically present.
Control: You can track fees, deductions, and payments made through the platform — for that, we recommend reading: How to Manage My Money in a Debit Account.
Ideal for Freelancers: If you do remote work, global companies typically require an account on some payment platform. For that, you'll need a U.S.-based account. That's why it's worth opening one, so you can meet the requirements of that payment platform.
Security: You get the security that comes with U.S. regulation. On top of that, funds are protected by the Federal Deposit Insurance Corporation (FDIC).
Options: There's a wide variety of ways to get a U.S. account, and among the main options is starting with a debit account, which offers alternatives for people who want an account without being a U.S. resident.
General Requirements to Open an Account in the United States
The requirements listed here are for opening a general account — keep in mind that requirements vary by account type. Among the requirements U.S. financial institutions typically ask for:
ID document: Issued by your country of residence's government (passport, national ID, or identity card depending on your country of origin).
Proof of residence: A current utility bill showing your physical address. It must include a zip code.
Email address: So the confirmation email can be sent this way if you open the account through a platform or app.
Mobile device: To authenticate transactions made through the bank's platform.
If you want to open an account in the United States, there are several options and account types available. Just choose the one that fits your needs, requirements, and that you can comfortably and securely meet the requirements for.
International Money Transfers
What Are Remittances and How Do They Work from the U.S.?
8 min de lectura
Do you really know what remittances are? They are international money transfers made by people living and working abroad to family members or recipients in their home country.
For Latin American immigrants living in the United States, sending remittances is a crucial matter, as is having efficient financial services that allow them to send money to their families and friends quickly, safely, and at low cost.
According to recent sources, the flow of remittances from Mexico to the United States fell 12.4% year over year, which is attributed to recent immigration measures imposed by that country. For this reason, it is important that migrants have international money transfer services that understand their needs.

Why Do People Send Remittances?
For the families of migrant workers in the United States, remittances represent much more than a simple transfer of money, as they often become the main support for millions of people in Latin America.
These Are the Main Reasons to Send Remittances:
Household expense support (rent, utilities, food)
This category includes basic expenses such as food, rent, utility payments, and everything related to daily costs, highlighting the importance of remittances for recipient families.
Education and study tools
Includes payment of tuition, school supplies, transportation, preschool fees, and computing tools such as laptops or desktop computers.
Health and family emergencies
If any family member requires specialized medical care, remittances play a central role in covering hospitalization, medications, treatments, and more.
Targeted savings (e.g., family home improvements)
It is also common for migrants to use remittances to build or renovate their family homes, thereby improving their quality of life.
Unexpected expenses during travel or temporary stays
Remittances may also be useful to cover unexpected travel expenses, related to unforeseen illnesses, flight cancellations, or unplanned charges.
How Do Remittances Work and What Options Exist?
Currently, there are several remittance service options you can rely on to send money to your relatives.
Traditional banks, such as Bank of America and Wells Fargo, allow you to make remittance transfers through their digital banking services or directly at branches.
There are also specialized sending agencies, such as Western Union, one of the most widely used and longest-standing remittance services in the United States, with a global presence in more than 200 countries.
The information that traditional banks and agencies will generally require to send money includes:
- Beneficiary’s full name
- Beneficiary’s account number
- SWIFT code
- Receiving country
- Amount and currency
Finally, you can choose digital platforms, which allow you to send money through mobile apps and, in general, offer more competitive options regarding costs and delivery times.
Común is one of these platforms, integrating the fintech experience with various benefits, such as a digital account and an easy to use mobile app, that is available in Spanish. Común accepts more than 100 qualified official IDs from your country of origin to open an account and offers different options for receiving money: into a local bank account or cash pickup. With Común, send money to your relatives for clear and competitive rates, from $2.99 USD and send up to applicable limits.
These Are the Characteristics of Each Available Remittance Sending Option:
Traditional Banks
Traditional banks are a safe option to send money through wire transfer. The advantage is that they are fully established institutions in the U.S. financial system.
However, they have certain limitations, such as high fees, which can reach 60 USD depending on the bank. Additionally, transfers also tend to be slower, taking up to 5 business days.
To access this service, it is necessary to open a bank account at a traditional U.S. bank, or resort to sending cash directly at a branch.
Money Sending Agencies
Specialized agencies for international money transfer, such as Western Union, are also a reliable alternative you can use.
However, fees are usually high and exchange rates less competitive, similar to traditional banks. Although delivery times tend to be shorter.
Digital Platforms
If you are looking for an option to make international bank transfers, digital platforms are a great option. In addition to more accessible opening requirements, they offer far more competitive fees compared to the two previous alternatives.
Remember that Común offers you a comprehensive digital platform to connect with your loved ones in a simple and fair way.
Costs, Timeframes, and How to Save When Sending Remittances
The cost of sending remittances depends on three main factors:
- Sending fee: this is the commission charged by the provider for offering its sending services. This amount varies depending on the method, amount, receiving country, and involvement of intermediaries. The fee may be variable or fixed. One option is to choose a service with a fixed fee, to avoid paying more than expected.
- Exchange rate: a common practice among remittance services is not using the real market exchange rate, but adding a margin that reduces the total amount to be received.
For example, if the dollar price is 18 Mexican pesos, and the remittance service offers it at 17.50, when sending 500 USD, the total amount to be received will be reduced by 250 pesos.
- Possible charges to the recipient: Some traditional banks may charge fees for receiving transfers from foreign countries, so it is important to also verify the recipient’s conditions.
Good Savings Practices for Sending Remittances
To ensure your family receives the maximum amount possible, we recommend following these tips.
Check if there are margins in the exchange rate
The ideal choice is a provider that uses the real exchange rate or as close as possible. Otherwise, your recipient will receive a significantly smaller amount.
Prefer fixed and transparent fees
Understanding sending fees can be confusing, since several services use ranges that vary according to numerous criteria. The recommended approach is to look for a provider that offers fixed fees and with no hidden costs.
Always compare the amount received (not just the fee)
Remember that, in addition to the sending fee, you must consider the exchange rate and how much the amount to be received is reduced after applying this margin.
Avoid data errors to prevent delivery delays
Check your recipient’s information and make sure it is written correctly.
Consider the sending time and holidays in both countries
In many cases, transfers may be delayed if they are made on weekends or on holidays in either country.
Use platforms with support available in Spanish to resolve questions quickly
It is important to choose a service capable of answering your questions in your language and understanding your needs as a migrant.
Get Ready to Start Sending Remittances with Común
Every month, millions of dollars are sent from the United States to Latin America, representing an emotional and financial bridge between immigrant families and their homes, for whom remittances are a primary source of income.
Before choosing a remittance service, don’t forget to check the total amount your household will receive, considering the fee, exchange rate, and possible receiving charges. We recommend choosing a financial solution with transparent costs, support available in Spanish, and you can open your account with qualifying official ID from your country of origin.
Discover Común, the comprehensive platform that offers you low fees, with fees starting from $2.99, and send up to the applicable limits, and support available in Spanish. Open your account today and connect with your loved ones, send them money transparently.
Frequently Asked Questions (FAQ)
What happens if I don’t claim a remittance?
Remittances usually have a validity period established by the provider. Once that period expires, the money is not lost but the transaction may be canceled. In such cases, the sender may reissue it or request a refund depending on the provider’s policies.
What is the difference between a remittance and a transfer?
The main difference between the two lies in their intended purpose. Remittances are money transfers with a personal motive, commonly used to send money to relatives in other countries, whereas the purpose of a bank transfer can vary, ranging from commercial to personal payments, among others.
Living in the United States
Cashier’s Checks in the U.S.: Costs, Impact on Latinos, and Free Alternatives
8 min de lectura
Why is it so expensive to cash checks in the United States?
Without a bank account, people must turn to check-cashing stores that charge between 1% and 3% of the check amount. For a $1,000 check, that means $10-30 lost on each cash-out. Banks may also charge fees for depositing checks from other banks.
Why do Latinos disproportionately bear these costs?
Latino communities have less access to banking services because of barriers such as SSN requirements, language, and unfamiliarity with the system. Without a bank account, they are more likely to use check-cashing stores located in low-income areas that charge high fees.
Solutions for cashing checks at no cost
The best solution is to open a bank account. Común is a Spanish-language digital bank that allows you to open an account without an SSN using a passport or consular ID card. Once opened, you can deposit checks for free from the app using mobile deposit. There are also nonprofit organizations such as UnidosUS that offer free financial services to Latino communities.
Frequently asked questions about cashing checks in the U.S.
How much does it cost to cash a check in the U.S. without a bank account?
Check cashing stores typically charge between 1% and 3% of the check amount, with a minimum of $3-5. For a $1,000 payroll check, that means losing between $10 and $30 on each cash-out. Walmart Money Center charges lower fees ($4 for checks up to $1,000), but the cost is still higher than having a bank account.
Can I cash a check for free in the U.S.?
Yes, with a bank account. If you deposit the check at your own bank, there is no charge. With Común you can deposit checks by photographing them from the app, completely free. Some banks also allow you to deposit checks from other banks at no additional cost using mobile deposit.
Why do Latino immigrants pay more to cash checks?
The main reason is less access to bank accounts. Barriers include SSN requirements, language, unfamiliarity with the system, and fear of formal procedures. Without a bank account, they turn to check-cashing services that charge high fees. Platforms like Común remove these barriers by accepting Latin American IDs without an SSN.
What do I need to deposit a check in Común?
You only need the Común app and the physical check. Open the app, select “Deposit check,” take a photo of the front and back of the check (with your signature on the back), and the money is generally credited in 1-2 business days. There are no additional charges for the mobile deposit service.
What happens if someone pays me with a personal check from someone without a bank account?
Personal checks from people without sufficient funds or without an active account bounce (bounced check). If you deposit that check, the bank may temporarily hold the funds and then debit you the amount plus an NSF fee ($25-35). To receive payments more safely, prefer Zelle, Venmo, or direct transfers instead of personal checks from people you do not know well.
Is it better to receive payroll by check or by direct deposit?
Direct deposit is better in virtually all cases: the money arrives automatically on payday (or earlier with Común), there is no risk of the check being lost or stolen, there are no cashing fees, and you can access the funds immediately. With Común you can set up direct deposit from the app in minutes using your routing number and account number.
Financial Education
How to renew your ITIN: step-by-step guide
8 min de lectura
How to renew your ITIN: step-by-step guide
Your ITIN may have expired if you have not used it on a federal tax return for three consecutive tax years. To renew it, you must submit Form W-7 to the IRS, which is the same form used to apply for a new ITIN. You do not need to wait until tax season to start the renewal process, and you can submit your renewal before filing a tax return.
When does an ITIN expire?
An ITIN (Individual Taxpayer Identification Number) is a 9-digit tax processing number issued by the IRS. It is designed specifically for individuals who need to report income and file taxes in the United States but are ineligible for a Social Security Number (SSN).
An ITIN expires when it has not been used on a federal tax return for three consecutive tax years. The IRS explains that the expiration takes effect on December 31 of the third year of non-use.
An ITIN does not expire because time has passed, but because it has not been used for federal tax filing. Once expired, the number remains the same and can usually be renewed rather than replaced. An expired ITIN does not erase previous tax filings or financial records associated with it.
How do you know if your ITIN has expired?
One sign that an ITIN may have expired is not having filed a federal tax return with that number for several years. If three consecutive tax years have passed without using the ITIN, the number may no longer be active according to current IRS rules.
The IRS may also send a notice informing you that your ITIN needs to be renewed. Receiving a renewal notice does not mean there is a problem with your record. It simply means the IRS has determined that renewal is required before the number can be used again for tax filing purposes.
Tax software may also indicate that an ITIN has expired when preparing a return. If you are unsure if your ITIN has expired, checking IRS correspondence or reviewing past tax filings can also be a way to confirm status.
What happens if your ITIN expires?
An expired ITIN can delay the processing of a federal tax return. According to the IRS, certain tax credits and benefits associated with a return may not be available until the ITIN has been renewed.
An expired ITIN does not cancel previous tax filings, change your tax history, or create a new tax identity. The IRS maintains records associated with the original number even if that number has expired due to non-use.
An expired ITIN also does not automatically affect financial accounts that were opened using that number. However, an active ITIN may be required when completing future tax-related paperwork or applying for certain financial products and services.
If your ITIN has expired, the most practical step can be to start the renewal process before filing your next federal tax return. Taking action early can help avoid delays and additional paperwork during tax season.
What do you need to renew your ITIN?
To renew an ITIN, you must complete Form W-7 and mark it as a renewal application.
You also need documentation that proves identity and foreign status. The IRS lists acceptable documents in its official instructions, which include: passport, U.S. Citizenship and Immigration Services (USCIS) photo identification, visa issued by the U.S. Department of State, U.S. driver's license, foreign driver's license, foreign military identification card, national identification card (must contain name, photograph, address, date of birth, and expiration date), among others.
If your legal name has changed since your ITIN was issued, supporting documentation such as a marriage certificate or court order may be required.
How to renew your ITIN: step by step
1. Complete Form W-7
Fill out Form W-7 and indicate that you are renewing an existing ITIN. Make sure all personal details match your official documents.
2. Gather required documents
Collect identification documents that prove identity and foreign status. The IRS outlines acceptable documents in the Form W-7 instructions.
3. Attach supporting documentation
Include any additional documents required for your situation, such as name change records or prior IRS notices.
4. Submit your application
You can submit Form W-7 by mail, through an IRS-certified Acceptance Agent, or at select IRS Taxpayer Assistance Centers.
5. Wait for IRS processing
The IRS reviews the application and supporting documents before issuing confirmation. Keep copies of everything submitted for reference.
How long does ITIN renewal take?
Processing times vary throughout the year, but the IRS currently advises applicants to allow approximately seven to eleven weeks to receive notification regarding an ITIN application or renewal. Processing may take nine to eleven weeks during peak tax season or when applications are submitted from outside the United States.
Submitting a complete application can help prevent unnecessary delays. Applications that are missing required documents may take longer because the IRS must request additional information before processing can continue.
Can Común help me renew my ITIN?
Yes. Común's ITIN service helps with both new ITIN applications and ITIN renewals.
Común's ITIN service costs $199 and includes guidance throughout the renewal process. The service works with IRS-certified agents who help prepare the required paperwork, explain the requirements, and answer questions in Spanish.
The process can be completed from your phone, making it easier to organize documents and track progress without visiting multiple offices. Común also offers a money-back guarantee if the ITIN application is not approved according to the program terms.
FAQ
Do all ITINs expire?
Not all ITINs expire immediately or at the same time. An ITIN expires if it has not been used on a federal tax return for three consecutive tax years.
Can I renew my ITIN without filing taxes?
In some cases, yes. The IRS allows exceptions where Form W-7 can be submitted without a tax return depending on eligibility.
What form do I use to renew my ITIN?
You use Form W-7 for both new applications and renewals.
How long does it take to renew an ITIN in 2026?
The IRS estimates about seven weeks for processing. Processing may take approximately nine to eleven weeks during tax season or for certain international applications.
Can I still use my Común account if my ITIN expires?
An expired ITIN does not erase your financial history. If you have questions about how an expired ITIN may affect your specific account, contact Común directly for guidance.
What happens to my tax refund if my ITIN expires?
If an ITIN is expired, the IRS may delay processing a return until it is renewed. Certain tax benefits may not be available until the ITIN has been renewed, which can affect the timing of a refund.
Común is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank, Member FDIC. The Común Visa® Debit Card is issued by Community Federal Savings Bank.
Living in the United States
The cheapest states to rent in the United States in 2026
8 min de lectura
The cheapest states to rent in the United States in 2026
Based on recent rental market data, West Virginia continues to rank among the lowest-cost states for renters, with a 2025 Fair Market Rent of approximately $801 per month for a one-bedroom apartment. Arkansas and Mississippi also remain among the most affordable states to rent, with estimated one-bedroom Fair Market Rents of roughly $811 and $910 per month respectively. Other states frequently appearing among the cheapest states to rent include Oklahoma, Kansas, Iowa, Alabama, Indiana, Wyoming, and Ohio.
The national average asking rent for a one-bedroom apartment in the US sits at around $1,576 per month — a figure that can consume a significant share of the household's income. However, the average masks the variations across the country.
Why do rent prices vary so much by state?
Rent prices are not a single national market, they are thousands of local ones. The gap between the cheapest and most expensive states may be more than $1,600/month for a comparable unit. Several structural factors explain why a one-bedroom in Iowa can cost a fraction of what it does in California:
- Housing supply and construction pace. States with fewer building restrictions and lower land costs tend to have more available units, which keeps prices more accessible.
- Local economy and wages. Higher-income cities attract more renters competing for the same units, pushing prices up.
- Urban vs. rural mix. A state dominated by mid-sized cities will register lower averages than one anchored by major coastal cities.
- Regulatory environment. Zoning laws, permitting processes, and landlord-tenant regulations influence how fast housing supply can respond to demand.
- Climate and geography. Desirable coastal cities or warmer climates attract more people, which drives up rents over time.
The 10 cheapest states to rent in the U.S. in 2026
1. West Virginia — 1BR FMR: ~$801/month
West Virginia holds the lowest 1-bedroom Fair Market Rent of any state in the US at $801/month. The median rent statewide sits around $883/month across all unit types, with West Virginia apartments running roughly 41.6% less expensive than the national 2BR average. In 2024, 64.8% of leased homes in West Virginia rented for less than $1,000/month.
2. Arkansas — 1BR FMR: ~$811/month
Arkansas is consistently cited among the states with the lowest rent in the US. The 2025 HUD Fair Market Rent for a 1-bedroom is $811/month, and the state's apartments run roughly 41.4% less expensive than the national 2BR average. In 2024, 51.9% of leased homes in Arkansas rented for less than $1,000/month.
3. Mississippi — 1BR FMR: ~$910/month
The 2025 HUD Fair Market Rent for a 1-bedroom is $910/month, and some market-rate data places average 1BR asking rents lower, around $785–$825/month. In Jackson, the state capital, a 1-bedroom apartment may average around $785/month. The state has a notable Latino community in agricultural and food-processing hubs.
4. Oklahoma — 1BR avg: ~$850–$875/month
Oklahoma may offer some of the most affordable urban rent in the country. Oklahoma City's average 1BR rent sits around $875/month, ranking among the cheapest large cities to rent in the US. The state's housing index sits at approximately 67.9, meaning homes and rentals cost about 32% less than they do nationally.
5. Kansas — 1BR FMR: ~$885/month
Kansas delivers consistent affordability, with a 2025 HUD Fair Market Rent for a 1-bedroom at $885/month, roughly 35.6% below the national 2BR average. The median home price in Wichita, Kansas' largest city, was approximately $198,000 in Q1 2026.
6. Iowa — 1BR FMR: ~$839/month
The 2025 HUD Fair Market Rent for a 1-bedroom is $839/month, with Iowa apartments running 38.3% less expensive than the national 2BR average. Iowa households spend just 17% of their income on housing, the lowest share of any state in the country.
7. Alabama — 1BR FMR: ~$905/month
Alabama's apartments run roughly 36.4% less expensive than the national 2BR average. The 2025 HUD Fair Market Rent for a 1-bedroom is $905/month. The median home price of approximately $179,400 is among the lowest in the country. In 2024, 42.8% of leased homes in Alabama rented for less than $1,000/month.
8. Indiana — 1BR avg: ~$900–$950/month
Indiana sits comfortably in the affordable tier, with average 1BR rents well below $1,000/month in most markets. Indianapolis offers sub-$1,000 rents in a metro with a job market ranging from logistics, healthcare, technology, to life sciences. Indianapolis' growing Latino community has made the city an increasingly relevant destination for immigrant families relocating to the Midwest.
9. Wyoming — 1BR FMR: ~$836/month
Wyoming's sparse population keeps rental demand low and rents affordable. The 2025 HUD Fair Market Rent for a 1-bedroom is $836/month. In 2024, 50.2% of leased homes in Wyoming rented for less than $1,000/month. Wyoming has no state income tax.
10. Ohio — 1BR avg: ~$950–$1,000/month
Average 1BR rents hover near $950–$1,000/month while the state's cost of living runs roughly 8–9% below the national average. Ohio's combination of major metro accessibility and rental affordability makes it a compelling option.
Comparison table of the cheapest states to rent in the US (2026)
| State | 1BR FMR / Avg. Rent | vs. National 1BR FMR (~$1,393) | Cost of Living Index |
|---|---|---|---|
| West Virginia | $801 (FMR) | ~42% less | 83.2–86.6 |
| Arkansas | $811 (FMR) | ~42% less | 87.6 |
| Mississippi | $910 (FMR) | ~35% less | 83.3 |
| Oklahoma | ~$850–$875 (market) | ~37–39% less | 85.5–88.8 |
| Kansas | $885 (FMR) | ~36% less | 89.0 |
| Iowa | $839 (FMR) | ~40% less | 90.4 |
| Wyoming | $836 (FMR) | ~40% less | 92.3 |
| Alabama | $905 (FMR) | ~35% less | 89.3 |
| Indiana | ~$900–$950 (market) | ~32–35% less | 90.1 |
| Ohio | ~$950–$1,000 (market) | ~28–32% less | 91.2 |
1BR FMR = HUD Fair Market Rent FY2025. National 1BR FMR baseline: $1,393. Market-rate averages from PropertyCEO. Cost of Living Index from costoflivingbystate.com (C2ER Q1 2026). All figures are estimates and may vary by city, unit type, and data provider.
How to choose the right State for your budget and lifestyle?
Rent-to-income ratio, not just the rent number:
Some cheap-rent states also have lower wages. Mississippi, for example, ranks near the bottom for rent in dollars, but can rank near the top in terms of what percentage rent makes up of earned income.
Job availability in your field:
Employment opportunities can vary significantly from state to state. States such as Ohio, Indiana, and Alabama tend to have more diversified economies. For remote workers, lower-cost states may provide greater financial flexibility.
Community and support networks:
For immigrants and families relocating to a new area, access to established communities can make a major difference. Cities with growing Latino populations, bilingual services, and community organizations may help newcomers feel more connected.
Climate and weather risk:
States in the Midwest can experience colder winters and higher heating costs, while Southern states may bring higher air conditioning expenses. Some regions may also face increased risks related to hurricanes, tornadoes, or flooding.
Compare the total cost of living:
Rent is only one part of a household budget. Groceries, utilities, transportation, healthcare, childcare, and taxes can also vary significantly by state.
Manage your finances in any state with Común
Moving to a more affordable state may help reduce financial pressure, but managing your money efficiently remains important no matter where you live. Visit Común's website or download the app to learn more.
FAQ
What is the cheapest state to rent in the US in 2026?
Based on HUD Fair Market Rent data, West Virginia has the lowest 1BR FMR of any state at $801/month and the lowest median rent overall at approximately $883/month.
Which states have the lowest average rent for an apartment?
The states with the lowest average apartment rent in 2026 are West Virginia, Arkansas, Iowa, Wyoming, Mississippi, Oklahoma, Kansas, Alabama, and Indiana. Average 1-bedroom rents in these states range from approximately $785 to $950/month.
How much should I budget for rent in the US?
The commonly cited guideline is to spend no more than 30% of gross monthly income on rent. In the cheapest states, where 1BR rents may run $800–$900/month, the same guideline requires roughly $2,667–$3,000/month in gross income.







Thousands of immigrants are already achieving more with their money. You can too.
Comun is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank; Member FDIC. The Comun Visa® Debit Card is issued by Community Federal Savings Bank, pursuant to a license from Visa U.S.A Inc. and may be used everywhere Visa Cards are accepted.
Comun is a fintech company and not a bank or licensed money transmitter.
* Results may vary. For a complete list of eligible IDs and application requirements, follow this link.
^ No minimums, no maintenance fees. ATM or transfer fees may apply. See app for fee details.
‡ Direct deposit funds are typically available when we receive the payment file, up to two days before the scheduled payment date. This early availability is not guaranteed.
** A service provided by Service UniTeller, Inc. Service UniTeller, Inc. is licensed in all states that require a license. Remittance fees start at $2.99 but may vary. Please check the app for more details. Comun Inc. may earn revenue from the conversion of foreign currencies.
† Funds in your account are FDIC insured up to $250,000 by ownership category through Community Federal Savings Bank (CFSB), Member FDIC, in the event CFSB fails.


