
Checking account
What Is a Bank Account and What Are the Benefits of Having One?
What is a bank account and how does it work in the U.S.? Types of accounts, how to open one as an immigrant, and what to look for.
8 min read

04 Nov 2022

A bank account is a financial account a customer holds at a bank. A bank account lets customers deposit and withdraw money, as well as write checks. That's why it's also called a checking account.
The advantages of having a bank account include:
- Easy access to your money — 24/7 banking access through the bank's website or app
- No need to carry cash
- The ability to earn interest on your deposits
- Building a credit history, which can matter when you want to apply for a loan in the future
How Do You Open a Bank Account?
Opening a bank account is relatively easy. You'll need to provide some personal information, like your name, date of birth, and address. You'll also be asked for ID — usually a Social Security Number (SSN) is enough. More modern banks, like Común, let you replace your SSN with a passport or consular ID. You may also be asked for documentation proving your address.
The Different Types of Bank Accounts Available
There are different bank accounts to choose from. The most common type is the checking account, which lets you deposit and withdraw money and write checks. A checking account is a great option if you want easy access to your money without carrying cash, since your account's debit card lets you pay at any business.
Another common type of bank account is the savings account. Savings accounts let you save money and earn interest on your deposits. It's a great option if you want to build up your savings over time.
There are also several specialized bank accounts, like accounts for students, seniors, and businesses. Be sure to research the different bank accounts available and choose the one that best fits your needs.
How to Manage a Checking Account Online
Many bank customers choose to manage their bank account online. You can do this through the bank's website or app. Managing your bank account online lets you access it 24 hours a day, 7 days a week.
Some things you can do online include:
- View your account balance and transaction history
- Transfer money between savings and checking accounts
- Pay bills
- Pay your credit card
- Deposit checks
- Set up banking alerts for specific events, like a low balance or a large deposit
What Does It Cost to Open a Bank Account in the United States?
Some accounts, like the one Común offers, come with no monthly fee and no minimum balance requirement. However, many banks do charge fees. These include some of the most popular banks in the United States: Bank of America, JPMorgan Chase, Citigroup, and Wells Fargo. Here are some of the fees they charge:
- Monthly service fee
- Minimum balance requirement
- Overdraft fee
- Check-cashing fee
Certain banks also limit Spanish-language support in their digital interfaces or customer service centers. Be sure to research the fees charged and the language support offered before opening an account with any bank.
FDIC Backing
The Federal Deposit Insurance Corporation (FDIC) is a government agency that insures consumer deposits at banks in its network. It's important to choose a bank with this backing, since you'll have up to $250,000 of your funds insured by the U.S. government if your bank fails.
The Benefits of Común
At Común, you'll find a checking account with no monthly fee and no minimum balance, in Spanish (from the mobile app to customer support), with the flexibility to apply using your passport, no matter your nationality. Opening an account is very easy, and you'll have 24/7 access, along with the ability to pay bills or deposit checks. Común is FDIC-insured, so your funds are protected up to $250,000 USD.
As with any financial service, be sure to research the different options available and choose the one that best fits your needs.
About Común
Común aims to support the Latino community in the United States. It offers a debit account that can be opened with more than 100 valid Latin American IDs and an app available in Spanish.
Visit Común's website or download the app for free to learn more about the full offer and applicable terms.
Olivia Rhye
Community Partner

Financial Education
How to fill out a check in the United States in 5 simple steps (+ Example)
8 min de lectura
Have you ever filled out a check? Although most transactions today are digital, knowing how to fill out a check is essential—especially if you are just beginning your financial life.
According to recent data, one-third of Americans paid by check in 2024, demonstrating that checks still play an important role in the U.S. economy.
You might consider checks an outdated payment method; the reality is that they are useful in specific situations. For that reason, we will explain what a check is, the different types of checks, and how to complete them properly.
What Is a Check and What Is It Used For?
Despite the digital era, checks remain a relevant traditional payment method due to their formality and traceability. They are used for rent payments, purchases, and service payments.
Additionally, checks are a common payment method among the immigrant community, who often use them while adapting to the U.S. banking system.
But what exactly is a check and what are its characteristics? It is a physical document issued by an individual or business (the drawer) to order a bank to pay a specified amount to a third party. For the payment to be processed, the drawer must have sufficient funds in their checking account.
In general, a check contains the following information:
- Name of the drawer, whether an individual or a business
- Name of the payee
- Financial institution where the money will be drawn
- Amount to be paid, both in numbers and in words
- Signatures of the drawer
What Are the Different Types of Checks?
There are different types of checks in the United States. In this case, we will focus on the personal check, although you may choose the option that best suits your needs.
Personal Check
A personal check is a payment order issued by an individual to another individual using the funds in a checking account.
What Is a Personal Check Used For?
The most common uses for personal checks include:
- Rent and utility payments
- Purchase of everyday goods
- Legal agreements requiring documentary support
Certified Check
A certified check serves the same purpose as a personal check but is reviewed and guaranteed by the issuing bank, which verifies that the drawer has sufficient funds and holds them until the check is cashed.
A certified check provides certainty of available funds, making it a more secure method for making and receiving payments.
Cashier’s Check
Unlike a personal check, a cashier’s check is issued directly by the bank, offering greater security for the payee, as the bank is responsible for issuing and safeguarding the funds.
To obtain a cashier’s check, the drawer must visit a bank branch and pay the amount to be transferred. The bank then issues the check in the name of the payee, guaranteeing that it can be cashed using the institution’s own funds and not a personal account.
It is commonly used for high-value purchases such as homes and vehicles.
Money Order
While not strictly a check, it is a traditional payment method with similar functionality.
A money order is a financial instrument that allows funds to be sent via traditional mail using a certified check, which must be purchased and paid for by the drawer at an authorized location.
It allows secure money transfers without requiring a bank account.
How to Fill Out a Check in the U.S.
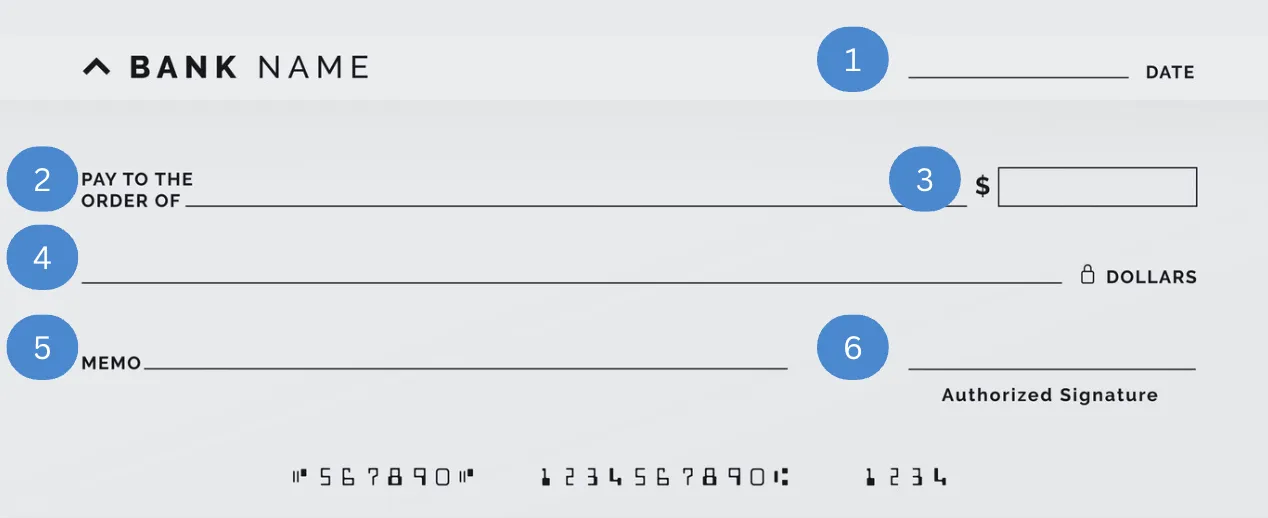
Before issuing this type of payment order, you must know how to do it properly. Below is an example of how to fill out a check easily, starting from step one:
1. Write the Date
Remember that in the United States, the date format is mm/dd/yyyy.
2. Payee’s Name
Write the full name of the person to whom you are issuing the check, exactly as it appears on their official identification.
3. Amount in Numbers
Write the numerical amount clearly.
4. Amount in Words
Write the amount in words, including cents.
5. Add a Memo
You may include a note specifying the reason for the payment.
6. Sign the Check
Sign the check legibly in the space designated for the drawer.
7. Review the Information
Ensure that all information is accurate to avoid issues for the payee when cashing the check.
It is essential to complete checks legibly, without strike-throughs or corrections, as these may invalidate the document.
How to Correctly Write Numbers in Words on a Check
Writing amounts in words may be confusing when dealing with U.S. dollars. The following points should be kept in mind:
- Dollar amounts must be written in full words
- Cents must be written as fractions
- Avoid using dollar symbols or similar notations
- If there is leftover space at the end of the line, draw a line to prevent fraud
- For example, $1,000.75 is written as: One thousand and 75/100 dollars
Cash Checks and Manage Your Money Easily with Comun
As you can see, knowing how to fill out a check is useful for sending and receiving money in the United States. It is a reliable and accessible alternative if you do not have a banking account.
However, issuing and cashing a check can also require significant time and effort. That’s why you can skip the trip to the bank, avoid wasting time or money on gas, and cash your check directly from your phone using Comun—no lines, no questions, no complications.
Discover Comun, the only platform designed to serve the needs of immigrant communities in the United States, with support available in Spanish.
Why Choose Comun?
- Open your account with an official ID from your country
- Access a mobile app specifically designed for immigrants in the U.S.
- Make payments, receive your salary, and manage your finances
- Send money to your loved ones in LATAM for just a $2.99 transfer fee
Frequently Asked Questions
Still have questions about how to fill out a personal check? See our FAQ section.
What if I Make a Mistake Filling Out a Check?
If there are strike-throughs or inconsistencies in the amounts, the check must be voided and a new one used.
How Do I Void a Check?
Write the word VOID in large letters on the front of the check.
What Information Appears on the Back of a Check?
The back of the check contains the endorsement, meaning the payee’s signature for cashing the check.

Living in the United States
How many numbers does a Social Security Number have? Format, meaning, and difference from an ITIN
8 min de lectura
How many numbers does a Social Security Number have? Format, meaning, and difference from an ITIN
The Social Security number (SSN) has 9 digits and is written in the format of XXX-XX-XXXX (for example 123-45-6789). An SSN is used to track earnings for taxes and benefits, access Social Security benefits, and verify identity for many activities such as applying for jobs, banking, accessing credit, and obtaining government services. It's one of the most sensitive personal identifiers in the U.S. You can find this number on your Social Security card, tax documents, and certain official government records.
What does each part of the Social Security number mean?
Historically, the SSN had meaning in each section. It followed a structure where the first three digits (known as the area number) were originally linked to the location where the SSN was issued. This was followed by the middle two digits (the group number), which had an administrative purpose. The last four digits (the serial number) were unique identifiers.
However, since 2011, these numbers no longer reflect location or order and are assigned using a 'randomization' system. The last four digits are often used for partial identity verification by financial institutions such as banks or credit unions, credit card issuers, government agencies, and healthcare providers.
How do I know if my SSN is valid?
There's no public tool to fully verify an SSN. You can confirm that it follows the 9-digit format, but official verification is performed through the Social Security Administration.
What is the Social Security number used for?
The SSN is a primary tax and financial identification number in the U.S. It is used across employment, financial, and government systems. Key uses include:
- Employment & Taxes: Required by employers for payroll processing and reporting income to the government
- Access to Government Benefits: Used by the Social Security Administration (SSA) to track lifetime earnings and determine eligibility for benefits, including retirement, disability, and Medicare
- Financial Services: Banks and financial institutions may require an SSN to open accounts and report interest income
- Credit & Loans: Credit bureaus use it to track credit history, and lenders use it to access creditworthiness
- Identification: Used by certain government agencies, for example the Department of Motor Vehicles in some states and for background checks
SSN vs. ITIN: What's the difference?
If you are not eligible for a Social Security Number (SSN) but have a U.S. federal tax obligation, you may need to apply for an Individual Taxpayer Identification Number (ITIN). Even though they are both nine digit numbers, they serve different purposes. The SSN is a nine-digit identification number issued to U.S. citizens and certain individuals authorized to work in the U.S. to report wages, access benefits, and establish credit history. An ITIN, on the other hand, is a tax processing number issued by the Internal Revenue Service (IRS) to individuals who are not eligible for an SSN but need to file U.S. tax returns.
Here are some key points to keep in mind:
- The ITIN also has 9 digits and typically starts with the number 9, the format 9XX-XX-XXXX
- The SSN is issued by the Social Security Administration, while the ITIN is issued by the IRS
- An SSN is generally issued to individuals authorized to work in the U.S., while an ITIN is used by individuals who need to meet tax obligations but are not eligible for an SSN
- An ITIN does not, by itself, authorize employment in the U.S. Work eligibility depends on immigration status and applicable laws
Both SSNs and ITINs may be accepted by some financial institutions to open checking or savings accounts, subject to each institution's policies.
Can I open a bank account without a SSN?
Policies vary by financial institution, but it may be possible. It can be challenging for newly arrived immigrants to open a bank account without an SSN; however, some institutions offer alternatives.
For example, certain banks may allow in-person account opening using an ITIN. Some community-focused credit unions may accept either an SSN or an ITIN. Other providers, such as Común, may offer digital account opening with more than 100 Latin American IDs.
Results may vary. For a complete list of eligible IDs and application requirements, follow this link to Común's Help Center.
How can you protect your Social Security number?
Your SSN is highly sensitive information, and protecting it is important to reduce the risk of identity theft. Here are some general tips:
- Whenever possible, avoid carrying the physical card. Try to keep the document in a safe place at home
- Avoid sharing your SSN unless it is necessary and you trust the requesting party
- Monitor your financial accounts and credit reports regularly for unauthorized activity
- Contact the Federal Trade Commission (FTC) if you suspect your SSN has been compromised
As a newly arrived immigrant, dealing with documentation can feel overwhelming. However, the good news is that you don't necessarily need to wait for an SSN to begin addressing your banking needs in the United States. Común's app is available in Spanish. Visit comun.app to learn more about account requirements.
FAQ
Can a Social Security number be changed?
Generally no, except in some exceptional cases, as determined by the Social Security Administration.
Do children born in the U.S. automatically receive a Social Security Number (SSN)?
An SSN is not issued automatically, but can be requested when the birth is registered.
How many digits does an ITIN have?
An ITIN has 9 digits, and typically starts with the number 9.
Is it mandatory to have an SSN to live in the United States?
No, an SSN is not required for residency.
Can I use someone else's Social Security number?
No, it's illegal and can result in serious legal consequences.

Financial Education
What is a W-2 form? Complete 2026 guide for immigrant workers in the U.S.
8 min de lectura
What is a W-2 form? Complete 2026 guide for immigrant workers in the U.S.
A W-2 form is one of the most important tax documents employees receive in the United States. If you worked for an employer during the year, your W-2 shows how much money you earned and how much money was withheld for taxes.
For many immigrant workers, this may also be the first time dealing with U.S. tax documents. Understanding how to read a W-2, when you should receive it, and what to do if something is incorrect can help you file taxes more confidently and avoid delays during tax season.
This article is for informational purposes only and does not constitute legal or tax advice. It is recommended to consult a qualified tax professional for guidance specific to your situation.
What is a W-2 form?
A W-2 form, officially called the Wage and Tax Statement, is a tax document employers send to employees every year. The form reports: total wages earned, federal income taxes withheld, Social Security and Medicare taxes withheld, state or local tax withholdings if applicable.
The IRS requires employers to provide a W-2 to employees who earned wages during the tax year. You typically receive a W-2 if you are considered an employee of a company. Independent contractors and certain gig workers generally receive Form 1099 rather than a W-2.
When should you receive your W-2?
Employers must send W-2 forms to employees by January 31 of the year following the reported tax year. If you haven't received your W-2 by early February, contact your employer. If you still don't receive it, you can contact the IRS for assistance.
What information does the W-2 contain?
- Box 1: Wages, tips, and other compensation
- Box 2: Federal income tax withheld
- Box 3: Social Security wages
- Box 4: Social Security tax withheld
- Box 5: Medicare wages
- Box 6: Medicare tax withheld
- Boxes 15–17: State tax information
W-2 vs. 1099: what is the difference?
| W-2 employee | 1099 contractor |
|---|---|
| Employer withholds taxes | Worker usually pays taxes independently |
| May receive benefits | Usually no employer benefits |
| Employer generally has greater control over work duties | Worker has more independence |
| Receives W-2 in January | Receives 1099-NEC if eligible |
Can ITIN holders get a W-2?
Yes. Employees can receive a W-2 using an ITIN instead of an SSN. If you are legally working in the U.S. with work authorization but do not yet have an SSN, you can use your ITIN for tax purposes. However, remember that an ITIN does not authorize employment on its own. For more information about ITINs, visit comun.app/itin.
What to do if your W-2 has errors?
If you find errors on your W-2, such as an incorrect name, SSN/ITIN, or incorrect figures: contact your employer immediately to request a corrected W-2 (Form W-2c), wait for the corrected W-2 before filing your tax return, if you cannot get a correct W-2 in time, the IRS has procedures to help you.
FAQ
What is the W-2 form?
It is the Wage and Tax Statement your employer sends you each January, showing how much you earned and how much you paid in taxes the previous year.
When will I receive my W-2?
No later than January 31 of the year following the reported tax year.
What do I do if I don't receive my W-2?
First contact your employer. If unresolved, you can contact the IRS for assistance.
This article is for informational purposes only and does not constitute legal or tax advice. Común is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank, Member FDIC.
Financial Education
How to Endorse a Check: Your Safe and Detailed Step-by-Step Guide
8 min de lectura
Despite the fact that digital payment methods have gained significant relevance practically worldwide, checks remain essential for carrying out certain transactions, especially for people without a banking account.
According to recent data, 61% of Americans still use checks. However, 17% have been victims of check fraud.
Knowing how to endorse a check in the United States is a necessary security measure to prevent fraud. While it can be a confusing procedure, it is crucial to understand it in order to avoid issues.
In this article, we will explain step-by-step how to correctly endorse checks, as well as the information you need to write on the back in order to cash the stated amount.
What Is a Check Endorsement and Why Is It So Important in the U.S.?
A check endorsement is a signature on the back of the check that serves as authorization for it to be cashed at a financial institution.
Its main function is to validate the cashing of the check, as well as authorize the transfer of funds, or to transfer the right to another person.
Knowing how to endorse a check is essential because it is a primary security requirement in the U.S. financial system, serving as a protection measure for the holder and the deposited funds.
What Is the Correct Way to Endorse a Check, and Where Should You Sign?
Below, we show you how to complete the endorsement before cashing checks at the bank.
Step 1: Verify the Check Details
Make sure the details on the front of the check are correct, such as the payee’s name, the amount in numbers and words, and the banking institution.
Step 2: Locate the Endorsement Area
Turn the check over and locate the statement “Endorse Here” or “Do not write below this line.” Avoid writing below the marked area.
Step 3: Sign the Check Precisely
Sign the check in the designated box, according to the type of endorsement you require. Next, we will explain everything about the different types.
But what should you do if the payee’s name is incorrect?
Example of How to Endorse a Check if the Name Is Misspelled
If the payee’s name is incorrect, you should first sign as it appears and then sign again with the corrected name.
James Smit — James Smith
Step 4: Consider a Restrictive Endorsement (Highly Recommended!)
A restrictive endorsement is a security measure to prevent an unauthorized third party from cashing the check, as it limits the form of payment to a registered banking account. It is linked to the information provided on the back of the check.
Step 5: Multiple-Payee Endorsements
If the check is made out to more than one payee, one or all may need to sign the endorsement, depending on how it is written.
- Katy Adams and Mark Palmer: Signatures from both are required
- Katy Adams or Mark Palmer: One signature is sufficient
- Katy Adams and/or Mark Palmer: Depending on the intermediary bank, one or two signatures may be required
- Katy Adams, Mark Palmer, etc.: The bank determines whether one or all signatures are necessary
Types of Endorsements: Know the Options for Your Checks
Before endorsing your check, verify which type is most suitable depending on the transaction you need to perform. For example, a restrictive endorsement is a way to secure your money, just like using modern financial alternatives such as Común, a comprehensive service that gives you access to unified and efficient financial tools.
Blank Endorsement
A blank endorsement is carried out when the same payee cashes the check in cash. In this case, only the signature in the designated area is needed.
Restrictive Endorsement
A restrictive endorsement is a security measure to ensure that the funds are deposited into a specific banking account.
To do this, you must include the statement “for deposit only to” + bank name, account number, and signature.
This is the most recommended method for Común users who make deposits via mobile, as it provides protection for the check in case of loss and ensures that the money is deposited into the designated account.
Third-Party Endorsement
If the check will be cashed by a third party, it must be endorsed as follows.
Pay to the order of: (name of another person) + signature
It is important to exercise extreme caution with this type of endorsement. Use it only with trusted individuals, and in case of theft or loss of a check, report it to the financial institution immediately.
Business Endorsement
A business endorsement is made when a check is cashed in the name of a company. This requires including the full name of the company, followed by the signature of the authorized legal representative.
Mobile Deposit Endorsement
To deposit check funds through a mobile application or mobile banking, it must be endorsed as follows:
For mobile deposit only + your signature.
Deposit your endorsed check easily and securely using Común
Cashing checks is a process that requires special care and attention in order to avoid mistakes and setbacks that could affect the transaction.
This time, we learned the importance of correctly endorsing a check in the United States, as well as the different types that exist, according to the available cashing methods.
Now that you know how to fill out a check on the back, you can rely on Común to deposit the funds through the mobile app.
Skip the lines: Deposit your check from the app; availability of funds may vary.
Común offers you the necessary security to protect your money and personal data
It is an accessible platform for immigrants in the United States; request to open your account with documentation from your country
Get customer support in English and Spanish, available 24/7
Access a comprehensive mobile app to manage your personal finances in the simplest way
Común will not only make the check deposit process easier, but it will also transform your financial life in the United States. Open your account today and find out.
Frequently Asked Questions
Is it mandatory to endorse a check in the United States?
In most cases, yes, it is necessary. If you request a deposit through an ATM or application, the bank may not require an endorsement.
What happens if I sign the check incorrectly when endorsing it?
Avoid cross-outs or scratches and endorse the check again. If the bank rejects it, ask the issuer to issue a new one.
Can I endorse a check to another person?
You can endorse a check so that it can be cashed by another person with the statement “pay to order of” along with the payee’s name. However, this process is restricted according to each bank’s specific policies.
Is it safe to deposit a check with the mobile app?
It is safe to deposit a check through the Común mobile app, as your data is encrypted and it includes other security measures such as two-step verification.
Instant payments
Direct deposit vs wire transfer: comparison guide for U.S. immigrants
8 min de lectura
Direct deposit vs wire transfer: comparison guide for U.S. immigrants
These payment methods are both available in the U.S. but they are often used for different purposes. Direct deposit is commonly used for paychecks, tax refunds, and government benefits, while wire transfers are more often used for urgent or high-value transfers between financial institutions.
Understanding the difference between direct deposit and wire transfers can help you avoid unnecessary fees, choose the right payment method for your situation, and manage your money more confidently.
What's the difference between direct deposit and wire transfer?
The biggest difference is the purpose they serve. Direct deposit is commonly used for recurring payments such as salaries, benefits, and tax refunds. Wire transfers are commonly used to move money quickly between financial institutions, particularly for large or time-sensitive transactions.
| Feature | Direct deposit | Wire transfer |
|---|---|---|
| Common use | Paychecks, benefits, tax refunds | Large or urgent transfers |
| Network used | ACH network | Wire transfer network |
| Speed | Typically 1–3 business days | Often same day or next business day |
| Typical cost | Often no fee to receive | Fees may apply |
| International transfers | Limited | Commonly used |
| Recurring payments | Yes | Less common |
| Setup required | Routing + account number | Bank details + recipient information |
How direct deposit works
Direct deposit is one of the most common payment methods in the United States, particularly for employees receiving wages from an employer. Instead of issuing a paper check, an employer sends the payment electronically to the employee's bank account through the ACH network.
To set up direct deposit you need to provide your employer: your bank's routing number and your personal account number.
How wire transfer works
A wire transfer is an electronic transfer of funds between financial institutions through secure financial networks like Fedwire or SWIFT. Unlike direct deposit, wire transfers are better suited for large one-time payments, urgent payments, real estate transactions, or international transfers.
When to use each one
Use direct deposit for:
- Receiving your paycheck
- IRS tax refunds
- Social security or unemployment benefits
- Recurring business payments
Use wire transfer for:
- Real estate payments (down payment, closing)
- Urgent international transfers
- High-value business payments
- When the recipient specifically requires a wire transfer
How to set up direct deposit with Común
With your Común account, you can set up direct deposit by providing your Común routing number and account number to your employer. Your Común account has unique routing and account numbers available in the app. Visit comun.app to learn more.
FAQ
Is direct deposit faster than wire transfer?
Not necessarily. Domestic wire transfers can be faster (same day), while direct deposits usually take 1-3 business days. However, many accounts offer early access to direct deposits up to 2 days early.
How much does it cost to set up direct deposit?
Setting up direct deposit is generally no fee. Employers use the ACH network to send payroll electronically at no charge to the employee.
Común is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank, Member FDIC.
International Money Transfers
What are remittances?
8 min de lectura
Living and working abroad? Remittances might be for you if you want to send money to family members, friends, or other beneficiaries in another country.
Remittance is money transfers from one person to another, usually across borders. They are most commonly sent by immigrants who send a portion of their income to support their families back home. However, remittances can also be personal gifts, financial support, or payments between relatives or friends who maintain social or economic ties despite the distance.
Do you know the difference between a remittance and a bank transfer payment?
Remittances can be money transfers, however what is commonly understood as remittances are voluntary person-to-person transfers, usually between family members. For example: a worker in Texas sending money to their parents in Mexico, a nurse in Florida sending money to her siblings in Honduras, or a student helping their grandparents in Guatemala. Bank transfers on the other hand, can include payments between companies, international trade payments, foreign direct investment, loans between corporations, or government aid.
In summary, remittances are personal, cross-border, person-to-person transfers.
How can you send remittances from the United States to Latin American countries?
Today there are more options than ever to send money to Latin America from the U.S. The process is usually very simple:
#1 Choose a remittance provider
Your remittance service provider can be a financial mobile application, a traditional bank like Wells Fargo, a specialized money transfer service like Western Union or MoneyGram, or a fintech company like Remitly.
#2 Select the destination country and delivery method
Each company offers different delivery options depending on their services and local partnerships. Delivery options vary in cost depending on the provider and the urgency.
#3 Enter the amount and confirm the exchange rate and fee
The amount received by the recipient varies by the exchange rate used by the provider and the service fee they charge. Some companies might charge no fees, but their business model relies on the exchange rate markup.
#4 Pay for the remittance
With so many options available, remittances can be paid with various methods including:
- Bank account (ACH).
- Debit card.
- Credit card (often the most expensive).
- Cash
#5 The recipient receives the money
It can take minutes to days for the recipient to receive the funds, depending on how the funds are received or by the type of remittance provider used to send the remittance.
How much does it cost to send remittances from the United States?
The total cost depends on two main factors:
1. Service fees
This is the fee the provider charges to send the remittance. It can range from $0 to over $20 USD per transaction depending on the provider and payment method used.
- Bank account: typically the cheapest.
- Debit card: mid-range cost.
- Credit card: most expensive (fees + potential interest)
2. Exchange rate costs
Some companies have different exchange rates, making the remittance more expensive even if the service fee is advertised as “$0.” Sometimes the fee for the service provider is included within the added margins in exchange rates.
3. Other possible additional costs
These may include cash pickup fees, limits for high transaction amounts, or fees charged by participating banks. It is important to understand the fees in remittance costs to be able to manage your funds in a way that makes sense to you.
What should you consider before sending money abroad from the United States?
To choose the best option, you can always consider:
- Total costs (fee + exchange rate). Sometimes comparing only the fixed fee is not enough to fully understand the cost of a remittance or transfer.
- Delivery time. If the recipient needs the money the same day, it could be best to choose an quick service.
- Delivery method. Cash pickup can be useful if the recipient doesn’t have a bank account. Other options include bank deposit or digital wallets, which can be practical and low-cost.
- Convenience for the sender. If you send money frequently, it is recommended to evaluate apps that allow saved recipients, automatic payments, recurring transfers, or exchange-rate alerts or options that adjust and serve your needs.
- Limits and requirements. Not all money transfer service providers are the same. Some services require government-issued identification to provide their services, while others require a U.S. bank account and, in some cases, proof of identity (some providers accept foreign passports as proof of identity to send remittances if the sender can prove residency in the United States) for large transfers.
What Companies Offer Remittance Services from the United States?
In the U.S., there are several types of companies offering remittance services:
Traditional money transfer companies, for example: Western Union, MoneyGram, and Ria Money Transfer. These companies have physical branches in many locations. Fees could be higher than alternatives and the exchange rates can be less competitive.
Traditional banks: However, not all banks provide this service, but institutions like Bank of America and Wells Fargo allow international transfers through online banking or in-branch. However, it is important to consider that the fees can reach up to $60 USD depending on the bank, and transfers can take up to 5 business days. For this option, a bank account with the institution is needed or cash transfers are done directly at a branch.
Digital first companies (apps): Examples include Remitly, Wise, WorldRemit, and Xoom (from PayPal). These companies can offer more competitive pricing and faster transfers. These options are presented as an alternative to traditional banks or Western Union. Comun is one of these platforms, combining a fintech experience with extra benefits like a digital account and an easy-to-use app available in Spanish.
Convenience stores: For example, Walmart offers in-person remittance services. For example companies like Comun can also offer services like cash funding in retails or ATM locations. With a Comun open account you can deposit cash at one of over 90,000 retail locations (Walmart, 7-Eleven, Walgreens, and more) and then complete the remittances conveniently from your app.
What do I need to send remittances from the United States to Latin American countries?
Requirements vary by provider and they depend on:
-How the remittance is sent, and
-How the remittance is received.
For example, if sending money for cash pickup, the most important information is the recipient’s full legal name as it appears on their official ID, since they’ll potentially need to present it to pick up the money.
For a bank-to-bank international transfer, the essential information includes the bank details for the receiving account.
Traditional banks and companies like Western Union generally require:
- Recipient’s full name.
- Recipient’s account number.
- SWIFT code.
- Receiving country.
- Amount and currency
How can you send remittances using Comun?
Sending a remittance with Comun is very simple. You have two options at the palm of your hand, you can send it through the app or via WhatsApp. Here’s a detailed step by step on how to do it:
Through the Comun App
- Open your Comun app.
- Select “Transfer.”
- Select “International.”
- Under “How do you want to send your money?”, choose “Through the app.”
- You’ll see the current exchange rate.
- Select an existing recipient or add a new one.
*To add a recipient, you’ll need: full name as on their ID, phone number, and—if sending a bank transfer—their bank details.
- Confirm the recipient’s information.
- Choose the transfer method (bank deposit or cash pickup; options vary by country).
- Enter the sender’s ID type and ID number.
- Confirm transfer details.
- Enter the amount (the calculator shows the amount the recipient will receive in local currency and the transfer fee).
- Confirm the transaction.
And that’s it—your remittance is sent!
Through Comun’s WhatsApp
- Start from our website (by selecting “Send Money”), which will show the WhatsApp option — or.
- From the app, select “Transfer.”
- Select “International.”
- Choose “Via WhatsApp.”
- Follow the conversation flow.
- Choose “Send money.”
- Confirm the country.
- Enter the amount.
- You’ll receive a confirmation message showing the amount to be received in local currency.
- Choose the delivery method.
- Provide the recipient’s details: full name, ID type, ID number, and bank account (if applicable).
- Confirm your remittance.
- Verify your identity through the verification steps.
And you’re done—your remittance is sent!
Best Practices for Sending Remittances
To make sure your get the best out of your hard-earned money, it is recommended to keep some good practices in mind:
1. Verify the exchange-rate margin
Ideally, choose a provider that uses an exchange rate as close as possible to the real market rate as this impacts the actual amount your recipient will receive. Understanding transaction costs can help make better financial decisions for your needs.
2. Look for transparent, fixed fees
Comparing fees can be confusing because many services use variable pricing based on multiple factors. Ideally it is recommended to choose a provider that offers fixed fees and transparent pricing.
3. Consider timing and holidays in both countries
Keep in mind that transfers may be delayed during weekends or holidays in either country, so processing times may be slower than on regular business days.
Immigration
The 100 Questions about American Citizenship in Spanish
8 min de lectura
The 100 Questions about American Citizenship in Spanish
Reaching the point where you're preparing for the citizenship exam is already a major milestone. It reflects time, effort, and a commitment to building your future in the United States.
In this guide, you'll find the 100 civic questions for the U.S. Citizenship exam provided by the U.S. Citizenship and Immigration Services (USCIS), the government agency that reviews and processes citizenship applications. These are the questions from the civics test, translated into Spanish with their answers and organized by category aimed to support you while you prepare. The exam is administered by USCIS and is oral, not written. You'll be asked up to 10 questions out of the 100.
How does the US citizenship test work?
The U.S. citizenship exam generally consists of two parts, an English test and a civics test. Understanding how each one of them works could make the process feel more manageable. The English evaluation is conducted through an interview, in which an officer evaluates your English language skills through simple speaking, reading, and writing exercises. In the civics portion, the officer asks up to 10 questions out of a list of 100. They are about U.S. history, government, geography and holidays. To pass the test you must answer at least 6 of them correctly. It is important to consider that this entire part of the exam is oral.
If you do not pass a section the first time, you will usually have a second opportunity to retake the failed portion within 60 to 90 days. To start the application for citizenship, you must submit a form called Form N-400, which is the official application for naturalization, and as of 2026, the filing cost is $760, however, fees are subject to change.
Who can take the exam in Spanish?
If you are 65 or older and have been a permanent resident for at least 20 years, you may qualify to take the civics test in Spanish. This special rule, provided by USCIS, is designed to make the process more accessible for long-term residents. In this case, you do not need to study all 100 questions, you only need to study 20 of the 100 questions. In our list we will mark them with an asterisk (*). It is recommended to always consult and review the specific requirements of your own case with the corresponding authorities.
The 100 Official Citizenship Civics Test Questions (with answers in Spanish)
Here you will find the 100 official questions that USCIS may ask you during your citizenship exam, along with their answers in Spanish. However, keep in mind that the actual interview is conducted in English, unless you qualify for an exemption.
Part A: The American government (questions 1-57)
Principles of American Democracy (1–12)
1. What is the supreme law of the land?
- the Constitution
2. What does the Constitution do?
- sets up the government
- defines the government
- protects basic rights of Americans
3. The idea of self-government is in the first three words of the Constitution. What are these words?
- We the People
4. What is an amendment?
- a change (to the Constitution)
- an addition (to the Constitution)
5. What do we call the first ten amendments to the Constitution?
- the Bill of Rights
6. What is one right or freedom from the First Amendment?*
- speech
- religion
- assembly
- press
- petition the government
7. How many amendments does the Constitution have?
- twenty-seven (27)
8. What did the Declaration of Independence do?
- announced our independence (from Great Britain)
- declared our independence (from Great Britain)
- said that the United States is free (from Great Britain)
9. What are two rights in the Declaration of Independence?
- life
- liberty
- pursuit of happiness
10. What is freedom of religion?
- You can practice any religion, or not practice a religion.
11. What is the economic system in the United States?*
- capitalist economy
- market economy
12. What is the "rule of law"?
- Everyone must follow the law.
- Leaders must obey the law.
- Government must obey the law.
- No one is above the law.
System of Government (13–47)
13. Name one branch or part of the government.*
- Congress
- legislative
- President
- executive
- the courts
- judicial
14. What stops one branch of government from becoming too powerful?
- checks and balances
- separation of powers
15. Who is in charge of the executive branch?
- the President
16. Who makes federal laws?
- Congress
- Senate and House (of Representatives)
- (U.S. or national) legislature
17. What are the two parts of the U.S. Congress?*
- the Senate and House (of Representatives)
18. How many U.S. Senators are there?
- one hundred (100)
19. We elect a U.S. Senator for how many years?
- six (6)
20. Who is one of your state's U.S. Senators now?*
- Answers will vary.
- [District of Columbia residents and residents of U.S. territories should answer that D.C. (or the territory where the applicant lives) has no U.S. Senators.]
21. The House of Representatives has how many voting members?
- four hundred thirty-five (435)
22. We elect a U.S. Representative for how many years?
- two (2)
23. Name your U.S. Representative.
- Answers will vary.
- [Residents of territories with nonvoting Delegates or Resident Commissioners may provide the name of that Delegate or Commissioner. Also acceptable is any statement that the territory has no (voting) Representatives in Congress.]
24. Who does a U.S. Senator represent?
- all people of the state
25. Why do some states have more Representatives than other states?
- (because of) the state's population
- (because) they have more people
- (because) some states have more people
26. We elect a President for how many years?
- four (4)
27. In what month do we vote for President?*
- November
28. What is the name of the President of the United States now?*
- Visit uscis.gov/citizenship/testupdates for the name of the President of the United States.
29. What is the name of the Vice President of the United States now?
- Visit uscis.gov/citizenship/testupdates for the name of the Vice President of the United States.
30. If the President can no longer serve, who becomes President?
- the Vice President
31. If both the President and the Vice President can no longer serve, who becomes President?
- the Speaker of the House
32. Who is the Commander in Chief of the military?
- the President
33. Who signs bills to become laws?
- the President
34. Who vetoes bills?
- the President
35. What does the President's Cabinet do?
- advises the President
36. What are two Cabinet-level positions?
- Secretary of Agriculture
- Secretary of Commerce
- Secretary of Defense
- Secretary of Education
- Secretary of Energy
- Secretary of Health and Human Services
- Secretary of Homeland Security
- Secretary of Housing and Urban Development
- Secretary of the Interior
- Secretary of Labor
- Secretary of State
- Secretary of Transportation
- Secretary of the Treasury
- Secretary of Veterans Affairs
- Attorney General
- Vice President
37. What does the judicial branch do?
- reviews laws
- explains laws
- resolves disputes (disagreements)
- decides if a law goes against the Constitution
38. What is the highest court in the United States?
- the Supreme Court
39. How many justices are on the Supreme Court?
- Visit uscis.gov/citizenship/testupdates for the number of justices on the Supreme Court.
40. Who is the Chief Justice of the United States now?
- Visit uscis.gov/citizenship/testupdates for the name of the Chief Justice of the United States.
41. Under our Constitution, some powers belong to the federal government. What is one power of the federal government?
- to print money
- to declare war
- to create an army
- to make treaties
42. Under our Constitution, some powers belong to the states. What is one power of the states?
- provide schooling and education
- provide protection (police)
- provide safety (fire departments)
- give a driver's license
- approve zoning and land use
43. Who is the Governor of your state now?
- Answers will vary. [District of Columbia residents should answer that D.C. does not have a Governor.]
44. What is the capital of your state?*
- Answers will vary. [District of Columbia residents should answer that D.C. is not a state and does not have a capital. Residents of U.S. territories should name the capital of the territory.]
45. What are the two major political parties in the United States?*
- Democratic and Republican
46. What is the political party of the President now?
- Visit uscis.gov/citizenship/testupdates for the political party of the President.
47. What is the name of the Speaker of the House of Representatives now?
- Visit uscis.gov/citizenship/testupdates for the name of the Speaker of the House of Representatives.
Rights and responsibilities (48–57)
48. There are four amendments to the Constitution about who can vote. Describe one of them.
- Citizens eighteen (18) and older (can vote).
- You don't have to pay (a poll tax) to vote.
- Any citizen can vote. (Women and men can vote.)
- A male citizen of any race (can vote).
49. What is one responsibility that is only for United States citizens?*
- serve on a jury
- vote in a federal election
50. Name one right only for United States citizens.
- vote in a federal election
- run for federal office
51. What are two rights of everyone living in the United States?
- freedom of expression
- freedom of speech
- freedom of assembly
- freedom to petition the government
- freedom of religion
- the right to bear arms
52. What do we show loyalty to when we say the Pledge of Allegiance?
- the United States
- the flag
53. What is one promise you make when you become a United States citizen?
- give up loyalty to other countries
- defend the Constitution and laws of the United States
- obey the laws of the United States
- serve in the U.S. military (if needed)
- serve (do important work for) the nation (if needed)
- be loyal to the United States
54. How old do citizens have to be to vote for President?*
- eighteen (18) and older
55. What are two ways that Americans can participate in their democracy?
- vote
- join a political party
- help with a campaign
- join a civic group
- join a community group
- give an elected official your opinion on an issue
- call Senators and Representatives
- publicly support or oppose an issue or policy
- run for office
- write to a newspaper
56. When is the last day you can send in federal income tax forms?*
- April 15
57. When must all men register for the Selective Service?
- at age eighteen (18)
- between eighteen (18) and twenty-six (26)
Part B: American history (questions 58-87)
Colonial Period and Independence
58. What is one reason colonists came to America?
- freedom
- political liberty
- religious freedom
- economic opportunity
- practice their religion
- escape persecution
59. Who lived in America before the Europeans arrived?
- American Indians
- Native Americans
60. What group of people was taken to America and sold as slaves?
- Africans
- people from Africa
61. Why did the colonists fight the British?
- because of high taxes (taxation without representation)
- because the British army stayed in their houses (boarding, quartering)
- because they didn't have self-government
62. Who wrote the Declaration of Independence?
- (Thomas) Jefferson
63. When was the Declaration of Independence adopted?
- July 4, 1776
64. There were 13 original states. Name three.
- New Hampshire
- Massachusetts
- Rhode Island
- Connecticut
- New York
- New Jersey
- Pennsylvania
- Delaware
- Maryland
- Virginia
- North Carolina
- South Carolina
- Georgia
65. What happened at the Constitutional Convention?
- The Constitution was written.
- The Founding Fathers wrote the Constitution.
66. When was the Constitution written?
- 1787
67. The Federalist Papers supported the passage of the U.S. Constitution. Name one of the writers.
- (James) Madison
- (Alexander) Hamilton
- (John) Jay
- Publius
68. What is one thing Benjamin Franklin is famous for?
- U.S. diplomat
- oldest member of the Constitutional Convention
- first Postmaster General of the United States
- writer of "Poor Richard's Almanac"
- started the first free libraries
69. Who is the "Father of Our Country"?
- (George) Washington
70. Who was the first President?*
- (George) Washington
1800s
71. What territory did the United States buy from France in 1803?
- the Louisiana Territory
- Louisiana
72. Name one war fought by the United States in the 1800s.
- War of 1812
- Mexican-American War
- Civil War
- Spanish-American War
73. Name the U.S. war between the North and the South.
- the Civil War
- the War between the States
74. Name one problem that led to the Civil War.
- slavery
- economic reasons
- states' rights
75. What was one important thing that Abraham Lincoln did?*
- freed the slaves (Emancipation Proclamation)
- saved (or preserved) the Union
- led the United States during the Civil War
76. What did the Emancipation Proclamation do?
- freed the slaves
- freed slaves in the Confederacy
- freed slaves in the Confederate states
- freed slaves in most Southern states
77. What did Susan B. Anthony do?
- fought for women's rights
- fought for civil rights
Recent American History and Other Important Historical Information
78. Name one war fought by the United States in the 1900s.*
- World War I
- World War II
- Korean War
- Vietnam War
- (Persian) Gulf War
79. Who was President during World War I?
- (Woodrow) Wilson
80. Who was President during the Great Depression and World War II?
- (Franklin) Roosevelt
81. Who did the United States fight in World War II?
- Japan, Germany, and Italy
82. Before he was President, Eisenhower was a general. What war was he in?
- World War II
83. During the Cold War, what was the main concern of the United States?
- Communism
84. What movement tried to end racial discrimination?
- civil rights (movement)
85. What did Martin Luther King, Jr. do?*
- fought for civil rights
- worked for equality for all Americans
86. What major event happened on September 11, 2001, in the United States?
- Terrorists attacked the United States.
87. Name one American Indian tribe in the United States.
- [USCIS Officers will be supplied with a list of federally recognized American Indian tribes.]
- Cherokee
- Navajo
- Sioux
- Chippewa
- Choctaw
- Pueblo
- Apache
- Iroquois
- Creek
- Blackfeet
- Seminole
- Cheyenne
- Arawak
- Shawnee
- Mohegan
- Huron
- Oneida
- Lakota
- Crow
- Teton
- Hopi
- Inuit
Part C: Geography and civic integration (questions 88-100)
Geography
88. Name one of the two longest rivers in the United States.
- Missouri (River)
- Mississippi (River)
89. What ocean is on the West Coast of the United States?
- Pacific (Ocean)
90. What ocean is on the East Coast of the United States?
- Atlantic (Ocean)
91. Name one U.S. territory.
- Puerto Rico
- U.S. Virgin Islands
- American Samoa
- Northern Mariana Islands
- Guam
92. Name one state that borders Canada.
- Maine
- New Hampshire
- Vermont
- New York
- Pennsylvania
- Ohio
- Michigan
- Minnesota
- North Dakota
- Montana
- Idaho
- Washington
- Alaska
93. Name one state that borders Mexico.
- California
- Arizona
- New Mexico
- Texas
94. What is the capital of the United States?*
- Washington, D.C.
95. Where is the Statue of Liberty?*
- New York (Harbor)
- Liberty Island
- [Also acceptable are New Jersey, near New York City, and on the Hudson (River).]
Symbols
96. Why does the flag have 13 stripes?
- because there were 13 original colonies
- because the stripes represent the original colonies
97. Why does the flag have 50 stars?*
- because there is one star for each state
- because each star represents a state
- because there are 50 states
98. What is the name of the national anthem?
- The Star-Spangled Banner
Holidays
99. When do we celebrate Independence Day?*
- July 4
100. Name two national U.S. holidays.
- New Year's Day
- Martin Luther King, Jr. Day
- Presidents' Day
- Memorial Day
- Independence Day
- Labor Day
- Columbus Day
- Veterans Day
- Thanksgiving
- Christmas
Frequently Asked Questions about the Citizenship Exam
How many questions are asked on the citizenship exam?
During the civics portion, an officer from USCIS will ask up to 10 questions out of a list of 100. You need to answer at least 6 correctly to pass this part of the test.
Is the citizenship exam in English or Spanish?
The exam is conducted in English, including both the English and civics portions. However, applicants who qualify for the 65/20 exemption can take the civics test in Spanish. Make sure you verify if the exemption applies in your specific case with the corresponding authorities.
What happens if I don't pass the exam the first time?
If you fail either the English or civics section, you are given a second opportunity to retake the part you did not pass. This second interview typically takes place within 60 to 90 days.
How much does the citizenship exam cost in 2026?
The exam itself does not have a separate fee, but it is included in the naturalization application. As of 2026, the cost to file Form N-400 is $760, though it's always a good idea to verify updates directly with USCIS.
Do the citizenship exam questions change?
The list of questions is updated occasionally by USCIS. The current version is based on the reinstated 2008 civics test, which remains the standard as of 2026.
Can I study the citizenship questions in Spanish?
Yes, many applicants study the questions in Spanish to better understand the content. However, the actual exam is conducted in English unless you qualify for an exemption like the 65/20 rule.
5 Tips for Studying for and Passing Your Citizenship Exam
Preparing for the citizenship test doesn't have to feel overwhelming. Approaching it with a plan and consistency could be the key for a smoother experience. Here are some general tips we've enlisted for preparing for your citizenship exam:
Study by category, avoid trying to learn all of them at once.
Break the 100 questions into topics like history, government, and geography. This makes it easier to understand patterns instead of trying to memorize everything in one go.
Practice your answers out loud.
The exam is oral, so it's important to get comfortable saying your answers, not just recognizing them. This helps with confidence during the interview.
Start with questions that change.
Aim to focus first on answers that can vary, like the current president or your state's senators. Learning these early helps you avoid confusion later in the process.
Use flashcards and try to study with someone.
Flashcards are a great tool for repetition and reinforcing memory. If possible try practicing with a friend or family member to simulate the real experience of being asked questions.
Don't panic if you don't know everything.
You don't need a perfect score. You only need to answer 6 out of 10 questions correctly, so focus on being consistent, not perfect.
Community
What You Need to Open an Account at Comun¹ 5
8 min de lectura
Unmatched Ease of Opening an Account
Opening a checking account with Comun is simple and hassle-free, addressing the barriers to financial exclusion typically faced by the immigrant community. Accepting over 100 forms of identification², including social security numbers from Latin American countries, Comun ensures that immigrants have access to essential banking services. The application process is quick, taking less than 5 minutes, and is free of additional or hidden fees, minimum balance requirements or monthly commissions. This inclusiveness is central to Comun's mission of fostering financial stability and growth.
Mobile Deposit Options
ComunComun offers a convenient mobile deposit feature that allows users to deposit cash at more than 88,000 locations in the United States, including major retailers such as Walgreens, Dollar General and Walmart. This extensive network ensures that users can easily find a deposit location near them, making the process of adding money to their accounts simple and hassle-free.
Traditional Banking: Although many traditional banks offer mobile deposit options, they often restrict these to check deposits through a mobile app. Cash deposits typically require a visit to an ATM or bank branch, which can be less convenient and more time-consuming than Comun's extensive cash deposit network.
Utility in Today's World: In today's fast-paced environment, the flexibility to deposit cash in a wide range of accessible locations is invaluable, especially for individuals who may not have easy access to traditional banking services or who work non-traditional hours when banks are closed.
International Remittances
ComunComun excels in facilitating international remittances⁴, allowing users to send money abroad quickly and with lower fees compared to many traditional banks and remittance services. The process is enhanced with real-time notifications, keeping the sender informed from the moment the money is sent until it is received.
Traditional Banking: Traditional banks generally offer international transfer services, but these can be expensive and slow, with transfers sometimes taking several days to complete. In addition, the fees associated with traditional bank remittances can be significantly higher.
Usefulness in Today's World: In a globalized economy, the ability to send money across borders quickly and affordably is crucial. Many families rely on remittances for financial support, and businesses need efficient ways to handle international transactions. Comun's streamlined and cost-effective service effectively meets these modern demands.
Advance Salary Access
Comun: Comun offers the ability to connect wages to the application and receive payment up to two days in advance³. This feature incurs no additional fees, providing significant relief during financial emergencies or when planning ahead.
Traditional Banking: Some traditional banks have begun to offer similar features, but they are often tied to specific types of accounts or require a minimum balance. The accessibility and ease of use of early access to Comun's salary is not always matched in traditional environments.
Usefulness in Today's World: With the rise of gig economy jobs and irregular pay schedules, having early access to wages can provide a buffer against financial instability. This feature is particularly valuable for those living paycheck to paycheck, offering a cushion that can help avoid overdraft fees and late payments.
Unlike traditional banking institutions, Comun's innovative features are designed to meet the needs of today's diverse and mobile population, particularly benefiting the immigrant community in the U.S. By providing services that offer greater convenience, lower costs and greater accessibility, Comun not only addresses common challenges faced by its users, but also empowers them toward greater financial freedom and stability. As we move toward a more interconnected and fast-paced world, the importance of responsive and inclusive financial services continues to grow, something Comun is uniquely positioned to offer.
Robust Security and Customer Support
Security and customer support are paramount at Comun. With FDIC-insured accounts and Visa protection on virtual Visa debit card transactions, Comun customers can manage their funds with confidence. Innovative security features such as biometric logins and instant transaction notifications keep your money safe. In addition, Comun offers 24/7 customer support in English and Spanish, ensuring that help is always available in your preferred language.
Commitment to Zero Fees and Upward Mobility
Comun stands out not only for offering zero fees for account opening, monthly maintenance or minimum balances, but also for its commitment to helping its users move up the financial ladder. Comun acts as a financial partner, supporting financial transactions without the burden of excessive fees. This commitment aligns with the goal of enabling upward mobility for immigrants, who contribute significantly to the U.S. economy.
Customized Features and Benefits
Comun goes beyond traditional financial services by offering features designed to meet the unique needs of the immigrant community. Users can send money abroad with low or no fees, deposit cash at more than 88,000 locations nationwide, including free ATM withdrawals, and connect their accounts to popular payment apps such as Zelle, CashApp and Venmo. Comun's platform also allows customers to receive their paychecks up to two days early through direct deposit, further enhancing their financial flexibility and stability.
Conclusion
Comun is not just a financial services provider, but a platform dedicated to transforming the banking experience for immigrants in the U.S. With its user-focused design, commitment to financial freedom and robust features, Comun is destined to become a vital tool for achieving financial stability and growth for its users. Whether you are looking to manage your daily finances or send money to loved ones abroad quickly and securely, Comun offers a reliable, inclusive and efficient banking solution.
Foundational Moment: Did you know?
Founded by entrepreneurs Mark Selcow and Andres Santos in New York, Comun was built to empower families and enable upward mobility, particularly for the immigrant family. The company has garnered significant investment from prominent firms such as Costanoa Ventures, FJ Labs and South Park Commons, underscoring the tremendous opportunity to serve the financial needs of immigrant families and improve the lives of every individual.
Living in the United States
How to Make Money Fast in the United States
8 min de lectura
Making money fast can be a necessity at any point in life, and for Latinos in the United States it can be an even greater challenge. But don’t worry, in this post we’ll give you some ideas and tips so you can make money quickly and improve your financial situation.
1. Find temporary jobs
Temporary jobs are a good option for making money quickly. Many companies hire temporary workers to cover demand during certain times of the year, such as the holiday season or tax season. Look on job websites like Indeed, Glassdoor, or Monster to find temporary jobs in your area.
2. Become a rideshare driver
If you have a car and a valid driver’s license, consider becoming a rideshare driver for services like Uber or Lyft. These services let you work on your own schedule and make money quickly. Plus, you can work as much or as little as you want.
3. Sell your skills
If you have skills you can sell, such as computer repair, graphic design, or language teaching, you can use online platforms like Fiverr or Upwork to connect with people who need your services. These platforms charge a commission for each completed job, but you can set your own prices and work on projects based on your availability.
4. Do yard work or cleaning jobs
Many people need help with yard work or cleaning, and this can be a good option for making money quickly. You can offer your services in your neighborhood or on websites like Craigslist. Make sure you have the right equipment and a good attitude to win regular customers.
5. Sell items you no longer need
Selling items you no longer need is a quick way to get extra cash. You can sell them online through websites like eBay or Amazon, or in person at a garage sale or flea market. If you have valuable items you no longer use, this can be an excellent option for making money quickly.
Remember that these are just some ideas for making money quickly. You can also look for jobs in the hospitality or customer service industry, offer house cleaning services, or take online surveys to earn extra money. The important thing is to find an option that fits your skills and needs.
Remember to connect your Común account to your job so you can receive your pay as quickly as possible — up to two days early. In your Común checking account, you can keep the income from your work at no cost and with the highest possible security.
Común debit cards are compatible with more than 57,000 ATMs in the United States for deposits and withdrawals, and they include Visa’s zero-liability protection policy. This means that any unauthorized charge will not be deducted from the balance in your checking account. Likewise, your bank account is insured by the FDIC up to $250,000 like any other legal bank.
Good luck!
Community
What You Need to Open an Account at Comun¹ 2
8 min de lectura
Unmatched Ease of Opening an Account
Opening a checking account with Comun is simple and hassle-free, addressing the barriers to financial exclusion typically faced by the immigrant community. Accepting over 100 forms of identification², including social security numbers from Latin American countries, Comun ensures that immigrants have access to essential banking services. The application process is quick, taking less than 5 minutes, and is free of additional or hidden fees, minimum balance requirements or monthly commissions. This inclusiveness is central to Comun's mission of fostering financial stability and growth.
Mobile Deposit Options
ComunComun offers a convenient mobile deposit feature that allows users to deposit cash at more than 88,000 locations in the United States, including major retailers such as Walgreens, Dollar General and Walmart. This extensive network ensures that users can easily find a deposit location near them, making the process of adding money to their accounts simple and hassle-free.
Traditional Banking: Although many traditional banks offer mobile deposit options, they often restrict these to check deposits through a mobile app. Cash deposits typically require a visit to an ATM or bank branch, which can be less convenient and more time-consuming than Comun's extensive cash deposit network.
Utility in Today's World: In today's fast-paced environment, the flexibility to deposit cash in a wide range of accessible locations is invaluable, especially for individuals who may not have easy access to traditional banking services or who work non-traditional hours when banks are closed.
International Remittances
ComunComun excels in facilitating international remittances⁴, allowing users to send money abroad quickly and with lower fees compared to many traditional banks and remittance services. The process is enhanced with real-time notifications, keeping the sender informed from the moment the money is sent until it is received.
Traditional Banking: Traditional banks generally offer international transfer services, but these can be expensive and slow, with transfers sometimes taking several days to complete. In addition, the fees associated with traditional bank remittances can be significantly higher.
Usefulness in Today's World: In a globalized economy, the ability to send money across borders quickly and affordably is crucial. Many families rely on remittances for financial support, and businesses need efficient ways to handle international transactions. Comun's streamlined and cost-effective service effectively meets these modern demands.
Advance Salary Access
Comun: Comun offers the ability to connect wages to the application and receive payment up to two days in advance³. This feature incurs no additional fees, providing significant relief during financial emergencies or when planning ahead.
Traditional Banking: Some traditional banks have begun to offer similar features, but they are often tied to specific types of accounts or require a minimum balance. The accessibility and ease of use of early access to Comun's salary is not always matched in traditional environments.
Usefulness in Today's World: With the rise of gig economy jobs and irregular pay schedules, having early access to wages can provide a buffer against financial instability. This feature is particularly valuable for those living paycheck to paycheck, offering a cushion that can help avoid overdraft fees and late payments.
Unlike traditional banking institutions, Comun's innovative features are designed to meet the needs of today's diverse and mobile population, particularly benefiting the immigrant community in the U.S. By providing services that offer greater convenience, lower costs and greater accessibility, Comun not only addresses common challenges faced by its users, but also empowers them toward greater financial freedom and stability. As we move toward a more interconnected and fast-paced world, the importance of responsive and inclusive financial services continues to grow, something Comun is uniquely positioned to offer.
Robust Security and Customer Support
Security and customer support are paramount at Comun. With FDIC-insured accounts and Visa protection on virtual Visa debit card transactions, Comun customers can manage their funds with confidence. Innovative security features such as biometric logins and instant transaction notifications keep your money safe. In addition, Comun offers 24/7 customer support in English and Spanish, ensuring that help is always available in your preferred language.
Commitment to Zero Fees and Upward Mobility
Comun stands out not only for offering zero fees for account opening, monthly maintenance or minimum balances, but also for its commitment to helping its users move up the financial ladder. Comun acts as a financial partner, supporting financial transactions without the burden of excessive fees. This commitment aligns with the goal of enabling upward mobility for immigrants, who contribute significantly to the U.S. economy.
Customized Features and Benefits
Comun goes beyond traditional financial services by offering features designed to meet the unique needs of the immigrant community. Users can send money abroad with low or no fees, deposit cash at more than 88,000 locations nationwide, including free ATM withdrawals, and connect their accounts to popular payment apps such as Zelle, CashApp and Venmo. Comun's platform also allows customers to receive their paychecks up to two days early through direct deposit, further enhancing their financial flexibility and stability.
Conclusion
Comun is not just a financial services provider, but a platform dedicated to transforming the banking experience for immigrants in the U.S. With its user-focused design, commitment to financial freedom and robust features, Comun is destined to become a vital tool for achieving financial stability and growth for its users. Whether you are looking to manage your daily finances or send money to loved ones abroad quickly and securely, Comun offers a reliable, inclusive and efficient banking solution.
Foundational Moment: Did you know?
Founded by entrepreneurs Mark Selcow and Andres Santos in New York, Comun was built to empower families and enable upward mobility, particularly for the immigrant family. The company has garnered significant investment from prominent firms such as Costanoa Ventures, FJ Labs and South Park Commons, underscoring the tremendous opportunity to serve the financial needs of immigrant families and improve the lives of every individual.

Community
How to Make a Bank Transfer Online | Común Guide
8 min de lectura
One of the great advantages of having an online account is being able to make bank transfers more quickly, easily, and securely. A bank transfer online is the sending of money from one account to another over the internet. You can do it by ACH (1-3 days, free), Zelle (instant, free), or wire transfer (same day, $15-$45). You only need the recipient’s account number or their phone/email if you use Zelle.
What is an online bank transfer?
An online bank transfer is the instruction you give your bank to move money from your account to another person’s or entity’s account, using digital channels (mobile app or website). There are several types of transfers, each with different speed, cost, and limit characteristics.
What types of bank transfers exist?
ACH Transfer
This is the standard method in the U.S. for transferring money between banks through the ACH (Automated Clearing House) payment network. It is free at most banks and funds arrive in 1-3 business days. Ideal for regular, non-urgent payments.
Zelle
An instant payment service between users of participating banks in the U.S. Transfers are free and instant (minutes). You only need the recipient’s phone number or email. Común is compatible with Zelle.
Wire Transfer
A direct transfer between banks domestically or internationally. It is the fastest method for large amounts (it can be same-day if initiated before the cutoff time). Typical cost: $15-$45 at traditional banks. Requires the recipient’s account number and routing number.
How do you make an online bank transfer step by step?
- Log in to your bank’s app or website
- Go to the "Transfers" or "Payments" section
- Select the type of transfer (ACH, Zelle, wire)
- Enter the recipient’s details: name, account number, and routing number (for ACH/wire) or phone/email (for Zelle)
- Enter the amount and date (immediate or scheduled)
- Review all details and confirm
- Save the transaction receipt
How much money can I transfer?
Limits vary by bank and account type. For ACH transfers, most banks allow between $1,000 and $10,000 per day for new users. With Zelle, the limit is set by your bank (Bank of America: $3,500/day; Wells Fargo: $2,500/day). Wire transfers typically have higher limits (up to $100,000 or more). For international transfers, limits are set by each service.
Frequently Asked Questions About Online Bank Transfers
How long does an online bank transfer take?
It depends on the method. Zelle: minutes. Standard ACH: 1-3 business days. Same-day ACH (premium option): hours. Domestic wire transfer: same day if initiated before the cutoff time (generally 3-4 PM local time). International wire transfer: 1-5 business days depending on the destination country.
What information do I need to make a transfer?
For ACH or wire transfer, you need: the recipient’s full name, bank account number, and routing number (9-digit routing number). For Zelle, the recipient’s registered phone number or email is enough. For international transfers, in addition to the receiving bank’s IBAN or SWIFT/BIC, you may also need CLABE (Mexico) or other local codes.
Can I cancel a bank transfer after sending it?
It depends on the type and how much time has passed. ACH: you can cancel if the bank has not yet processed it (typically within the first few hours). Zelle: not cancellable if the recipient is already registered. Wire transfer: difficult but possible if you act immediately; the bank charges a reversal fee. Always verify the recipient’s details before confirming any transfer.
Is there a limit to how many transfers I can make per month?
Banks may set limits on the number of transactions in addition to dollar limits. Some savings accounts limit you to 6 monthly transfers (Reg D regulation, although it was suspended in 2020). Checking accounts generally do not have a limit on the number of transfers. Check your account’s specific terms.
Are online bank transfers safe?
Yes, when you use regulated platforms. Banks use SSL encryption, two-factor authentication, and fraud monitoring. However, confirmed transfers are difficult to reverse, so always verify the recipient’s details. Be wary of any urgent transfer requests from people you do not know.
What do I need to receive a bank transfer?
To receive a transfer, you need a bank account with a routing number and account number. Común gives you both from the moment you open your account, with no SSN. Share your routing number and account number with whoever is sending you money, or your phone number if it is through Zelle.
International Money Transfers
Understanding Money Transfer Fees: How to Save on Your Transactions
8 min de lectura
What Are Money Transfers?
Money transfers are transactions where money moves from one person or entity to another, which can happen within the same country (domestic transfers) or across international borders (international transfers). These transactions can be handled through several methods, including:
- Bank Transfers: Money is sent from one bank account to another. This can be done through direct bank-to-bank transactions, wire transfers, or Automated Clearing House (ACH) transfers, with ACH transfer standing out as a common, cost-effective method for bank transfers.
- Online Payment Services: Platforms like PayPal, Venmo, and others let users send money electronically over the internet. Users generally link their bank accounts or credit cards to the service to fund transfers.
- Money Transfer Services: Companies like Western Union and MoneyGram specialize in transferring funds quickly, both domestically and internationally, without needing bank accounts. Money can be sent and received in person at service locations or through online platforms.
- Mobile Payments: Services built into smartphones, like Apple Pay or Google Pay, let users send money directly to others through mobile apps.
In a typical money transfer, the sender chooses a transfer method, provides the recipient's details (like bank account number, email, or phone number), and pays the transfer amount plus any applicable fees. The service then processes the transfer, converting funds into the recipient's currency if needed, before disbursing the money either directly to the recipient's bank account or making it available for pickup at a local service branch. Understanding the types of money transfers is crucial, since it highlights the range of options available to customers, including bank transfers, online payment services, and mobile payments, each with its own set of possible fees and considerations for domestic or international transfers. These transfers are governed by various financial regulations to prevent fraud, money laundering, and other illegal activity, ensuring the transaction's security and reliability.
Types of International Money Transfer Fees
When initiating a money transfer, consumers face several fees, crucial for managing financial commitments like a down payment or regular savings contributions. Flat fees and percentage-based fees are common in both domestic and international transfers, impacting everything from sending money to relatives abroad to paying international suppliers. Currency conversion fees play a significant role when transferring foreign currency, since they can reduce the amount received due to unfavorable exchange rates. Additionally, some banks offer lower currency conversion fees if you let them convert the funds before transferring, or if you provide the currency already converted. They may also offer lower fees for transfers sent in foreign currency and for recurring transfers, highlighting the importance of currency exchange in a transfer's total cost.
Third-party service charges, like intermediary banks or platforms such as Western Union, can also add up, especially in complex scenarios like international wire transfers where multiple financial institutions may be involved. Different banks or financial institutions have their own fees for money transfers, including fees for incoming and outgoing fund transfers. Consumers may face fees for incoming transfers and incoming wire transfers, which vary between financial institutions for both domestic and international transfers. Understanding these different fees helps users evaluate money transfer options more effectively, emphasizing the distinction between incoming and outgoing fees and the impact of currency conversion on total cost.
Click here and we'll explain everything you need to know about bank accounts in the U.S.
Comparing Costs Across Different Transfer Services
Costs to transfer money can vary widely between services like traditional banks, which may offer lower fees for ACH transfers compared to outgoing wire transfer fees, and digital platforms that specialize in international money transfers. It's crucial to compare how different services transfer funds, including banks and online platforms, to understand the range of methods available and their associated costs and fees for both domestic and international transfers. For example, banks charge different fees for incoming and outgoing wire transfers and may offer incentives like free wire transfers for maintaining certain account types, like checking or savings accounts.
Online platforms may offer competitive rates for international transfers but could include additional fees based on the transfer amount or speed. Encouraging the use of an online calculator, if available, can help consumers find the best deal by comparing the total costs associated with each service, considering both domestic and international options.
Impact of Payment Methods on Fees
Choosing the right payment method can significantly affect the fees incurred during a money transfer. For example, credit cards may involve higher fees when used for international money transfer charges due to processing fees and interest rates, while direct bank transfers from a checking account may offer lower fees for transferring money internationally.
Cash transactions, especially through services like Western Union, are immediate but may carry higher fees, particularly for in-person transfers. An international transfer, on the other hand, may incur additional charges related to exchange rates and fees specific to the services facilitating these transactions, like MoneyGram, Revolut, Wise, and Payoneer. Each method, from wire transfers to ACH transfers, has its own set of pros and cons, influencing the total cost and speed of the transaction. It's vital to understand these differences to choose the most cost-effective method for sending money both internationally and domestically.
How Currency Fluctuations Influence Transfer Costs
Exchange rates fluctuate, impacting the cost-effectiveness of international money transfers. The mid-market rate is the fairest rate but is often marked up by financial institutions to cover their services, affecting the amount of foreign currency received. For those who transfer money internationally on a regular basis, using tools that track exchange rates or opting for a money transfer service that offers rate locks can provide savings.
Strategies like monitoring the Federal Reserve's wire transfer network and exchange rate trends, or choosing moments of favorable currency strength, are essential for those who need to manage international bank account numbers or business transactions involving foreign partners.
Tips to Save Money and Reduce Transfer Fees
In today's world, efficiently managing money transfers is crucial, whether sending funds domestically or internationally. Understanding how to minimize fees can save you a significant amount of money over time. Here are some strategic tips for reducing transfer fees and making sure you get the most out of your transactions:
- Consolidate Transfers: Combining multiple small transfers into one larger transaction can significantly reduce fees, since many financial institutions offer lower fees for larger amounts.
- Explore Fee-Free Options: Research services that don't charge transfer fees or that offer a loyalty program that reduces or even eliminates certain fees for regular customers.
- Negotiate Fees: Contact your bank or transfer service to discuss personalized rates. Frequent users transferring large sums may have leverage to negotiate better terms.
- Timing Flexibility: When you make transfers can affect the fees you pay. Be flexible about when you send money — sometimes waiting for a less busy transfer period can result in lower fees.
- Choosing the Right Transfer Method: Use online transfer options whenever possible, since they can be more affordable than in-person transfers. For domestic transfers, consider using direct bank transfers or ACH transfers, which typically carry lower fees than wire transfers.
[⚠️ FLAGGED PARAGRAPH — translated faithfully below, but this mixes DDA account-opening with international remittance pricing in one paragraph and directly compares price against competitors. Recommend splitting into two separate paragraphs/sections before publishing, per your DDA/Remesas separation rule:]
You can also open a Común account, which offers a variety of transfer methods at low or no cost. Our customers can send international money transfers starting at $2.99, a fraction of what competitors charge, and get the added benefit of opening a U.S. bank account.
By adopting these strategies, you can effectively reduce the costs associated with money transfers. Always be sure to read the fine print and watch out for hidden fees. With the right approach, you can get the most out of your financial transactions and make sure more of your money reaches its intended destination.
Conclusion
In conclusion, understanding the many fees associated with money transfers is essential for anyone looking to manage their finances efficiently, whether for personal or business purposes. This article has explored the various types of fees, from flat and percentage-based fees to currency conversion fees and service charges, highlighting how they can affect your transactions. It has also provided insight into how to compare costs across different services, the impact of payment methods on fees, and how currency fluctuations influence transfer costs. Most importantly, it offered practical strategies for minimizing these fees, like consolidating transfers, negotiating better rates, being flexible with timing, and selecting the most cost-effective transfer method.
Armed with this knowledge, you can make more informed decisions, potentially saving a significant amount of money and avoiding unnecessary costs. Remember, the key to maximizing the value of your transfers lies in a deep understanding of fee structures and choosing the right strategies to mitigate these costs. As you navigate the complex world of financial transactions, take proactive steps to educate yourself and explore all available options to make sure your money works harder for you.







Thousands of immigrants are already achieving more with their money. You can too.
Comun is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank; Member FDIC. The Comun Visa® Debit Card is issued by Community Federal Savings Bank, pursuant to a license from Visa U.S.A Inc. and may be used everywhere Visa Cards are accepted.
Comun is a fintech company and not a bank or licensed money transmitter.
* Results may vary. For a complete list of eligible IDs and application requirements, follow this link.
^ No minimums, no maintenance fees. ATM or transfer fees may apply. See app for fee details.
‡ Direct deposit funds are typically available when we receive the payment file, up to two days before the scheduled payment date. This early availability is not guaranteed.
** A service provided by Service UniTeller, Inc. Service UniTeller, Inc. is licensed in all states that require a license. Remittance fees start at $2.99 but may vary. Please check the app for more details. Comun Inc. may earn revenue from the conversion of foreign currencies.
† Funds in your account are FDIC insured up to $250,000 by ownership category through Community Federal Savings Bank (CFSB), Member FDIC, in the event CFSB fails.


