
Community
Común: Digital Banking for Immigrants in the U.S.
Común does not have branches, but it has a team that supports its customers 24 hours a day, 7 days a week, from the.
8 min read

29 May 2024
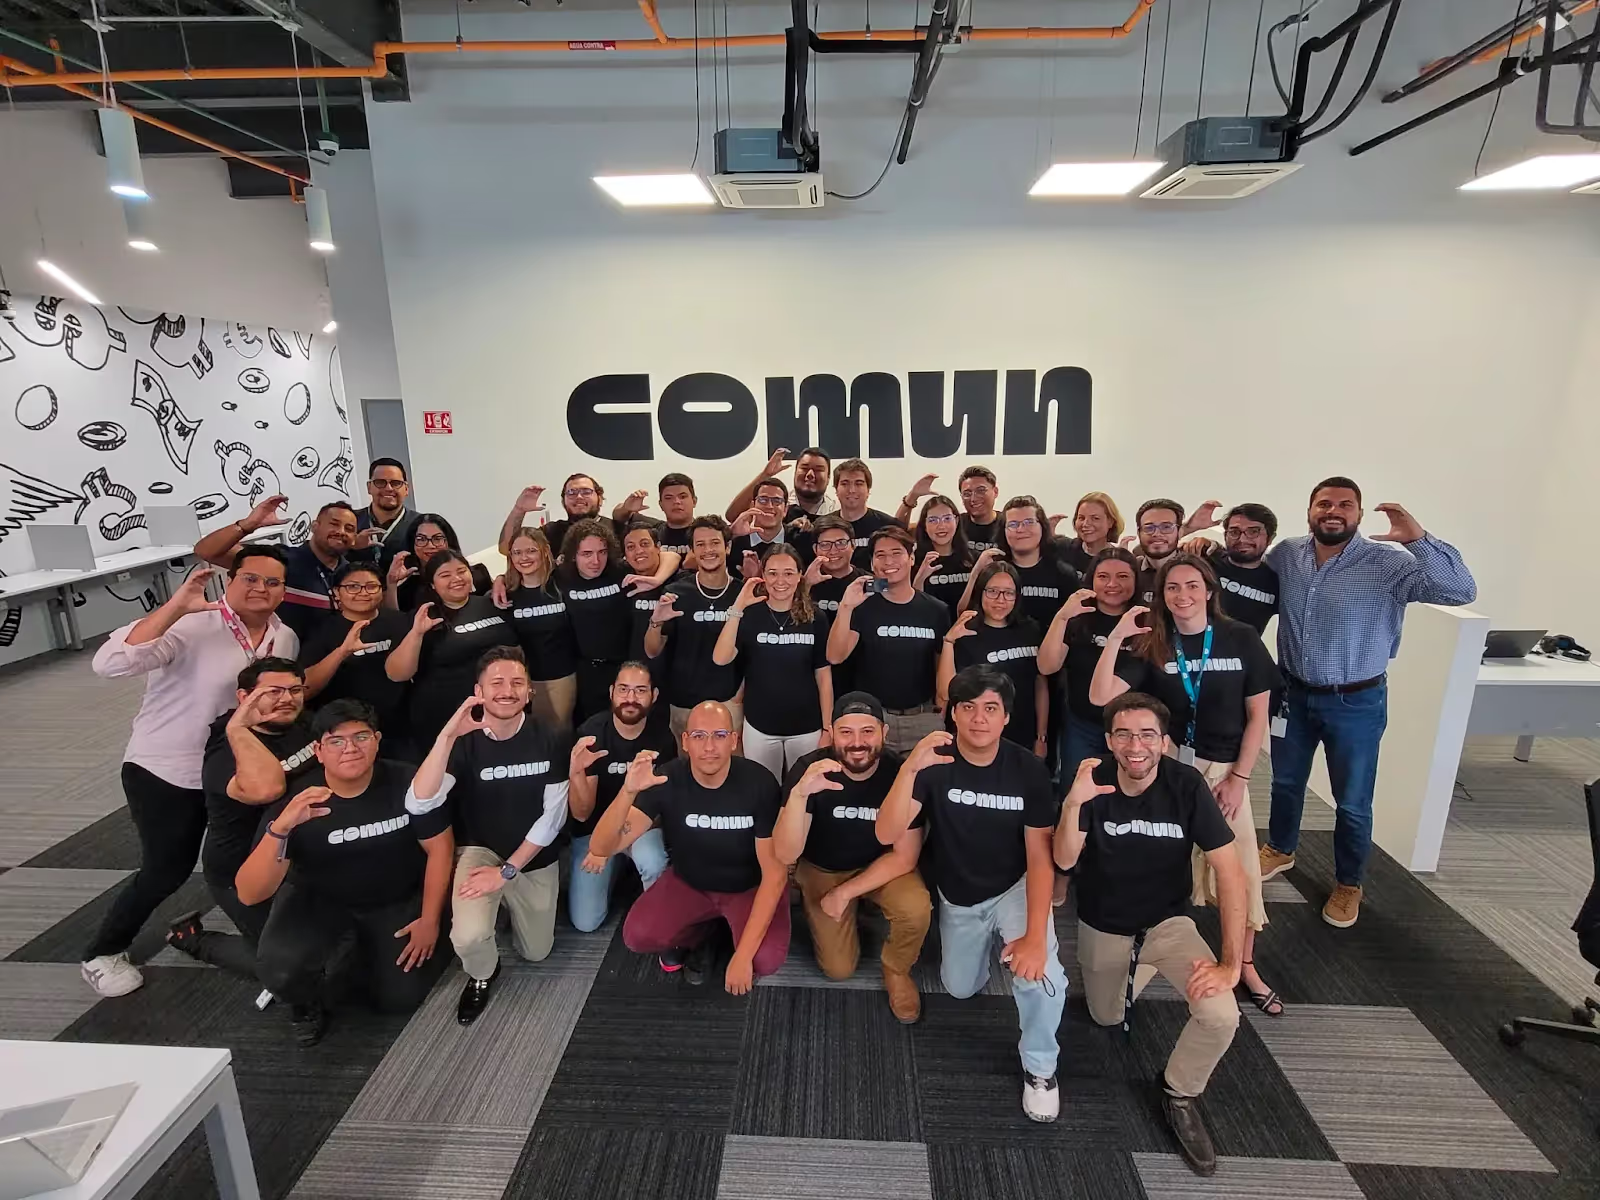
Común is a digital financial platform designed specifically for the immigrant community in the United States, letting you open an account with Latin American IDs, no Social Security Number required.
Común does not have branches, but it has a team that supports its customers 24 hours a day, 7 days a week, from the comfort of their homes, in three different languages.
Building a better future for immigrants in the U.S. is a core principle of Común’s mission. Accessible and easy-to-understand banking options are a key part of the immigrant journey. However, the options are scarce.
Complex, cumbersome, and expensive options are the norm. Activities that may seem trivial and intuitive to those born in the U.S. are overwhelming and confusing for a newly arrived immigrant. Everything from setting up direct deposit with an employer to sending money home, making payments for goods and services, or understanding how to build a credit score seems too complex for anyone who has never had to do this in the U.S., let alone at all.
Hidden fees and costly charges add another layer of stress when starting a financial life in the U.S. Between minimum account balances, monthly fees, overdraft charges, large check deposit fees, extortionate international transfer fees, and everything else, maintaining and using a bank account in the U.S. can be expensive. For manual laborers, this can represent a significant percentage of their wages.
The physical locations of traditional banks can also be scarce in some areas. Since opening a bank account or depositing a check or cash into the account must be done at a branch, this is a significant burden for someone living in a remote area. Many immigrants, sometimes working on remote farms or factories, live miles away from the nearest bank branch. Transportation costs to those branches add to the already high fees of using and maintaining an account.
Even if the banking services provided were more intuitive, digital, and lower cost, another major barrier remains. Obtaining the necessary documentation to open a bank account can also make access to fair and simple financial services difficult. Immigrants fortunate enough to have work authorization still need to gather important documentation that is not always available to them. For those who have come to the U.S. seeking asylum or better work opportunities through a more unconventional path, the documents required to open an account are often prohibitive.
Building a 100% digital banking platform to solve the issues mentioned above is part of what Común seeks to achieve because we believe in helping unlock social mobility. But a digital, low-cost, and intuitive platform is not enough. To navigate this process, immigrants need help, and help is best found in a Community that understands them when they need it most.
That is why not only our customers are part of our Community, but also the people who help them 24 hours a day, 7 days a week through our app, social media, WhatsApp, or by phone. Beyond solving an immediate problem, the support provided goes further. It teaches and educates, empathizes, and strives to foster a sense of Community among people who understand them, in terms they comprehend and in the language they speak. This is the core of true digital community banking. Our team helps them set up direct deposit, get refunds for charges they disagree with, and everything else.
At Común, the first step in this journey has already begun. Our team in Mérida, Mexico, is part of our Community and the one we seek to serve. They are an extension of our mission and our digital platform, and a necessary ingredient in unlocking social mobility for millions of immigrants in the U.S.
What makes Común different from a traditional bank?
Común accepts over 100 Latin American IDs (passport, consular ID, among others), doesn't require an SSN or ITIN, and doesn't charge a monthly fee or require a minimum balance.
How does Común specifically support the immigrant community?
With 100% Spanish-language support, an account opening process that takes minutes, and features built for common community needs, like low-cost remittances and cash deposit without needing a prior bank account.
What services does Común offer?
A checking account with a Visa debit card, international remittances starting at $2.99, cash deposit at over 88,000 locations, and direct deposit.
Frequently asked questions
Who is Común designed for?
For the Latin American immigrant community in the U.S. looking for accessible financial services without traditional documentation barriers.
What IDs does Común accept?
Over 100 Latin American IDs, including passports and consular IDs — no SSN or ITIN required.
Does Común charge an opening or maintenance fee?
No, there's no opening fee, monthly fee, or minimum balance required.
Is Común's support available in Spanish?
Yes, the app and customer support are available in Spanish.
How fast can I open my account?
The process takes about 3 minutes, with instant approval in most cases.
Does Común offer remittances to Latin America?
Yes, starting at $2.99 per transfer, with your first transfer at no cost.
About Común
Común aims to support the Latino community in the United States. It offers a debit account that can be opened with more than 100 valid Latin American IDs and an app available in Spanish.
Visit Común's website or download the app for free to learn more about the full offer and applicable terms.
Olivia Rhye
Community Partner

Living in the United States
Halloween and Día de Muertos: A Guide for Latino Families in the U.S.
8 min de lectura
Halloween and Día de Muertos fall on consecutive dates, October 31 through November 2, but they come from completely different traditions. Halloween has Celtic origins and is widely celebrated in the United States with costumes, trick-or-treating, candy, and spooky decorations. Día de Muertos is a celebration in Mexico that honors relatives who have passed, centered on ofrendas, favorite foods, and marigold flowers.
Because the two celebrations happen at nearly the same time, it's easy to wonder how they relate to each other. One focuses on costumes and neighborhood traditions, while the other is a time to remember loved ones who have passed. Many Latino families in the United States celebrate both, each with its own meaning. Understanding what makes each tradition unique can help preserve their significance while enjoying both.
What is Día de Muertos and where does it come from?
Día de Muertos is a Mexican tradition that honors the memory of relatives and loved ones who have died, observed on November 1 and 2. Its roots go back to pre-Hispanic cultures in Mesoamerica, including the Mexica, Maya, and Purépecha peoples, who saw death as a continuation of life rather than an ending. Over centuries, these Indigenous practices blended with Catholic traditions brought by Spanish colonizers, creating the celebration recognized today.
Families build ofrendas at home or at gravesites, placing photos, favorite dishes, candles, and marigolds to welcome the spirits back for a visit. UNESCO inscribed the celebration on its Representative List of the Intangible Cultural Heritage of Humanity in 2008, after originally proclaiming it in 2003. The holiday is about celebrating the lives of the people who have passed. Families gather, tell stories, prepare their favorite dishes, play their favorite music, and build ofrendas.
Some regions in Mexico celebrate slightly differently. In Michoacán, families spend the night at the cemetery with candles and food. In Oaxaca, comparsas (costumed parades) fill the streets. However, the heart of the celebration is honoring those who have passed by celebrating their lives.
What is Halloween and how is it celebrated in the U.S.?
Halloween is a tradition celebrated widely in the United States on October 31, a day when people wear costumes, children go trick-or-treating, families and friends carve pumpkins, and decorate their homes with haunted house decorations. It has roots in ancient Celtic festivals and later Christian observances, but in its modern form it is mostly a secular, community-based holiday for children and neighborhoods.
Halloween is widely celebrated across the United States, but it is not a federal public holiday, so schools and most workplaces stay open. Kids often dress up for school during the day and go trick-or-treating door to door in the evening. Neighborhoods decorate their yards with pumpkins, cobwebs, and lights weeks in advance.
For many Latino families in the United States, Halloween is one of the first traditions children experience at school and in their neighborhoods. Costume parades, classroom activities, and trick-or-treating are common parts of the celebration.
Halloween vs. Día de Muertos: key differences
Halloween and Día de Muertos take place within days of each other, which can make them easy to confuse. While both are widely celebrated during fall, they have different histories, traditions, and meanings. Being familiar with those differences can help you understand each better and celebrate accordingly.
- Purpose:
Halloween is playful and focuses on costumes and candy. Día de Muertos is a remembrance of loved ones who have passed. - Origin:
Halloween developed from Celtic and Christian traditions in Europe and later took its modern form in the U.S. On the other hand, Día de Muertos comes from Indigenous Mesoamerican beliefs blended with Catholic practice. - Symbols:
Halloween decorations include pumpkins, ghosts, and skeletons as spooky themes. Día de Muertos centers on marigolds, candles, pan de muerto and offerings with specific meanings. - Mood:
Halloween aims to scare or entertain. Día de Muertos aims to honor and reconnect, often with warmth rather than fear. - Status in the U.S.:
Halloween is a widely observed cultural tradition, not an official public holiday. Día de Muertos is increasingly recognized in U.S. cities with large Latino populations, through parades, museum exhibits, and school programs, though it is not a national holiday either.
Although the celebrations take place during the same time of year, each has its own history and purpose. Many families choose to celebrate both while preserving and embracing the traditions and cultural meaning of each one.
How to celebrate Día de Muertos in the United States
Día de Muertos is celebrated in many parts of the United States, especially in communities with a strong Mexican and Latino presence. Cultural centers, museums, schools, and community organizations often host public altars, festivals, parades, and educational events during the days leading up to November 1 and 2. These events offer an opportunity to learn about the tradition and take part in local celebrations.
Many families also observe Día de Muertos at home. The way it is celebrated varies from one household to another, but common traditions include:
- Setting up an ofrenda with photos and personal items of relatives who have passed.
- Preparing a favorite meal or drink of the person being remembered.
- Sharing stories and family memories with children and other relatives.
- Visiting a local Día de Muertos festival, museum exhibit, or community altar.
- Buying traditional foods such as pan de muerto from a nearby Mexican bakery or grocery store during the season.
Because Halloween and Día de Muertos take place within the same week, many families participate in both. Children may go trick-or-treating on October 31 while the family gathers on November 1 or 2 to remember loved ones and continue Día de Muertos traditions.
How to set up a traditional ofrenda
The ofrenda is built to welcome the spirits of deceased loved ones back for a visit. While designs vary by region and family, most ofrendas include the same elements that follow the tradition:
- Photos:
Pictures of the relatives being honored, placed at the center or top level. - Cempasúchil (marigold) flowers:
Their scent and bright color are believed to guide spirits back home. They're the most traditional flower for the occasion. - Pan de muerto:
A sweet bread shaped like bones, representing an offering shared with the departed. - Favorite foods and drinks:
Whatever the honored person enjoyed most in life, from mole to coffee to a favorite tequila. - Candles:
To light the path back for the spirit and represent hope. - Papel picado:
Cut tissue paper banners representing the wind and the connection between life and death. - Sugar skulls (calaveras):
Decorative and symbolic, representing the deceased with color rather than fear. - Salt and water:
Salt to purify the soul on its journey, water to quench its thirst after traveling.
Ofrendas are often arranged on two or three levels, symbolizing heaven, purgatory, and earth. But there is no single correct way to build one. Some families also include religious images, incense or seasonal fruit. However, it is very important to add something that had a special meaning for the person being remembered. That could be personal belongings, clothes, perfumes, but when you don’t have the items accessible, they can still be represented through colors, music or symbolic gestures. What matters is creating a space that reflects the memory of the loved ones being honored.
How to send money home so your family can celebrate Día de Muertos
Preparing for Día de Muertos often means buying flowers, candles, pan de muerto, ingredients for family recipes, and other items used to build an ofrenda. For families celebrating in Mexico or other parts of Latin America, money sent from relatives in the United States can help cover those seasonal expenses and support the holiday preparations.
If you plan to send money for the celebration, it's a good idea to do it before the end of October so your family has enough time to shop before November 1. Común Remittances allows eligible customers to send money from the United States to Mexico and other Latin American countries, with transfer fees starting at $2.99. Transfers typically arrive in less than 10 minutes, and money can be sent through the app without visiting a physical location. Eligible customers may be able to apply for a Común account with a valid passport, matrícula consular card, or more than 100 valid Latin American IDs.
Even from thousands of miles away, you can celebrate Día de Muertos whether it's in the US or by supporting your loved ones back home. Marigolds and pan de muerto make the celebration special but what matters most is honoring those who have passed by celebrating their lives in any way that you might find meaningful.
FAQ
What is the difference between Halloween and Día de Muertos?
Halloween is a tradition widely celebrated in the United States, focused on costumes, candy, and spooky fun, celebrated October 31. Día de Muertos is a Mexican tradition that honors deceased loved ones through ofrendas, food, and flowers, celebrated on November 1 and 2.
Is Día de Muertos celebrated in the United States?
Yes. Cities with large Latino populations hold public festivals, parades, and museum exhibits for Día de Muertos. Many families also celebrate at home with a private ofrenda.
What goes on a Día de Muertos ofrenda?
An ofrenda can include photos of the deceased, marigold flowers, pan de muerto, favorite foods and drinks, candles, papel picado, and sugar skulls. Salt and water are often included to represent purification and rest after the spirit's journey.
What do families in Mexico typically buy to prepare for Día de Muertos?
Marigolds, candles, pan de muerto, ingredients for the meal being offered, and materials for the ofrenda. Many families in the U.S. send money home to help with these costs.
How do I explain Día de Muertos to my U.S.-born children?
Focus on remembrance rather than fear. Share photos and stories about relatives who have passed, and let kids help build the ofrenda so they understand it as a way of keeping memory alive, not something scary.
What flowers are traditional for Día de Muertos?
Cempasúchil, also known as marigold, is the most traditional flower. Its bright color and strong scent are believed to guide spirits to the ofrenda so they can enjoy their favorite meal or drink.
Común is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank, Member FDIC. The Común Visa® Debit Card is issued by Community Federal Savings Bank, pursuant to a license from Visa U.S.A. Inc. and may be used everywhere Visa debit cards are accepted.
Remittance service provided by Service UniTeller, Inc. Service UniTeller, Inc. is licensed in all states that require a license.
Remittance fees start at $2.99, but may vary. Please check the app for more details.
Común Inc. may earn revenue from the conversion of foreign currencies.

Living in the United States
How many numbers does a Social Security Number have? Format, meaning, and difference from an ITIN
8 min de lectura
How many numbers does a Social Security Number have? Format, meaning, and difference from an ITIN
The Social Security number (SSN) has 9 digits and is written in the format of XXX-XX-XXXX (for example 123-45-6789). An SSN is used to track earnings for taxes and benefits, access Social Security benefits, and verify identity for many activities such as applying for jobs, banking, accessing credit, and obtaining government services. It's one of the most sensitive personal identifiers in the U.S. You can find this number on your Social Security card, tax documents, and certain official government records.
What does each part of the Social Security number mean?
Historically, the SSN had meaning in each section. It followed a structure where the first three digits (known as the area number) were originally linked to the location where the SSN was issued. This was followed by the middle two digits (the group number), which had an administrative purpose. The last four digits (the serial number) were unique identifiers.
However, since 2011, these numbers no longer reflect location or order and are assigned using a 'randomization' system. The last four digits are often used for partial identity verification by financial institutions such as banks or credit unions, credit card issuers, government agencies, and healthcare providers.
How do I know if my SSN is valid?
There's no public tool to fully verify an SSN. You can confirm that it follows the 9-digit format, but official verification is performed through the Social Security Administration.
What is the Social Security number used for?
The SSN is a primary tax and financial identification number in the U.S. It is used across employment, financial, and government systems. Key uses include:
- Employment & Taxes: Required by employers for payroll processing and reporting income to the government
- Access to Government Benefits: Used by the Social Security Administration (SSA) to track lifetime earnings and determine eligibility for benefits, including retirement, disability, and Medicare
- Financial Services: Banks and financial institutions may require an SSN to open accounts and report interest income
- Credit & Loans: Credit bureaus use it to track credit history, and lenders use it to access creditworthiness
- Identification: Used by certain government agencies, for example the Department of Motor Vehicles in some states and for background checks
SSN vs. ITIN: What's the difference?
If you are not eligible for a Social Security Number (SSN) but have a U.S. federal tax obligation, you may need to apply for an Individual Taxpayer Identification Number (ITIN). Even though they are both nine digit numbers, they serve different purposes. The SSN is a nine-digit identification number issued to U.S. citizens and certain individuals authorized to work in the U.S. to report wages, access benefits, and establish credit history. An ITIN, on the other hand, is a tax processing number issued by the Internal Revenue Service (IRS) to individuals who are not eligible for an SSN but need to file U.S. tax returns.
Here are some key points to keep in mind:
- The ITIN also has 9 digits and typically starts with the number 9, the format 9XX-XX-XXXX
- The SSN is issued by the Social Security Administration, while the ITIN is issued by the IRS
- An SSN is generally issued to individuals authorized to work in the U.S., while an ITIN is used by individuals who need to meet tax obligations but are not eligible for an SSN
- An ITIN does not, by itself, authorize employment in the U.S. Work eligibility depends on immigration status and applicable laws
Both SSNs and ITINs may be accepted by some financial institutions to open checking or savings accounts, subject to each institution's policies.
Can I open a bank account without a SSN?
Policies vary by financial institution, but it may be possible. It can be challenging for newly arrived immigrants to open a bank account without an SSN; however, some institutions offer alternatives.
For example, certain banks may allow in-person account opening using an ITIN. Some community-focused credit unions may accept either an SSN or an ITIN. Other providers, such as Común, may offer digital account opening with more than 100 Latin American IDs.
Results may vary. For a complete list of eligible IDs and application requirements, follow this link to Común's Help Center.
How can you protect your Social Security number?
Your SSN is highly sensitive information, and protecting it is important to reduce the risk of identity theft. Here are some general tips:
- Whenever possible, avoid carrying the physical card. Try to keep the document in a safe place at home
- Avoid sharing your SSN unless it is necessary and you trust the requesting party
- Monitor your financial accounts and credit reports regularly for unauthorized activity
- Contact the Federal Trade Commission (FTC) if you suspect your SSN has been compromised
As a newly arrived immigrant, dealing with documentation can feel overwhelming. However, the good news is that you don't necessarily need to wait for an SSN to begin addressing your banking needs in the United States. Común's app is available in Spanish. Visit comun.app to learn more about account requirements.
FAQ
Can a Social Security number be changed?
Generally no, except in some exceptional cases, as determined by the Social Security Administration.
Do children born in the U.S. automatically receive a Social Security Number (SSN)?
An SSN is not issued automatically, but can be requested when the birth is registered.
How many digits does an ITIN have?
An ITIN has 9 digits, and typically starts with the number 9.
Is it mandatory to have an SSN to live in the United States?
No, an SSN is not required for residency.
Can I use someone else's Social Security number?
No, it's illegal and can result in serious legal consequences.
Checking account
How to Identify Where to Deposit Cash
8 min de lectura
To deposit cash with Común, open the app, go to the "Cash" section and then "Deposit" to see all nearby locations on the map. You can generate a barcode and deposit without needing your physical card.
Depositing cash into your Común account is simple and convenient. Whether you prefer using your physical card at an AllPoint+ ATM or generating a barcode in the app, here is a step-by-step guide to help you understand both methods.
Using a Physical Card
Step 1: Wait for Your Physical Card
After opening your online bank account, your physical debit card will be mailed to your home. This usually takes 7 to 10 business days.
Step 2: Activate Your Card
Before you can use your card, make sure to activate it through the Común app. Your card must be active for any transaction.
Step 3: Locate an AllPoint+ ATM
AllPoint+ ATMs are part of a broad network of ATMs, perfect for cash deposits. Here is how to find one:
- Open the Común app.
- Go to the "Move Money" section.
- Use the map to locate the nearest AllPoint+ ATM. These machines are usually found at popular retail locations.
Step 4: Deposit Cash at an AllPoint+ ATM
Once you are at the ATM:
- Insert your activated card.
- Follow the on-screen instructions to deposit cash into your checking account. Please note that deposits can only be made into checking accounts, not savings accounts.
- Make sure your deposit is within the limits: up to $250 per deposit and up to $1,000 per day, including deposits and withdrawals.
Tip: If there are no AllPoint+ ATMs near you, do not worry. You can also deposit cash using a barcode at many other locations!
Using the Barcode in the App
Step 1: Generate a Barcode
Here is how to generate a barcode in the Común app:
- Open the app and go to the "Cash" section.
- Select the option to generate a barcode for deposit.
- The barcode will appear on your screen, ready to use.
Step 2: Find Locations That Accept the Barcode
To find a nearby location that accepts the barcode:
- In the "Cash" section, look for the list of participating locations.
- You can also use the map feature to find the nearest store.
Step 3: Using the Barcode
Take your barcode to a participating location and show it to the cashier. They will scan the barcode, allowing you to deposit your cash.
Important Details:
- Expiration: The barcode expires after 15 minutes, but you can generate as many as you need.
- Limits: Keep in mind the deposit limits that may apply when using the barcode method.
Troubleshooting ATM Transactions
Problems Depositing Money
When troubleshooting ATM transactions, especially problems depositing money, it is important to make sure you are using an AllPoint+ ATM, since these machines do not charge fees for deposits. Your physical card must be activated; if it is not, you can easily activate it from the app. Also, make sure you enter the correct PIN. If you do not remember your PIN, you can view it or change it in the app settings section. Verify that your deposit is within the limits, which are up to $250 per deposit and up to $1,000 per day. Finally, always select "checking account," since Común accounts are checking accounts, not savings accounts.
Problems Withdrawing Money
If you run into problems withdrawing money, first make sure you have enough balance by checking your balance in the app before making a withdrawal. Use an AllPoint+ ATM to avoid withdrawal fees, since other ATMs may charge a fee. Enter the correct PIN; if you do not remember your PIN, you can view it or change it in the app settings section. Verify that your withdrawal is within the limits, which are up to $250 per withdrawal and up to $1,000 per day, including deposits and withdrawals. If you continue having problems, contact us through the chat in your app for more help.
Alternative Deposit Methods
If you cannot find a nearby store to deposit cash, Común offers other options:
- Receive Money: Use apps like Zelle, CashApp, Venmo, or PayPal.
- Direct Deposit: Set up direct deposit with your employer.
- External Transfers: Send money to your Común account from an external bank or other financial institutions.
Additional Tips and Information
Fraud Prevention
Always keep your account number and PIN secure. Do not share this information with anyone to avoid unauthorized transactions.
Know Your Limits
Be aware of the deposit amount limits. For example, you can only deposit up to $250 per deposit and up to $1,000 per day. This helps you manage your funds and avoid any unexpected issues.
Use Común Features
The Común app provides a map to find the nearest ATMs and stores that accept barcodes for deposits. This feature helps you quickly locate convenient deposit points.
Stay up to date with the latest features and benefits offered by Común through the app, ensuring you get the most out of your online banking experience.
Cash Deposit Fees
Depositing cash at an AllPoint+ ATM has no fees, while other ATMs may charge a fee. Always check for possible fees before making a deposit.
Mobile Check Deposits
In addition to cash deposits, Común also supports mobile check deposits, adding more flexibility to the way you manage your money..
Conclusion
In short, depositing cash into a bank account is a practical decision driven by safety, convenience, possible earnings, financial management, and legal compliance. By understanding these reasons, people can make informed decisions about how to handle and manage their cash effectively, ensuring financial stability and growth.
Whether you use your physical card at an AllPoint+ ATM or a barcode in the app, depositing cash into your Común account is simple and convenient. Always make sure your card is activated, check nearby locations, and keep deposit limits in mind. With these steps, you will be able to manage your cash deposits effortlessly.
Do not worry, if there are no locations near you, you can also deposit with a barcode at many more locations! Visit Común for more details and get started with your deposits today.
By understanding the process and using the tools provided by Común, you will be able to handle your cash deposits effectively and ensure your funds are always accessible.
How do I find where to deposit cash near me?
In the app, go to "Cash" → "Deposit" to see the map with all available locations. Choose the closest one; if the location allows it, you can generate a code to deposit without a card.
Is there a limit on how much cash I can deposit?
Most stores have a $500 limit per transaction, though some allow higher amounts. If you deposit more than $300 at Walgreens or Walmart, you'll be asked for a U.S. government-issued ID.
What do I do if there's no location near me?
Check other locations on the app's map, or deposit at an AllPoint+ network ATM, which also accepts cash deposits.
Frequently asked questions
Do I need my physical card to deposit cash?
Not always — at many locations you can generate a barcode in the app and deposit using only your phone.
How much cash can I deposit per transaction?
Most stores have a $500 limit, though it can vary by location.
Do I need ID to deposit cash?
If you deposit more than $300 at stores like Walgreens or Walmart, you'll be asked for a U.S. government-issued ID.
Does depositing cash cost anything?
The cost can vary by store; check the details directly on the app's map before depositing.
Can I deposit cash at an ATM?
Yes, ATMs in the AllPoint+ network also accept cash deposits.
How do I know if a nearby location accepts Común deposits?
The map inside the "Cash" → "Deposit" section of the app shows you in real time which nearby locations accept deposits.
Checking account
Prepaid card vs. debit card: what's the difference?
8 min de lectura
A prepaid card is loaded with money in advance and generally is not linked to a traditional checking account. A debit card is linked to a checking account, and money is taken directly from the available balance in that account. A debit card is generally connected to additional banking features, such as account statements, direct deposit, and other account services.
The main difference is their connection to a bank account, as a debit card draws funds directly from a checking account, while a prepaid card requires you to load money onto it in advance. Neither prepaid cards nor debit cards typically help you build a credit score because they generally are not reported to the major credit bureaus.
What is a prepaid card?
A prepaid card is a payment card that must be loaded with funds before it can be used. Spending is limited to the amount loaded onto the card. They are commonly available through retail stores and financial service providers.
Prepaid cards are commonly used for everyday purchases, online payments, and sending or receiving limited funds. Prepaid cards can be reloadable, meaning you can add money again after spending the balance. Some also allow direct deposit, but the features available depend on the provider.
Because prepaid cards are generally not linked to a traditional checking account, they may not include features such as full account statements, overdraft services, or other banking features. Available services vary by provider.
What is a debit card?
A debit card is linked to a checking account. When a purchase is made, the money is taken directly from the account balance.
Debit cards are commonly used for daily spending, online purchases, ATM withdrawals, and bill payments. They are also commonly used for receiving income through direct deposit from employers or other payment sources.
Because the card is connected to an account, all transactions are recorded in account statements. These statements can be used to track spending, income deposits, and account activity over time.
A debit card generally reflects your available account balance as transactions are processed.
Prepaid card vs. debit card: main differences
Prepaid cards and debit cards can look similar in everyday use, but they operate in different ways behind the scenes. The comparison below breaks down how each one works across key features such as account access, fees, deposits, and financial tools. Común’s debit card is included to be used as an example of a debit card.
| Feature | Prepaid Card | Debit Card | Común Debit Card |
|---|---|---|---|
| Linked to checking account | No | Yes | Yes |
| FDIC insured | Varies by provider | Yes, if linked to an FDIC insured checking account | Yes, through Community Federal Savings Bank, Member FDIC |
| Direct deposit | Limited | Available, depending on the account | Yes, with early access options |
| Monthly fees | May apply, depending on the provider | Varies by provider | No monthly fee |
| Reload fees | May apply, depending on the provider | Not applicable | None |
| Account statements | Not available | Available through account | Available through account |
| Open without SSN | Many prepaid cards require SSNs | Varies by provider | Yes, eligible customers may apply using a passport or certain Latin American IDs |
| Overdraft protection | Generally no | Varies by account | Generally no |
This comparison shows how prepaid cards and debit cards differ in structure, cost, and financial features, especially when it comes to account access and long-term use. A debit card linked to a checking account can offer more functionality, including direct deposit and account statements. Eligible customers can open a Común checking account using a Passport or certain Latin American IDs.
What are the disadvantages of prepaid cards?
Prepaid cards can be useful for basic spending, but they can have limitations depending on how they are used.
One common limitation is cost structure. Many prepaid cards may charge fees for adding money, withdrawing cash, or maintaining the card. The types and amounts of fees vary by provider.
Some prepaid cards also have limits on deposits, withdrawals, or transfers.
Another limitation is access to financial features. Prepaid cards usually do not include all of the features available with a traditional checking account, such as detailed account statements, bill payment tools, or other banking services.
Can immigrants get a debit card without a Social Security Number?
Some financial institutions and service providers allow individuals to open accounts using alternative identification instead of a Social Security Number. Accepted identification varies by institution and may include a passport or other forms of government issued identification.
Verification is still required to confirm identity under U.S. financial rules, but the documents accepted can vary by provider.
Once the account is approved, a debit card is issued and linked to the checking account. It can then be used for purchases, withdrawals, and direct deposits.
In the United States, some financial service providers accept different forms of identifications for their verification process. For example, Común accepts passports and more than 100 Latin American IDs to open an account.
When does it make sense to use a prepaid card?
A prepaid card can be useful for basic spending, short-term use, or situations where a traditional checking account is not available.
It can also be used as a budgeting tool since spending is limited to the loaded balance.
Some people use prepaid cards as a first step in the U.S. financial system before moving toward debit accounts with more features.
How to switch from a prepaid card to a debit card
Switching from a prepaid card to a debit card usually involves opening a checking account and moving recurring payments or deposits to the new account.
Once the account is open, money can be added through direct deposit, transfers, or other supported methods depending on the provider.
Some users keep their prepaid card active during the transition period while updating payment information across services.
If you’re considering switching from a prepaid card, Común offers a checking account with a debit card that eligible customers can open using a passport or accepted Latin American IDs. The account doesn’t have any minimum balance requirements or monthly maintenance fees.
FAQ
Is a prepaid card the same as a debit card?
No, a prepaid card is loaded with money in advance and is not connected to a checking account. A debit card is linked to a checking account and uses the available balance in that account.
Can I use a prepaid card to build credit?
Prepaid cards generally do not build credit because purchases are not typically reported to the major credit bureaus.
What are the fees on a typical prepaid card?
Fees can include monthly maintenance charges, reload fees, and ATM withdrawal fees. The exact cost depends on the provider.
Can I get a debit card without a Social Security Number?
Some services allow account opening using alternative identification such as a passport or national IDs, depending on verification requirements.
What do I need to open a debit card account as an immigrant?
Requirements typically include a valid form of identification, personal information, and verification steps required by the financial provider.
Común is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank, Member FDIC. The Común Visa® Debit Card is issued by Community Federal Savings Bank, pursuant to a license from Visa U.S.A. Inc. and may be used everywhere Visa Cards are accepted.
No minimum balance requirements or monthly maintenance fees. ATM or transfer fees may apply. See app for fee details.
Direct deposit funds are typically available when we receive the payment file, up to two days before the scheduled payment date. This early availability is not guaranteed.
Funds in your account are FDIC insured up to applicable limits by ownership category through Community Federal Savings Bank (CFSB), Member FDIC, in the event CFSB fails.
Financial Education
Why was my bank transaction declined? Causes and solutions in 2026
8 min de lectura
Why was my bank transaction declined? Causes and solutions in 2026
Bank transactions are usually declined for one of these reasons: insufficient funds, daily transfer limits, suspected fraud, incorrect payment information, expired cards, or unusual account activity. In some cases, your bank may temporarily block a payment to protect your account, even if there's sufficient money available.
If your debit card, ACH transfer, ATM withdrawal, or online payment was rejected, the fastest solution is identifying whether the issue is caused by a transaction limit, a fraud alert, or a technical restriction on the account.
Top 10 reasons why your transaction was declined
1. Insufficient funds
This is still one of the most common causes. Even if you recently deposited money, funds may still be pending or unavailable. What you can do: check your available balance (not just current balance), review pending transactions.
2. Daily limit reached
Most accounts have daily transaction limits for debit cards, ATM withdrawals, and ACH transfers. What you can do: verify your limits in your bank's app or contact support.
3. Automatic fraud alert
Security systems may block transactions that seem unusual, such as purchases in a different location. What you can do: check if you received a confirmation SMS and respond to authorize the transaction.
4. Incorrect information
An incorrect card number, expiration date, CVV, or billing address can cause rejection. What you can do: verify the information entered and correct it.
5. Expired card
If your card has expired, transactions will be automatically rejected. What you can do: request a replacement card from your bank.
6. Blocked account
Your account may be temporarily blocked due to suspicious activity. What you can do: contact your bank directly.
7. Unsupported merchant
Some merchants or purchase types may be restricted by your bank. What you can do: use a different payment method or contact your bank.
8. Monthly ACH limit
ACH transfers have monthly limits in addition to daily ones. What you can do: verify your ACH limits and wait for the next cycle if you've reached them.
9. Inactive account
Accounts with no activity for an extended period may be flagged. What you can do: contact your bank to reactivate the account.
10. International transactions not enabled
Many debit cards don't come with international transactions enabled by default. What you can do: contact your bank to enable international payments.
Transaction types and their limits
| Transaction type | How it works | Common limitation |
|---|---|---|
| Debit card | Uses money from your checking account | Daily purchase or ATM limit |
| Credit card | Uses borrowed credit from the issuer | Credit limit or available credit |
| ACH transfer | Bank-to-bank electronic transfer | Daily or monthly ACH transfer cap |
Fraud alert vs. transaction limit: how to tell the difference
| Sign | Likely fraud alert | Likely transaction limit |
|---|---|---|
| Sudden block after travel | Yes | Sometimes |
| Transaction amount identical to your limit | No | Yes |
| Verification text message received | Yes | Rare |
| Small transactions also failing | Possibly | Less common |
| Decline happens at same amount repeatedly | Unlikely | Likely |
FAQ
Why was my card declined if I have money?
It could be a daily limit, a fraud alert, or a technical restriction. Check your bank's app or contact support for more details.
How do I check my transaction limits?
Most banking apps show transaction limits in the settings or transfers section. You can also contact your bank's support.
Común is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank, Member FDIC.
Checking account
What to Do if Your Alza Account Was Closed
8 min de lectura
If your Alza account was closed, you can open an account with Común using your passport, consular ID, or another Latin American ID — no Social Security Number required. The process takes about 3 minutes.
Similarities Between Alza and Común
Sending money to Latin America: Both Alza and Común offer remittance services, letting users send money to friends and family in Latin America quickly and efficiently.
Debit card and checking account: Users on both platforms get a debit card linked to a checking account; Común offers a Visa card, allowing worldwide transactions and access to funds.
Virtual Visa debit card: Común provides a checking account connected to a physical and virtual Visa debit card, emphasizing the importance of this offering for the financial stability and inclusion of Latino families.
Flexible application process: Both platforms let users apply for an account using various forms of ID, like an international passport, consular card, SSN, or ITIN.
ATM fee reimbursement: Alza users could withdraw cash from any ATM worldwide with full fee reimbursement. Común also supports ATM withdrawals, ensuring convenient access to cash.
Advantages of Switching to Común: Modern Banking Solutions
One of Común's standout features is its commitment to transparency and cost-effectiveness. Unlike traditional banks and even Alza, Común doesn't charge opening fees, monthly maintenance fees, and has no minimum balance requirements. This makes it an ideal option for those looking to avoid unnecessary banking fees and keep more of their hard-earned money. Here are a few more standout features of a Común account:
Financial inclusion: Común is dedicated to promoting financial inclusion by providing modern banking solutions tailored to the unique needs of Latino families. They address the challenges Latinos face in accessing traditional financial services and emphasize the importance of financial education. This commitment ensures the Latino community has access to an inclusive, supportive banking experience.
Broader ID acceptance:
- Común: Accepts any official government-issued ID, not just passports or consular cards. This makes it easier for a wider range of people to open an account.
- Alza: Limited to specific forms of ID, which could be restrictive for some users.
Simplified address verification:
- Común: Applicants can verify their home address using their phone's geolocation. This feature is particularly beneficial for immigrants who may not have traditional proof-of-address documents.
- Alza: Required physical proof of address, which could be a challenge for those in non-permanent housing or living with relatives.
Extensive cash deposit network:
- Común: Offers access to the largest cash deposit network in the U.S., with more than 90,000 locations, including popular retailers like Walgreens, Walmart, and Dollar General.
- Alza: Didn't specify as extensive a cash deposit network, limiting convenience for cash deposits.
24/7 customer service:
- Común: Provides customer service around the clock, ensuring help is available anytime, any day of the week.
- Alza: Customer service availability wasn't highlighted as a 24/7 feature.
With Común, you'll never feel alone managing your finances. They offer top-tier customer service available seven days a week via chat, email, or phone. That means you can get help whenever you need it, making your banking experience smooth and worry-free.
Open your bank account¹ in 3 minutes with your country's ID²
- No minimum balance fees
- Send money to your home country safely
- Get paid up to 2 days early³
- Send money to your home country safely
- And much more!
Making the Switch to Común: Financial Inclusion
Switching from Alza to Común is simple and hassle-free. As a trusted financial partner, Común understands Latino families' unique needs. You can apply for a Común account online in minutes using a variety of ID documents like a passport, consular card, or ITIN. Once your account is set up, you can easily transfer your funds to Común. The fastest way would be to withdraw cash from your Alza account and then deposit it at any cash deposit location Común offers using the barcode option in Común's cash deposit feature.
The transition from Alza to Común is designed to be smooth and straightforward, helping you achieve financial freedom. Here's how you can make the switch:
Open a Común account: Visit the Común website or download the Común app to start your application. Use any government-issued ID and your phone's geolocation to verify your address.
Transfer your funds: To transfer your funds to your Común account, we recommend first withdrawing cash from your Alza account. Then, you can go to any cash deposit location Común offers and deposit your cash using the barcode option. This option doesn't require your physical card, so you can deposit cash from your Alza account immediately after being approved for a Común account.
Another quick option that doesn't require your Común card is transferring your Alza funds directly from your Alza account to your Común account using your account number and routing number. You can find this information under Account Information in Settings.
Set up direct deposits: Update your direct deposit information with your employer or any other income source to ensure uninterrupted access to your funds.
Current Común Offerings
One of Común's founding principles is inclusivity. As a customer-focused digital bank, Común doesn't require a Social Security Number (SSN) to open an account. Unlike many traditional banks, this feature is particularly beneficial for immigrants and people who may not have access to traditional forms of ID. Común focuses on providing secure banking solutions for everyone, regardless of immigration status. Común also aims to be a financial hub for Latino immigrants, offering a comprehensive banking solution with expanded resources tailored to their needs. To welcome former Alza customers, Común has several incentives:
- Hassle-free application: Apply using any government-issued ID and easily verify your address through your smartphone.
- Enhanced customer support: Benefit from 24/7 customer service to assist with any questions or issues during your transition.
- Extensive cash deposit options: Enjoy the convenience of depositing cash at more than 90,000 locations nationwide.
Conclusion: Secure Your Financial Future With Común for Financial Stability
As Alza prepares to close its doors, Común offers a robust, user-friendly alternative that not only matches but goes beyond the services Alza provided. With no fees, an extensive cash deposit network, and unmatched customer support, Común is the ideal banking solution for former Alza customers. Make the switch today and experience the superior banking experience Común has to offer.
Make the switch today and experience the benefits of a banking platform that truly puts you first. Visit the Común website to learn more and start your new banking journey.
For more information and to start your application, visit Común's official website here: https://www.comun.app
Why do digital bank accounts like Alza get closed?
Reasons vary by institution — they can include inactivity, identity verification issues, or changes in the provider's policies. Check directly with Alza for your specific case.
What do I do if my account was closed and I need an alternative?
You can open an account with Común using a valid government-issued ID — passport, consular ID, or one of over 100 accepted Latin American IDs.
What do I need to open my new account with Común?
Just your valid government-issued ID. No Social Security Number or ITIN required, and the process is 100% online.
Frequently asked questions
Can I open a Común account if my previous account was closed by another provider?
Yes, as long as you have a valid government-issued ID, you can open your Común account without issue.
Do I need a Social Security Number to open my Común account?
No, we accept a passport, consular ID, or other Latin American IDs.
How long does it take to open my new account?
About 3 minutes, with instant approval in most cases.
Will I lose my financial history if I switch providers?
History within another platform doesn't transfer automatically; your new Común account starts fresh.
Does Común charge a fee to open the account?
No, there's no opening fee, monthly fee, or minimum balance required.
What should I do with the money in my old account?
Contact your previous provider directly to learn the process for withdrawing your funds before the account closes completely.
Financial Education
What is the CVV and what is it used for on your card?
8 min de lectura
What is the CVV on a card?
Nowadays, making purchases with a credit or debit card in physical stores and online is an essential activity for acquiring everyday goods.
Security in these operations is essential. For this, these payment methods use the CVV or CVC code, which means Card Verification Value or Card Verification Code respectively, and its purpose is to verify that the cardholder has the physical card and to protect online and phone purchases.
Below, we will explain in detail what the CVV is, where to find it, the types of security codes, and tips to keep your cards secure.
Where to find the CVV on your card?
If you are going to make purchases online or by phone, you will need to provide the security code of your debit or credit card to verify it belongs to you.
In most cases, the CVV is located on the back of the card and consists of 3 or 4 numbers.
Here is a quick guide to locating the verification code depending on the card type.
Card type
Where to find the CVV?
How many digits does it have?
Visa
Usually on the back, next to the magnetic stripe.
3
Mastercard
Usually on the back, next to the signature.
3
Discover
Usually on the back, to the right of the signature.
3
American Express
Usually on the front, next to the card number.
4
One way to strengthen security during electronic transactions is the use of a dynamic CVV, which is found in digital applications or cards and is valid only for a limited time to make a single purchase. This reduces the risk of misuse of your personal data if it is exposed.
What is the CVV for and why is it important?
The CVV number is a security lock that allows you to use your physical and digital cards with confidence that a third party cannot access your money.
These are the most important functions of this security code.
- Holder verification:
It is especially useful for protecting electronic operations by verifying that the cardholder is the one making the purchase.
- Security in online purchases
When making an online purchase, you must enter the card’s CVV to validate the transaction. This process is more secure when using a dynamic CVV because it reduces the risk in case of fraud.
- Fraud prevention
Unlike other data usually included on physical cards, such as the number and expiration date, the CVV is not stored in online store systems, so your data remains safe in case of potential identity theft.
The purpose of the CVV is to provide you with security and peace of mind when making online purchases.
CVV, CVC, and CVV2: how are they different?
You may notice different types of CVV since the name can vary depending on the card issuer.
These are the security codes most commonly used by financial institutions to protect users’ cards.
CVV
The CVV (Card Verification Value) is the security code created for Visa cards. It consists of 3 or 4 digits and is used to confirm that the person making the purchase actually has the card.
CVC
The CVC (Card Verification Code) is the version of the CVV used by Mastercard cards. It has the same function and a similar composition.
CVV2
The CVV2 (Card Verification Value 2) is a digital version of the CVV used to provide greater protection in online purchases. While the traditional CVV is used during payments at card terminals, the CVV2 is requested to confirm remote transactions.
4 tips to use your card safely
Some people avoid or minimize the use of physical or digital cards due to fear of having their personal data stolen and generating unauthorized charges. However, financial institutions and digital platforms currently offer the necessary security measures to protect your assets.
Thanks to the implementation of codes such as the CVV, the risk of experiencing a security incident is minimal and decreases even more when you have the right information to apply practical strategies like the following.
- Do not share your CVV or write it in visible places: avoid having this code leaked to third parties. Remember that it is the number used to verify online purchases and that no financial institution requests sensitive data over the phone, so make sure to use the CVV responsibly.
- Use only secure payment sites (https://): if you need to make an online purchase, make sure the site has the required security measures to process electronic payments.
- Activate notifications or dynamic CVV if your bank offers it: enable notifications in your banking application and try using the dynamic CVV when shopping online. This allows you to generate a new CVV for each purchase.
- Review your transactions regularly: check your statement and transaction history frequently. If you detect any irregular activity, report it to your bank immediately.
Bank cards are useful tools that require responsible and cautious use. Learning to use your card safely and confidently is also part of building financial stability.
Manage your money and make payments securely with Comun
This time we explained what the CVV or CVC is, why it is important, and gave you some tips to keep your checking accounts secure.
The security provided by the CVV is the same you need in all your financial operations, such as digital payments, cash deposits, and international money transfers. For this, you have Comun, the digital platform specially designed for immigrants living in the United States who want to manage their money safely and without complications, with clear and competitive fees.
Comun is the financial platform that truly understands your needs and offers fair, tailored solutions.
Open your Comun account and start managing your money in the United States with confidence. Send, receive, and monitor your expenses from the mobile app.
Frequently Asked Questions (FAQ)
If you still have questions, check the following section.
What happens if I give my CVV to someone else?
It is not advisable to give your CVV to someone else, as they could make purchases not authorized by you. Make sure to protect your banking information so only you have access to it.
Is the CVV the same as the card number?
No, the card number consists of 16 digits and identifies the checking account. The CVV consists of 3 or 4 digits and verifies that the holder is the card owner.
Can I make purchases without a CVV?
In physical stores, it is not strictly necessary, as the purchase is validated with the chip and PIN. For online purchases, it is essential to enter the CVV to authorize the transaction.
Financial Education
Practical guide to choosing the best savings account in the U.S. in 2025
8 min de lectura
Looking for an effective way to save money in the United States? For immigrants, opening a bank account is an essential step to adapt to the country’s pace of life and to access various everyday financial services, such as receiving payments, sending money, and saving.
For the latter, there are savings accounts which, unlike checking accounts, are a tool to safeguard money in a secure place and grow it through an interest rate or Annual Percentage Yield (“APY”).
More than a list of savings account options in the United States, below we present a practical, comprehensive guide so you can learn to compare key factors such as which banks pay higher interest in the USA, fees, and FDIC backing for greater security.
Best savings accounts in the United States in 2025
One of the qualities of the U.S. financial system is that it includes a large number of institutions offering savings accounts with different advantages and features.
Below, we list some of the high-yield savings accounts in 2025. Please check each bank for the most up-to-date information.
| Bank | Marcus by Goldman Sachs | SoFi Bank | Ally Bank | Capital One | Citi Bank |
|---|---|---|---|---|---|
| Estimated APY (September 2025) | 3.65% | Up to 4.50% under certain requirements | Up to 3.90% | Up to 3.50% | Up to 4.30% on High-Yield options |
| Minimum opening deposit | Not required | Not required | Not required | Not required | Not required |
| Main fees / charges | Clear and competitive fees | Some conditions are required to maintain the high APY | Limit of 10 withdrawals or early withdrawal penalty for the High-Yield CD | Meeting certain conditions is required to maintain the high APY | May require a minimum balance to avoid fees |
| FDIC insurance | FDIC member | FDIC member | FDIC member | FDIC member | FDIC member |
| Key benefit | Money transfers up to $100,000 USD to/from other banks | Use vaults to set money aside and enable round-ups | Access Allpoint or MoneyPass ATMs and up to $10 reimbursement for other ATMs | Digital access and branch access | Broad branch network |
| Suitable profile | People seeking simplicity and a good APY | Those looking to combine checking and savings | People seeking an easy-to-use digital platform | People seeking a hybrid experience with online and in-person service | People seeking a bank with global presence |
Key factors for choosing a savings account in the United States
Before choosing a savings account, it is very important to compare alternatives at traditional banks, such as Bank of America and Wells Fargo, and digital banks, such as Ally Bank and Capital One.
Annual Percentage Yield (APY)
APY (Annual Percentage Yield) indicates the annual return on your money. This percentage varies depending on the type of financial institution and the type of account.
For example, at traditional banks the APY may be under 1%, while on digital high-yield savings account options, you can obtain a return above 4%, under certain conditions.
Minimum deposits and balance requirements
Although many digital and hybrid banks do not require initial deposits, traditional banks often do. For example, U.S. Bank requires a minimum deposit of $25 USD to open an account.
Fees and hidden charges
Banks also frequently charge monthly maintenance fees, which can affect the return on your savings.
For example, Wells Fargo requires a minimum balance of $300 USD per month to avoid a $5 USD monthly fee.
Security: FDIC insurance
It is essential to verify that the bank you choose is a member of the FDIC (Federal Deposit Insurance Corporation), because this institution insures deposits up to $250,000 USD per depositor, per insured bank, for each account ownership category in the event of bank failure.
Access and ease of use
It is also very important to assess how easy it is to access the services of the institutions you consider. For example, whether they have mobile banking, access to ATM networks, the ability to make transfers and withdraw money, as well as the account-opening requirements requested for immigrants.
Types of savings accounts in the United States
In the United States there are several types of bank accounts to cover profiles with different expectations and lifestyles. It is essential to understand the particularities of each one so you can choose the most suitable option according to your needs.
These are the main bank account types in the U.S.
Traditional savings accounts
These are savings accounts offered by both traditional and digital banks to keep money with moderate interest rates.
Advantages
- It is possible to make direct deposits and withdraw money.
- Most do not require a minimum opening deposit.
Disadvantages
- Lower interest rates than high-yield options.
- Because of this, your money may lose value against inflation.
- Limited additional benefits compared with other options.
High-yield savings accounts (High-Yield Savings Account)
These are savings accounts distinguished by offering a considerably higher APY than traditional options.
Advantages
- Greater growth of your money, especially in the long term.
- Unlike Certificates of Deposit, these accounts allow you to withdraw money without penalties in most cases.
Disadvantages
- Sometimes it is necessary to maintain a minimum balance to access the highest APY.
- Rates vary over time.
- Not all institutions have physical branches.
Money Market Accounts
These are deposit accounts that combine some features of checking and savings accounts.
Advantages
- They provide greater flexibility and allow the use of checks and debit cards.
- They offer notable interest rates, especially for accounts with high balances.
Disadvantages
- They may require higher minimum balances to open an account or avoid monthly fees.
- Variable interest rates.
- Limits on withdrawals and money transfers at some banks.
Certificates of Deposit (CDs)
These are fixed-term investment instruments starting at 3 months, with a fixed interest rate.
Advantages
- Higher interest rates than regular savings accounts.
- Guaranteed return if you do not withdraw the money.
Disadvantages
- If you need to withdraw your money early, you will have to pay a penalty.
- Generally, you will need to invest a large amount of money to reach a good rate of return.
Tips to get the most out of your savings account
If you really want to see a positive impact on your personal finances, opening a bank account is not enough. You need to learn to use it strategically to see real results.
Follow these simple tips and maximize the potential of your savings account.
- Automate minimum monthly deposits to build discipline.
- Set clear savings goals to build an emergency fund.
- Do not use your savings account for daily expenses; try to have a separate account that allows you to carry out daily transactions easily.
- Look for banks that offer a debit card or integration with international transfers so you can send money to your country of origin without complications.
Manage and grow your money in the U.S. with Común
Throughout this article you learned what a savings account is, the key aspects for comparing and choosing your preferred option—APY, minimum deposit, fees, and FDIC protection—as well as tips to make the most of them and promote financial education.
Común is the financial option designed for immigrants who want to handle their money with clarity and confidence.
Discover why Común is an option designed for your needs:
- Open your checking account with qualifying official identification from your country of origin.
- Get a debit card for daily expenses.
- Send remittances easily to Mexico and other LATAM countries.
- Save and organize your money easily.
Open your account with Común today and start organizing your money safely and simply. Take the next step toward more stable finances in the United States!
Frequently Asked Questions (FAQ)
What is the minimum deposit to open a savings account?
It depends on the bank. Some do not require a minimum deposit, while traditional institutions usually request around $25 USD.
Do all savings accounts have FDIC insurance?
All accounts at FDIC-insured banks have insurance. Exceptions are fintechs that act as intermediaries.
Can a person without a Social Security Number open a savings account in the U.S.?
Many banks accept an ITIN instead of an SSN or, in some cases, a passport or official foreign ID. Please check with the corresponding bank for their identification requirements for opening an account.
Community
What You Need to Open an Account at Comun¹ 5
8 min de lectura
Unmatched Ease of Opening an Account
Opening a checking account with Comun is simple and hassle-free, addressing the barriers to financial exclusion typically faced by the immigrant community. Accepting over 100 forms of identification², including social security numbers from Latin American countries, Comun ensures that immigrants have access to essential banking services. The application process is quick, taking less than 5 minutes, and is free of additional or hidden fees, minimum balance requirements or monthly commissions. This inclusiveness is central to Comun's mission of fostering financial stability and growth.
Mobile Deposit Options
ComunComun offers a convenient mobile deposit feature that allows users to deposit cash at more than 88,000 locations in the United States, including major retailers such as Walgreens, Dollar General and Walmart. This extensive network ensures that users can easily find a deposit location near them, making the process of adding money to their accounts simple and hassle-free.
Traditional Banking: Although many traditional banks offer mobile deposit options, they often restrict these to check deposits through a mobile app. Cash deposits typically require a visit to an ATM or bank branch, which can be less convenient and more time-consuming than Comun's extensive cash deposit network.
Utility in Today's World: In today's fast-paced environment, the flexibility to deposit cash in a wide range of accessible locations is invaluable, especially for individuals who may not have easy access to traditional banking services or who work non-traditional hours when banks are closed.
International Remittances
ComunComun excels in facilitating international remittances⁴, allowing users to send money abroad quickly and with lower fees compared to many traditional banks and remittance services. The process is enhanced with real-time notifications, keeping the sender informed from the moment the money is sent until it is received.
Traditional Banking: Traditional banks generally offer international transfer services, but these can be expensive and slow, with transfers sometimes taking several days to complete. In addition, the fees associated with traditional bank remittances can be significantly higher.
Usefulness in Today's World: In a globalized economy, the ability to send money across borders quickly and affordably is crucial. Many families rely on remittances for financial support, and businesses need efficient ways to handle international transactions. Comun's streamlined and cost-effective service effectively meets these modern demands.
Advance Salary Access
Comun: Comun offers the ability to connect wages to the application and receive payment up to two days in advance³. This feature incurs no additional fees, providing significant relief during financial emergencies or when planning ahead.
Traditional Banking: Some traditional banks have begun to offer similar features, but they are often tied to specific types of accounts or require a minimum balance. The accessibility and ease of use of early access to Comun's salary is not always matched in traditional environments.
Usefulness in Today's World: With the rise of gig economy jobs and irregular pay schedules, having early access to wages can provide a buffer against financial instability. This feature is particularly valuable for those living paycheck to paycheck, offering a cushion that can help avoid overdraft fees and late payments.
Unlike traditional banking institutions, Comun's innovative features are designed to meet the needs of today's diverse and mobile population, particularly benefiting the immigrant community in the U.S. By providing services that offer greater convenience, lower costs and greater accessibility, Comun not only addresses common challenges faced by its users, but also empowers them toward greater financial freedom and stability. As we move toward a more interconnected and fast-paced world, the importance of responsive and inclusive financial services continues to grow, something Comun is uniquely positioned to offer.
Robust Security and Customer Support
Security and customer support are paramount at Comun. With FDIC-insured accounts and Visa protection on virtual Visa debit card transactions, Comun customers can manage their funds with confidence. Innovative security features such as biometric logins and instant transaction notifications keep your money safe. In addition, Comun offers 24/7 customer support in English and Spanish, ensuring that help is always available in your preferred language.
Commitment to Zero Fees and Upward Mobility
Comun stands out not only for offering zero fees for account opening, monthly maintenance or minimum balances, but also for its commitment to helping its users move up the financial ladder. Comun acts as a financial partner, supporting financial transactions without the burden of excessive fees. This commitment aligns with the goal of enabling upward mobility for immigrants, who contribute significantly to the U.S. economy.
Customized Features and Benefits
Comun goes beyond traditional financial services by offering features designed to meet the unique needs of the immigrant community. Users can send money abroad with low or no fees, deposit cash at more than 88,000 locations nationwide, including free ATM withdrawals, and connect their accounts to popular payment apps such as Zelle, CashApp and Venmo. Comun's platform also allows customers to receive their paychecks up to two days early through direct deposit, further enhancing their financial flexibility and stability.
Conclusion
Comun is not just a financial services provider, but a platform dedicated to transforming the banking experience for immigrants in the U.S. With its user-focused design, commitment to financial freedom and robust features, Comun is destined to become a vital tool for achieving financial stability and growth for its users. Whether you are looking to manage your daily finances or send money to loved ones abroad quickly and securely, Comun offers a reliable, inclusive and efficient banking solution.
Foundational Moment: Did you know?
Founded by entrepreneurs Mark Selcow and Andres Santos in New York, Comun was built to empower families and enable upward mobility, particularly for the immigrant family. The company has garnered significant investment from prominent firms such as Costanoa Ventures, FJ Labs and South Park Commons, underscoring the tremendous opportunity to serve the financial needs of immigrant families and improve the lives of every individual.
Immigration
What is needed to obtain a Green Card in the United States?
8 min de lectura
Surely during your stay in the United States you have heard about the well-known Green Card or permanent resident card.
It is a document issued by the U.S. government that allows immigrants to reside and work legally and permanently.
For immigrants, obtaining it is of utmost importance, as it also opens the door to several benefits, such as legal protection, the right to purchase property, and the ability to apply for lawful permanent residence for family members.
Thousands of migrants in the United States often ask the big question: “How can I live legally in the United States?” We know how important it is for you to achieve better living conditions to support your family and loved ones. Therefore, below you’ll find a guide with practical steps, eligibility categories, and the documents needed to obtain a Green Card and change your life in the United States.
Eligibility categories for the Green Card
There are several paths to obtain a green card. To know which one to take, you need to be clear about both your immigration status and the eligibility category that applies to your profile.
Family-based Green Card
The first category refers to permanent residence granted through immediate family members who already have legal status in the United States.
It is divided as follows:
- Immediate relatives of U.S. citizens: spouses and unmarried children under 21.
You must wait for approval of Form I-130 and then apply for residence; there is no annual cap.
- Family preference category: unmarried children over 21 of citizens; spouses and children of permanent residents; married children of citizens; and siblings of citizens.
You must file Form I-485. For this, you must wait until your priority date becomes current on the Visa Bulletin. Otherwise, you can only file the I-130.
Employment-based Green Card
- EB-1 visa: individuals with extraordinary ability, such as distinguished professors or researchers.
- EB-2 visa: accomplished professionals with an advanced degree and exceptional ability.
- EB-3 visa: skilled workers, professionals, and “other workers.”
- EB-4 visa: special categories such as religious workers, U.S. government employees, members of the Armed Forces, among others.
- EB-5 visa: for investors who allocate substantial funds to businesses that create at least 10 jobs in the country.
Process to obtain a work-based visa
- The employer files the PERM Labor Certification, demonstrating that there are no qualified or available U.S. workers for the position. To do this, they must submit Form ETA-9089 to the Department of Labor.
- Once employment authorization is obtained, the employer must file Form I-140 with USCIS, along with the approved PERM certification.
- The employee must apply for adjustment of status via Form I-485 (if in the United States) or do consular processing at a U.S. embassy.
- For the EB-2 visa, applicants may choose the National Interest Waiver (NIW), which eliminates the need for PERM.
Remember that to work legally in the United States you must obtain an SSN. Before obtaining residence, migrants often use an ITIN to file their tax returns.
Green Card for special immigrants
- VAWA visa: victims of abuse by a U.S. citizen or permanent resident.
- SIJ visa: minors who have been abused or abandoned by their parents.
- In both cases, applicants must file Form I-360.
Green Card through refugee or asylee status
- People admitted through an asylum claim or refugee status, as well as their immediate family members.
- In both cases, applicants must be physically present in the United States for at least 1 year and then file Form I-485.
Other categories
In addition, there are other less common categories:
- Diversity Visa (Green Card Lottery): an annual lottery of up to 50,000 slots. Selectees receive a consular interview, though it does not guarantee a visa.
- Cuban Adjustment Act: a special adjustment program for Cuban nationals.
Each category has different eligibility requirements and processing times, so it is very important to consult U.S. government guidance and, if needed, seek the support of an immigration attorney.
Steps to apply for a Green Card
Once you know, in broad strokes, the requirements to obtain a Green Card, you need to be clear about the application process you must follow.
Determine eligibility
Before starting any process, review the categories above and determine which best fits your profile—family, employment, special immigrants, etc.
We recommend reviewing the Visa Bulletin to verify the documents required for your category and ensure you have them.
File the initial petition
Once you are clear on the category that applies to you, you must file the form indicated for that category, along with the required supporting documents, for example:
- Valid passport (required for any category).
- Evidence of the family relationship, such as birth or marriage certificates.
- Job offer letter.
Adjustment of status or consular processing
After your corresponding form is approved, you must apply for adjustment of status or consular processing and pay the fee required by the Department of State.
- If you are in the United States, file Form I-485 along with evidence of eligibility.
- If you are in another country, you must submit the DS-260 at a U.S. consulate. This is the immigrant visa application for permanent residence.
Interview and biometrics
In the next step, you must attend an adjustment-of-status appointment, at which USCIS will take your fingerprints, biometrics, photo, and signature.
You must also attend an interview to answer questions related to your eligibility category.
Receiving the Green Card
Finally, your Green Card will be mailed to your address. Make sure to check that all details are correct and keep it in a safe place.
After some time, you may apply for citizenship if you meet the necessary requirements.
Maintaining and renewing the Green Card
Once you have your green card in hand, you must keep track of renewal periods to avoid issues after the expiration date.
Renewal and replacement
- A regular Green Card is valid for 10 years.
- To replace your Green Card, you must file Form I-90 at least 6 months before the expiration date.
- The same form is also used in case of damage or loss.
Removal of conditions
- Applies to conditional residents with a 2-year Green Card, generally based on a recent marriage to a U.S. citizen.
- File Form I-751 for marriage-based cases or the corresponding form for your category.
- You must submit the documentation required by USCIS, as well as attend an additional interview.
Important rules
- If you change your address, be sure to report it to USCIS promptly.
- If for any reason you need to spend more than 6 consecutive months outside the United States, be sure to obtain a reentry permit (Advance Parole or Reentry Permit). Otherwise, you could risk losing your residence.
- Refrain from actions considered abandonment of residence, such as surrendering the card or voting in foreign countries.
- Keep an eye on your Green Card’s validity and renew it when appropriate.
Organize your financial life in the U.S. with Común
As you can see, the process of obtaining a Green Card is long and exhausting. Therefore, it is essential to understand the different categories, steps, forms, and the key points to maintain your permanent residence.
Another relevant point for improving your stay in the United States is having partners who understand your needs.
We present Común, the financial platform that addresses day-to-day needs through an intuitive mobile app, where you can easily open an account with qualifying official identification from your country of origin.
It also offers remittance services to several countries, helping your family receive more for less.
- Open a secure account with clear and competitive fees.
- Receive deposits and send remittances home.
- Get a debit card for daily expenses and financial control.
- Ability to save and plan your finances as you settle in the United States.
Open your account with Común today and get financial services tailored to you.
Frequently Asked Questions (FAQ)
If you still have questions, consult our FAQs.
Can I travel outside the U.S. while my application is in process?
You need to obtain Advance Parole (Form I-131), since leaving the country could cancel your application.
When can I apply for citizenship after obtaining a Green Card?
You must be a permanent resident for at least 5 years, or 3 if based on marriage, and have lived continuously in the United States and fulfilled tax obligations.
How long does the Green Card process take?
It depends on the category and whether you apply inside or outside the country. In general, the wait time is approximately 1 to 3 years.
How much does it cost to apply for a Green Card?
The cost varies by category. Check USCIS’s fee calculator to get a clear figure.
What is the difference between the I-485 and the DS-260?
The I-485 is the adjustment-of-status application to permanent resident filed within the United States, whereas the DS-260 is the immigrant visa application filed from another country.
What happens if your Green Card is denied?
You can appeal the decision via Form I-290B or refile the application.
Checking account
What Is a Bank Account and What Are the Benefits of Having One?
8 min de lectura
A bank account is a financial account a customer holds at a bank. A bank account lets customers deposit and withdraw money, as well as write checks. That's why it's also called a checking account.
The advantages of having a bank account include:
- Easy access to your money — 24/7 banking access through the bank's website or app
- No need to carry cash
- The ability to earn interest on your deposits
- Building a credit history, which can matter when you want to apply for a loan in the future
How Do You Open a Bank Account?
Opening a bank account is relatively easy. You'll need to provide some personal information, like your name, date of birth, and address. You'll also be asked for ID — usually a Social Security Number (SSN) is enough. More modern banks, like Común, let you replace your SSN with a passport or consular ID. You may also be asked for documentation proving your address.
The Different Types of Bank Accounts Available
There are different bank accounts to choose from. The most common type is the checking account, which lets you deposit and withdraw money and write checks. A checking account is a great option if you want easy access to your money without carrying cash, since your account's debit card lets you pay at any business.
Another common type of bank account is the savings account. Savings accounts let you save money and earn interest on your deposits. It's a great option if you want to build up your savings over time.
There are also several specialized bank accounts, like accounts for students, seniors, and businesses. Be sure to research the different bank accounts available and choose the one that best fits your needs.
How to Manage a Checking Account Online
Many bank customers choose to manage their bank account online. You can do this through the bank's website or app. Managing your bank account online lets you access it 24 hours a day, 7 days a week.
Some things you can do online include:
- View your account balance and transaction history
- Transfer money between savings and checking accounts
- Pay bills
- Pay your credit card
- Deposit checks
- Set up banking alerts for specific events, like a low balance or a large deposit
What Does It Cost to Open a Bank Account in the United States?
Some accounts, like the one Común offers, come with no monthly fee and no minimum balance requirement. However, many banks do charge fees. These include some of the most popular banks in the United States: Bank of America, JPMorgan Chase, Citigroup, and Wells Fargo. Here are some of the fees they charge:
- Monthly service fee
- Minimum balance requirement
- Overdraft fee
- Check-cashing fee
Certain banks also limit Spanish-language support in their digital interfaces or customer service centers. Be sure to research the fees charged and the language support offered before opening an account with any bank.
FDIC Backing
The Federal Deposit Insurance Corporation (FDIC) is a government agency that insures consumer deposits at banks in its network. It's important to choose a bank with this backing, since you'll have up to $250,000 of your funds insured by the U.S. government if your bank fails.
The Benefits of Común
At Común, you'll find a checking account with no monthly fee and no minimum balance, in Spanish (from the mobile app to customer support), with the flexibility to apply using your passport, no matter your nationality. Opening an account is very easy, and you'll have 24/7 access, along with the ability to pay bills or deposit checks. Común is FDIC-insured, so your funds are protected up to $250,000 USD.
As with any financial service, be sure to research the different options available and choose the one that best fits your needs.
Living in the United States
Cashier’s Checks in the U.S.: Costs, Impact on Latinos, and Free Alternatives
8 min de lectura
Why is it so expensive to cash checks in the United States?
Without a bank account, people must turn to check-cashing stores that charge between 1% and 3% of the check amount. For a $1,000 check, that means $10-30 lost on each cash-out. Banks may also charge fees for depositing checks from other banks.
Why do Latinos disproportionately bear these costs?
Latino communities have less access to banking services because of barriers such as SSN requirements, language, and unfamiliarity with the system. Without a bank account, they are more likely to use check-cashing stores located in low-income areas that charge high fees.
Solutions for cashing checks at no cost
The best solution is to open a bank account. Común is a Spanish-language digital bank that allows you to open an account without an SSN using a passport or consular ID card. Once opened, you can deposit checks for free from the app using mobile deposit. There are also nonprofit organizations such as UnidosUS that offer free financial services to Latino communities.
Frequently asked questions about cashing checks in the U.S.
How much does it cost to cash a check in the U.S. without a bank account?
Check cashing stores typically charge between 1% and 3% of the check amount, with a minimum of $3-5. For a $1,000 payroll check, that means losing between $10 and $30 on each cash-out. Walmart Money Center charges lower fees ($4 for checks up to $1,000), but the cost is still higher than having a bank account.
Can I cash a check for free in the U.S.?
Yes, with a bank account. If you deposit the check at your own bank, there is no charge. With Común you can deposit checks by photographing them from the app, completely free. Some banks also allow you to deposit checks from other banks at no additional cost using mobile deposit.
Why do Latino immigrants pay more to cash checks?
The main reason is less access to bank accounts. Barriers include SSN requirements, language, unfamiliarity with the system, and fear of formal procedures. Without a bank account, they turn to check-cashing services that charge high fees. Platforms like Común remove these barriers by accepting Latin American IDs without an SSN.
What do I need to deposit a check in Común?
You only need the Común app and the physical check. Open the app, select “Deposit check,” take a photo of the front and back of the check (with your signature on the back), and the money is generally credited in 1-2 business days. There are no additional charges for the mobile deposit service.
What happens if someone pays me with a personal check from someone without a bank account?
Personal checks from people without sufficient funds or without an active account bounce (bounced check). If you deposit that check, the bank may temporarily hold the funds and then debit you the amount plus an NSF fee ($25-35). To receive payments more safely, prefer Zelle, Venmo, or direct transfers instead of personal checks from people you do not know well.
Is it better to receive payroll by check or by direct deposit?
Direct deposit is better in virtually all cases: the money arrives automatically on payday (or earlier with Común), there is no risk of the check being lost or stolen, there are no cashing fees, and you can access the funds immediately. With Común you can set up direct deposit from the app in minutes using your routing number and account number.







Thousands of immigrants are already achieving more with their money. You can too.
Comun is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank; Member FDIC. The Comun Visa® Debit Card is issued by Community Federal Savings Bank, pursuant to a license from Visa U.S.A Inc. and may be used everywhere Visa Cards are accepted.
Comun is a fintech company and not a bank or licensed money transmitter.
* Results may vary. For a complete list of eligible IDs and application requirements, follow this link.
^ No minimums, no maintenance fees. ATM or transfer fees may apply. See app for fee details.
‡ Direct deposit funds are typically available when we receive the payment file, up to two days before the scheduled payment date. This early availability is not guaranteed.
** A service provided by Service UniTeller, Inc. Service UniTeller, Inc. is licensed in all states that require a license. Remittance fees start at $2.99 but may vary. Please check the app for more details. Comun Inc. may earn revenue from the conversion of foreign currencies.
† Funds in your account are FDIC insured up to $250,000 by ownership category through Community Federal Savings Bank (CFSB), Member FDIC, in the event CFSB fails.


