
Financial Education
How to fill out a check in the United States in 5 simple steps (+ Example)
Learn how to fill out a check correctly in the United States step by step. What each field means and common mistakes to avoid.
8 min read

30 Jul 2025
Have you ever filled out a check? Although most transactions today are digital, knowing how to fill out a check is essential—especially if you are just beginning your financial life.
According to recent data, one-third of Americans paid by check in 2024, demonstrating that checks still play an important role in the U.S. economy.
You might consider checks an outdated payment method; the reality is that they are useful in specific situations. For that reason, we will explain what a check is, the different types of checks, and how to complete them properly.
What Is a Check and What Is It Used For?
Despite the digital era, checks remain a relevant traditional payment method due to their formality and traceability. They are used for rent payments, purchases, and service payments.
Additionally, checks are a common payment method among the immigrant community, who often use them while adapting to the U.S. banking system.
But what exactly is a check and what are its characteristics? It is a physical document issued by an individual or business (the drawer) to order a bank to pay a specified amount to a third party. For the payment to be processed, the drawer must have sufficient funds in their checking account.
In general, a check contains the following information:
- Name of the drawer, whether an individual or a business
- Name of the payee
- Financial institution where the money will be drawn
- Amount to be paid, both in numbers and in words
- Signatures of the drawer
What Are the Different Types of Checks?
There are different types of checks in the United States. In this case, we will focus on the personal check, although you may choose the option that best suits your needs.
Personal Check
A personal check is a payment order issued by an individual to another individual using the funds in a checking account.
What Is a Personal Check Used For?
The most common uses for personal checks include:
- Rent and utility payments
- Purchase of everyday goods
- Legal agreements requiring documentary support
Certified Check
A certified check serves the same purpose as a personal check but is reviewed and guaranteed by the issuing bank, which verifies that the drawer has sufficient funds and holds them until the check is cashed.
A certified check provides certainty of available funds, making it a more secure method for making and receiving payments.
Cashier’s Check
Unlike a personal check, a cashier’s check is issued directly by the bank, offering greater security for the payee, as the bank is responsible for issuing and safeguarding the funds.
To obtain a cashier’s check, the drawer must visit a bank branch and pay the amount to be transferred. The bank then issues the check in the name of the payee, guaranteeing that it can be cashed using the institution’s own funds and not a personal account.
It is commonly used for high-value purchases such as homes and vehicles.
Money Order
While not strictly a check, it is a traditional payment method with similar functionality.
A money order is a financial instrument that allows funds to be sent via traditional mail using a certified check, which must be purchased and paid for by the drawer at an authorized location.
It allows secure money transfers without requiring a bank account.
How to Fill Out a Check in the U.S.
Before issuing this type of payment order, you must know how to do it properly. Below is an example of how to fill out a check easily, starting from step one:
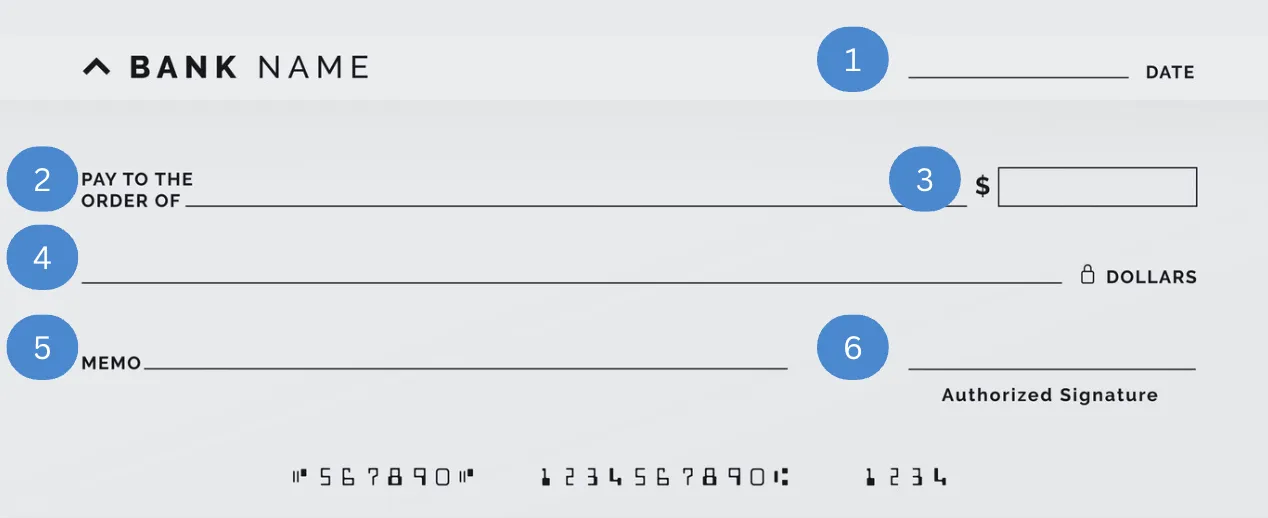
1. Write the Date
Remember that in the United States, the date format is mm/dd/yyyy.
2. Payee’s Name
Write the full name of the person to whom you are issuing the check, exactly as it appears on their official identification.
3. Amount in Numbers
Write the numerical amount clearly.
4. Amount in Words
Write the amount in words, including cents.
5. Add a Memo
You may include a note specifying the reason for the payment.
6. Sign the Check
Sign the check legibly in the space designated for the drawer.
7. Review the Information
Ensure that all information is accurate to avoid issues for the payee when cashing the check.
It is essential to complete checks legibly, without strike-throughs or corrections, as these may invalidate the document.
How to Correctly Write Numbers in Words on a Check
Writing amounts in words may be confusing when dealing with U.S. dollars. The following points should be kept in mind:
- Dollar amounts must be written in full words
- Cents must be written as fractions
- Avoid using dollar symbols or similar notations
- If there is leftover space at the end of the line, draw a line to prevent fraud
- For example, $1,000.75 is written as: One thousand and 75/100 dollars
Cash Checks and Manage Your Money Easily with Comun
As you can see, knowing how to fill out a check is useful for sending and receiving money in the United States. It is a reliable and accessible alternative if you do not have a banking account.
However, issuing and cashing a check can also require significant time and effort. That’s why you can skip the trip to the bank, avoid wasting time or money on gas, and cash your check directly from your phone using Comun—no lines, no questions, no complications.
Discover Comun, the only platform designed to serve the needs of immigrant communities in the United States, with support available in Spanish.
Why Choose Comun?
- Open your account with an official ID from your country
- Access a mobile app specifically designed for immigrants in the U.S.
- Make payments, receive your salary, and manage your finances
- Send money to your loved ones in LATAM for just a $2.99 transfer fee
Frequently Asked Questions
Still have questions about how to fill out a personal check? See our FAQ section.
What if I Make a Mistake Filling Out a Check?
If there are strike-throughs or inconsistencies in the amounts, the check must be voided and a new one used.
How Do I Void a Check?
Write the word VOID in large letters on the front of the check.
What Information Appears on the Back of a Check?
The back of the check contains the endorsement, meaning the payee’s signature for cashing the check.
About Común
Común aims to support the Latino community in the United States. It offers a debit account that can be opened with more than 100 valid Latin American IDs and an app available in Spanish.
Visit Común's website or download the app for free to learn more about the full offer and applicable terms.
Olivia Rhye
Community Partner

Immigration
What is needed to obtain a Green Card in the United States?
8 min de lectura
Surely during your stay in the United States you have heard about the well-known Green Card or permanent resident card.
It is a document issued by the U.S. government that allows immigrants to reside and work legally and permanently.
For immigrants, obtaining it is of utmost importance, as it also opens the door to several benefits, such as legal protection, the right to purchase property, and the ability to apply for lawful permanent residence for family members.
Thousands of migrants in the United States often ask the big question: “How can I live legally in the United States?” We know how important it is for you to achieve better living conditions to support your family and loved ones. Therefore, below you’ll find a guide with practical steps, eligibility categories, and the documents needed to obtain a Green Card and change your life in the United States.
Eligibility categories for the Green Card
There are several paths to obtain a green card. To know which one to take, you need to be clear about both your immigration status and the eligibility category that applies to your profile.
Family-based Green Card
The first category refers to permanent residence granted through immediate family members who already have legal status in the United States.
It is divided as follows:
- Immediate relatives of U.S. citizens: spouses and unmarried children under 21.
You must wait for approval of Form I-130 and then apply for residence; there is no annual cap.
- Family preference category: unmarried children over 21 of citizens; spouses and children of permanent residents; married children of citizens; and siblings of citizens.
You must file Form I-485. For this, you must wait until your priority date becomes current on the Visa Bulletin. Otherwise, you can only file the I-130.
Employment-based Green Card
- EB-1 visa: individuals with extraordinary ability, such as distinguished professors or researchers.
- EB-2 visa: accomplished professionals with an advanced degree and exceptional ability.
- EB-3 visa: skilled workers, professionals, and “other workers.”
- EB-4 visa: special categories such as religious workers, U.S. government employees, members of the Armed Forces, among others.
- EB-5 visa: for investors who allocate substantial funds to businesses that create at least 10 jobs in the country.
Process to obtain a work-based visa
- The employer files the PERM Labor Certification, demonstrating that there are no qualified or available U.S. workers for the position. To do this, they must submit Form ETA-9089 to the Department of Labor.
- Once employment authorization is obtained, the employer must file Form I-140 with USCIS, along with the approved PERM certification.
- The employee must apply for adjustment of status via Form I-485 (if in the United States) or do consular processing at a U.S. embassy.
- For the EB-2 visa, applicants may choose the National Interest Waiver (NIW), which eliminates the need for PERM.
Remember that to work legally in the United States you must obtain an SSN. Before obtaining residence, migrants often use an ITIN to file their tax returns.
Green Card for special immigrants
- VAWA visa: victims of abuse by a U.S. citizen or permanent resident.
- SIJ visa: minors who have been abused or abandoned by their parents.
- In both cases, applicants must file Form I-360.
Green Card through refugee or asylee status
- People admitted through an asylum claim or refugee status, as well as their immediate family members.
- In both cases, applicants must be physically present in the United States for at least 1 year and then file Form I-485.
Other categories
In addition, there are other less common categories:
- Diversity Visa (Green Card Lottery): an annual lottery of up to 50,000 slots. Selectees receive a consular interview, though it does not guarantee a visa.
- Cuban Adjustment Act: a special adjustment program for Cuban nationals.
Each category has different eligibility requirements and processing times, so it is very important to consult U.S. government guidance and, if needed, seek the support of an immigration attorney.
Steps to apply for a Green Card
Once you know, in broad strokes, the requirements to obtain a Green Card, you need to be clear about the application process you must follow.
Determine eligibility
Before starting any process, review the categories above and determine which best fits your profile—family, employment, special immigrants, etc.
We recommend reviewing the Visa Bulletin to verify the documents required for your category and ensure you have them.
File the initial petition
Once you are clear on the category that applies to you, you must file the form indicated for that category, along with the required supporting documents, for example:
- Valid passport (required for any category).
- Evidence of the family relationship, such as birth or marriage certificates.
- Job offer letter.
Adjustment of status or consular processing
After your corresponding form is approved, you must apply for adjustment of status or consular processing and pay the fee required by the Department of State.
- If you are in the United States, file Form I-485 along with evidence of eligibility.
- If you are in another country, you must submit the DS-260 at a U.S. consulate. This is the immigrant visa application for permanent residence.
Interview and biometrics
In the next step, you must attend an adjustment-of-status appointment, at which USCIS will take your fingerprints, biometrics, photo, and signature.
You must also attend an interview to answer questions related to your eligibility category.
Receiving the Green Card
Finally, your Green Card will be mailed to your address. Make sure to check that all details are correct and keep it in a safe place.
After some time, you may apply for citizenship if you meet the necessary requirements.
Maintaining and renewing the Green Card
Once you have your green card in hand, you must keep track of renewal periods to avoid issues after the expiration date.
Renewal and replacement
- A regular Green Card is valid for 10 years.
- To replace your Green Card, you must file Form I-90 at least 6 months before the expiration date.
- The same form is also used in case of damage or loss.
Removal of conditions
- Applies to conditional residents with a 2-year Green Card, generally based on a recent marriage to a U.S. citizen.
- File Form I-751 for marriage-based cases or the corresponding form for your category.
- You must submit the documentation required by USCIS, as well as attend an additional interview.
Important rules
- If you change your address, be sure to report it to USCIS promptly.
- If for any reason you need to spend more than 6 consecutive months outside the United States, be sure to obtain a reentry permit (Advance Parole or Reentry Permit). Otherwise, you could risk losing your residence.
- Refrain from actions considered abandonment of residence, such as surrendering the card or voting in foreign countries.
- Keep an eye on your Green Card’s validity and renew it when appropriate.
Organize your financial life in the U.S. with Común
As you can see, the process of obtaining a Green Card is long and exhausting. Therefore, it is essential to understand the different categories, steps, forms, and the key points to maintain your permanent residence.
Another relevant point for improving your stay in the United States is having partners who understand your needs.
We present Común, the financial platform that addresses day-to-day needs through an intuitive mobile app, where you can easily open an account with qualifying official identification from your country of origin.
It also offers remittance services to several countries, helping your family receive more for less.
- Open a secure account with clear and competitive fees.
- Receive deposits and send remittances home.
- Get a debit card for daily expenses and financial control.
- Ability to save and plan your finances as you settle in the United States.
Open your account with Común today and get financial services tailored to you.
Frequently Asked Questions (FAQ)
If you still have questions, consult our FAQs.
Can I travel outside the U.S. while my application is in process?
You need to obtain Advance Parole (Form I-131), since leaving the country could cancel your application.
When can I apply for citizenship after obtaining a Green Card?
You must be a permanent resident for at least 5 years, or 3 if based on marriage, and have lived continuously in the United States and fulfilled tax obligations.
How long does the Green Card process take?
It depends on the category and whether you apply inside or outside the country. In general, the wait time is approximately 1 to 3 years.
How much does it cost to apply for a Green Card?
The cost varies by category. Check USCIS’s fee calculator to get a clear figure.
What is the difference between the I-485 and the DS-260?
The I-485 is the adjustment-of-status application to permanent resident filed within the United States, whereas the DS-260 is the immigrant visa application filed from another country.
What happens if your Green Card is denied?
You can appeal the decision via Form I-290B or refile the application.

Instant payments
What is Venmo and how does it work? The Ultimate Guide for Immigrants to the United States
8 min de lectura
Have you heard of Venmo? It is a digital payment application that has gained popularity in the United States in recent years. According to recent data, in 2024 the mobile application reached 68.3 million active users, representing an 8.8% increase compared to 2023.
The importance this mobile application has acquired cannot be denied, which is why knowing what Venmo is in the United States can be very useful to send and receive money from family and friends quickly and securely.
As a foreign national living in the U.S., you must ensure that you choose a financial platform that meets your needs for sending money to your home country and making payments with ease.
In this guide, we clarify all your potential questions about how to use Venmo in other languages like Spanish, what it is for, the requirements to open an account, the benefits this mobile app offers, and also its limitations.
What Is Venmo and How Does It Work?
Venmo is a highly popular P2P (peer-to-peer) payment mobile application in the U.S. Its primary purpose is to facilitate the instant transfer of money between friends and family, in addition to allowing users to link bank accounts and cards.
Venmo’s business model is based on charging fees for services such as credit card transactions, instant transfers of money to bank accounts, and transactions using its physical card.
Some of the most common reasons immigrants use Venmo include:
- Paying monthly rent
- Receiving wages from occasional jobs
- Paying or receiving money from friends and family
- Lending or repaying money to acquaintances
Key Features of Venmo: What Can You Do With It in the U.S.?
To fully understand what Venmo is in the United States, it is important to explore the functionalities this P2P payment service offers its users to simplify their lives:
- Instant sending and receiving of money between Venmo users
These are the mobile app’s most important features, as it allows for instant transfers without charging a fee between Venmo users.
It also enables adding notes or emojis to identify each transaction and the option to use the mobile app’s balance or a linked bank account. - Use of Venmo Debit Card (Mastercard) for purchases
Venmo also offers a physical debit card for making purchases at brick-and-mortar establishments. It is valid at any merchant that accepts Mastercard within the United States.
Additionally, it includes an extra benefit: each purchase with the debit card accumulates cash back for greater savings. - Direct deposit for wages and benefits
You can use your Venmo account to receive your salary or other types of transfers. All you need is your personal QR code. - Bank transfers to bank accounts
Venmo offers two types of bank transfers: standard transfers, which are free and take one to three business days, and instant transfers, which incur a fee of approximately 1.75% and are completed within minutes. - Payments to businesses and merchants that accept Venmo
Another advantage of this service is the “Pay with Venmo” feature, which allows payments at physical or online businesses that accept Venmo.
This streamlines transactions and enables you to use the balance deposited in the application directly. - Social features: comments, “likes,” and bill-splitting
Lastly, one feature that makes Venmo more appealing is the ability to add comments, likes, and emojis.
This allows you to request payments from friends and family, add reminders, and split expenses among multiple users. - Business profiles for companies
Venmo allows small businesses and independent workers to create a business profile to receive payments directly into their account via username or QR code.
What Do I Need to Have Venmo? The Reality of Its Availability
Now that you know the benefits of this mobile application in detail, you probably want to learn the requirements to start using it.
Before learning how to pay with Venmo, remember that it only works in the United States.
These are the requirements to use Venmo:
- Have an Android or iOS phone
As it is a mobile application, you must have a compatible Android or iOS smartphone and download the mobile app from the corresponding store. - Register with a personal phone number
To register in the mobile app, you need a U.S. phone number and must reside in the country, as Venmo is only available there. You may also register with an email address. - Link your U.S. bank account
Linking a bank account isn't required to create your Venmo account; you can receive money and pay with your balance or a card. However, most features require a linked bank account. - Link a debit or credit card
Another option to access all Venmo’s features is linking a credit or debit card instead of a bank account. This allows you to use the card’s balance for transactions directly from the mobile app. - Verify your account
Account verification is required to access all Venmo features, to confirm users’ identities. Verified users can send up to $60,000 per week, but only if their SSN or ITIN has been confirmed. Non-verified users can send up to $299.99 per week.
To verify your account, Venmo will request the following:
- Full legal name
- Mailing address in the United States
- Date of birth
- SSN (Social Security Number) or ITIN
How to Transfer Money from Venmo to My Bank Account?
To transfer money from Venmo to your bank account, once it is linked and verified, follow these steps:
1. Log into your account through the mobile app and go to the “Me” tab.
2. Press the “Transfer” or “Add” button.
3. Enter or edit the amount you want to transfer to your bank account.
4. Select the transfer method: “Instant” or “up to 3 biz days,” noting any applicable fees.
5. Confirm the transfer details and complete the process.
If you want more options for depositing money into another person’s account, do not miss these recommendations.
Limitations of Venmo for Immigrants: Why Is It Not a Complete Solution?
The need for immigrants to have an integrated solution allowing access to digital payments, transfers, and other benefits increases daily. Therefore, while Venmo is a popular option for sending and receiving money in the U.S., it may present limitations for immigrants working in the country.
One limiting factor for immigrant communities is the language barrier in customer support. Because it is a service designed for U.S. residents, it is not optimized for people who speak a different language, such as Spanish. In addition, you should have a U.S. bank account.
Your best option may be to entrust your financial assets to a service offered in your language.
Comun: An Excellent Alternative to Venmo for the Immigrant Community in the U.S.
We present Comun, the solution for immigrants seeking to improve the way they send and receive money to family and friends.
Why Is Comun a Great Option for Immigrant Communities in the United States?
- Comun allows you to open an account with the official identification from your country.
- It is also a platform available in Spanish without complicated terms.
- Unlike Venmo, Comun enables you to send remittances to LATAM for an affordable fee starting at $2.99, subject to applicable limits.
- Access a mobile application to perform your transactions from the palm of your hand.
If you think accessing quality financial services in the U.S. is impossible for immigrants, open your Comun account today and forget about complications.
Disclosures:
“Comun is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank; Member FDIC. The Comun Visa® Debit Card is issued by Community Federal Savings Bank, pursuant to a license from Visa U.S.A Inc. and may be used everywhere Visa Cards are accepted.”
“Funds in your account are FDIC insured up to $250,000 by ownership category through Community Federal Savings Bank (CFSB), Member FDIC, in the event CFSB fails.”
“A service provided by Service UniTeller, Inc. Service UniTeller, Inc. is licensed in all states that require a license.”
“Remittance fees start at $2.99 but may vary. Please check the app for more details.”
“Comun Inc. may earn revenue from the conversion of foreign currencies.”
“Direct deposit funds are typically available when we receive the payment file, up to two days before the scheduled payment date. This early availability is not guaranteed.”
Living in the United States
Everything You Need to Know About Bank Accounts in the
8 min de lectura
Bank Accounts
Having a bank account is essential for managing your financial life efficiently and offers numerous practical benefits. One of the main advantages is safe money storage. Unlike keeping cash at home, which can be vulnerable to theft, loss, and damage, money kept in a bank account is safe and protected. Additionally, bank accounts provide great convenience for everyday transactions. You can easily pay bills, receive direct deposits, withdraw cash, and make purchases with a debit card linked to your account. Modern banking also lets you manage your finances from virtually anywhere through online and mobile banking platforms.
Types of Bank Accounts: Checking and Savings
In the world of personal finance, understanding the different types of bank accounts is crucial.
- Checking Accounts: Checking accounts, often called personal checking accounts, are designed for everyday transactions like depositing money and debit card purchases. They frequently come with the option of direct deposits and online bill pay. Understanding the differences between checking and savings accounts is essential, especially when considering banking promotions and bonuses that often feature specific offers for opening new checking and savings accounts, including direct deposit requirements and minimum deposits to qualify for cash bonuses.
- Savings Accounts: Savings accounts, including specialized forms like a Barclays savings account, are meant for storing money over a longer period, often with the goal of building an emergency fund. These accounts may offer a higher interest rate and sometimes require a minimum balance. Combining checking and savings accounts can provide a comprehensive banking solution, offering both the flexibility of everyday transactions and the benefit of earning interest on long-term savings, which is particularly advantageous when banks offer promotions and bonuses for these accounts.
- Money Market and CD (Certificate of Deposit) Accounts: Generally offer higher annual percentage yields than regular savings accounts, locking in funds for a specified period to achieve better returns.
Understanding these options helps align banking services with your financial goals, whether you're considering opening a business checking account or a joint savings account at the same bank or credit union.
Opening Your First New Bank Account
To open an account, particularly a new online bank account, start by choosing the right financial institution — it could be an online-only bank, a traditional bank, or a credit union, depending on your financial needs and preferences. Consider factors like accessibility, customer service, fee structures, and the availability of online and mobile banking features when selecting where to open your account.
The process generally involves making an initial deposit, which can vary but is often a minimum opening deposit. Meeting the minimum deposit is crucial to qualify for account bonuses. Some institutions may require only a few dollars, while others may ask for a larger amount, especially for premium or specialized accounts. During the account-opening phase, you'll need to provide personal information like a Social Security Number or an Individual Taxpayer Identification Number, and a government-issued ID, like a passport or driver's license. This information helps the bank ensure compliance with regulatory requirements, including those related to money laundering.
Many banks offer bank account bonuses or a checking account bonus to new checking account customers, which can be an attractive incentive. Opening a personal checking account in America comes with specific bonuses and rewards, including cash bonuses for meeting certain requirements like a qualifying direct deposit. To qualify for these bonuses, customers often need to meet criteria like a minimum deposit within a certain timeframe and maintaining that balance for a specific period. For example, some financial institutions offer cash bonuses for setting up a qualifying direct deposit. This incentive often requires you to receive a regular payment, like a salary or a government benefit, directly into your new account within a certain period of opening the account. Be sure to understand the terms and conditions associated with these bonuses, like minimum balance requirements and the duration of direct deposits.
Additionally, ask about any potential fees associated with the account, like monthly maintenance fees, ATM usage fees, and overdraft charges. Sometimes, banks offer fee waivers under certain conditions, like maintaining a minimum balance or even by enrolling in direct deposit. It's also worth asking about the bank's overdraft policies. Some banks offer overdraft protection programs, which can keep you from incurring fees if you accidentally overdraw your account. This service can be a lifesaver for new account holders unfamiliar with managing their balance, but it typically comes at an additional cost.
Finally, consider the bank's customer service and support options. Reliable customer support can be invaluable, especially if you run into issues with your account or need guidance on using banking services. By carefully considering these aspects, you can ensure your first banking experience is positive and financially beneficial. Remember, the right bank for someone else might not be the right bank for you, so choose based on your specific circumstances and financial needs.
Común Is a Great Choice for Your Banking Needs in the USA
If you're looking for a reliable, modern banking solution in the United States, Común is the perfect choice for you. Común is a digital bank designed for everyone, especially the immigrant community, offering a hassle-free banking experience, no hidden charges, and Spanish-language tools that make managing your finances easier. With Común, you can open an account in minutes from your phone, get your complimentary debit card, and start enjoying benefits like no-cost transfers, direct deposits, and access to more than 55,000 fee-free ATMs nationwide. Plus, Común cares about your security, implementing advanced measures to protect your money and your data. Don't wait any longer — join the Común community for a banking experience that understands and supports your unique needs.
Open your checking account¹ in 3 minutes with your country's ID²
More Information About Bank Accounts in the United States
We explain your account number
Best practices for managing your account
Effective Account Management
Effectively managing bank accounts goes beyond simply monitoring balances — it involves a comprehensive approach to financial administration. This means understanding and reducing account fees, which can include monthly maintenance, ATM usage, and overdraft charges. One way to minimize these fees is by meeting minimum balance requirements or enrolling in direct deposit, since many banks offer fee waivers under these conditions.
Using online and mobile banking tools is essential for efficient financial management. These platforms allow real-time transaction monitoring, immediate fund transfers, and quick access to statements and banking documents, which can help with budgeting and tax preparation. Setting up automatic bill payments is another crucial feature, ensuring all payments are made on time, avoiding late fees and service interruptions.
For those managing multiple accounts, like a business checking account and a personal checking account, linking these accounts can simplify money management. It allows easier transfers between accounts and a consolidated view of finances, which is particularly beneficial for small business owners who need to keep personal and business expenses separate. Additionally, having multiple bank accounts can offer significant benefits, like separating funds for different purposes — such as everyday expenses, savings, and investments — and meeting individual or joint financial needs, including for international travel or business purposes.
Additionally, mobile banking has revolutionized access to financial services, letting users complete a variety of banking tasks from their devices, like checking balances, depositing checks remotely, and withdrawing cash from ATMs without a physical card. This convenience, however, needs to be balanced with diligent security practices to protect financial data.
Security and Protection
Account security is critical for protecting financial assets from potential threats like fraud and identity theft. Banks, whether online or traditional, implement robust security measures, including encryption, Secure Sockets Layer (SSL) certificates, and continuous monitoring for suspicious activity. However, responsibility also falls on the account holder to improve their personal security.
Enabling two-factor authentication adds an extra layer of security, significantly reducing the risk of unauthorized access. Using strong, complex passwords and changing them regularly are fundamental practices for securing online banking portals. Account holders should also be alert to phishing scams — fraudulent attempts to obtain sensitive information. Recognizing suspicious emails, links, or phone calls requesting personal banking information is crucial.
Regularly monitoring account activity is another proactive security measure. Many banks offer customizable alerts that immediately notify the account holder of unusual or large transactions, allowing quick action against unauthorized access. It's also advisable to frequently review transaction history to identify any irregularities that might indicate fraudulent activity. Additionally, understanding the latest banking security technologies and using all available tools provided by financial institutions can significantly improve the security of banking operations. These tools include biometric verifications, like fingerprint and facial recognition, which offer a higher level of security than traditional passwords.
By incorporating these advanced management and security practices, people can significantly improve both the efficiency and security of their banking experience, ensuring their financial assets are managed wisely and protected against potential threats.
Conclusion
Navigating the complexities of bank accounts — from choosing the right type to managing and securing them — can significantly impact your financial well-being. Understanding the various account types available, from personal and business checking accounts to savings and CD accounts, lets you make informed decisions that align with your financial goals. Opening your first account is a crucial step that lays the groundwork for building a robust financial future. By selecting the right financial institution, understanding fee structures, and taking advantage of incentives like account bonuses, you position yourself to maximize the benefits of banking.
Effective account management and vigilant security measures are essential to getting the most out of your banking experience. Using online and mobile banking tools not only provides convenience, but also lets you keep close oversight of your financial activities, ensuring your money works for you as efficiently as possible. Additionally, the importance of security can't be overstated — protecting your financial information from fraud and theft is paramount in today's digital age.
Ultimately, carefully managing and protecting your bank accounts is crucial to maintaining financial health and reaching your monetary goals. By adopting the practices outlined in this guide, you can confidently navigate the banking landscape, making informed decisions that strengthen your personal and business finances. Whether you're opening your first account or optimizing existing ones, remember that every step you take is a building block toward greater financial security and freedom.
Community
Using Your Digital Card From Day One: A Step-by-Step Guide
8 min de lectura
¿Por Qué Configurar una Tarjeta Digital?
Tu tarjeta digital está disponible para su uso tan pronto como financies tu cuenta, ofreciendo varias ventajas:
- Acceso Instantáneo: No hay período de espera para una tarjeta física.
- Conveniencia: Realiza compras en línea fácilmente en comerciantes populares como Amazon, Walmart y más.
- Flexibilidad: Usa la tarjeta digital para varias transacciones, incluyendo depósitos en efectivo con un código de barras en tu aplicación.
Configuración de Tu Tarjeta Digital
Sigue estos pasos para configurar y comenzar a usar tu tarjeta digital con Común¹:
1. Financia Tu Cuenta
Asegúrate de que tu cuenta bancaria esté financiada. Este paso es crucial, ya que tu tarjeta digital solo estará disponible después de que la cuenta tenga fondos.
2. Accede a la Tarjeta Digital
Abre tu aplicación bancaria Común y navega hasta la página principal.Busca el botón “Administrar tarjetas” en la esquina superior izquierda de la página principal.
3. Ver Detalles de la Tarjeta
Haz clic en “Administrar tarjetas” para acceder a las opciones de gestión de tarjetas.Para ver los detalles de tu tarjeta, haz clic en “Ver información de la tarjeta”.
4. Usando Tu Tarjeta Digital para Compras en Línea
Con los detalles de tu tarjeta visibles, ahora puedes usar tu tarjeta de débito digital para hacer compras en línea. Simplemente ingresa la información de la tarjeta en el proceso de pago en cualquier sitio web que acepte pagos con tarjeta de crédito o débito, incluidos grandes minoristas como Amazon y Walmart.
5. Depositar Efectivo
No necesitas esperar tu tarjeta física para depositar efectivo. Usa el código de barras en tu aplicación para hacer depósitos en efectivo en lugares compatibles.
Beneficios e Inconvenientes de Usar una Tarjeta Digital
Seguridad: Las tarjetas digitales ofrecen una capa adicional de seguridad para transacciones en línea. Se pueden bloquear o reemplazar fácilmente si se ven comprometidas, reduciendo el riesgo de robo de identidad y transacciones no autorizadas.
Uso Inmediato: Comienza a comprar en línea o deposita efectivo sin esperar tu tarjeta física.
Control: Gestiona los detalles de tu tarjeta directamente desde tu aplicación Común, lo que facilita el seguimiento de gastos y la actualización de información según sea necesario.
Conveniencia: No es necesario llevar una tarjeta física, lo que reduce el riesgo de perderla.
Inconvenientes Potenciales de Usar una Tarjeta Digital
Aceptación Limitada: Algunos comerciantes pueden no aceptar tarjetas digitales, especialmente para transacciones en tienda donde se requiere una tarjeta física.
Dependencia de la Tecnología: El acceso a tu tarjeta digital depende de tener tu dispositivo móvil y conexión a internet. Si pierdes tu teléfono, te lo roban o se queda sin batería, podría ser difícil acceder a los detalles de tu tarjeta.
Transición a Tarjeta Física: Una vez que llegue tu tarjeta física, necesitarás activarla y actualizar cualquier método de pago guardado, lo que puede ser un paso adicional.
Riesgos de Seguridad Potenciales: Aunque las tarjetas digitales son generalmente seguras, no son inmunes a ataques de phishing u otras estafas en línea. Es esencial estar alerta y practicar buenos hábitos de seguridad.
Why Set Up a Digital Card?
Your digital card is available to use as soon as you fund your account, offering several advantages:
- Instant Access: No waiting period for a physical card.
- Convenience: Easily make online purchases at popular merchants like Amazon, Walmart, and more.
- Flexibility: Use the digital card for various transactions, including cash deposits using a barcode in your app.
Setting Up Your Digital Card
Follow these steps to set up and start using your digital card with Común¹:
1. Fund Your Account
Make sure your bank account is funded. This step is crucial, since your digital card will only be available once the account has funds.
2. Access the Digital Card
Open your Común banking app and navigate to the home page. Look for the "Manage cards" button in the top left corner of the home page.
3. View Card Details
Click "Manage cards" to access card management options. To view your card details, click "View card information."
4. Using Your Digital Card for Online Purchases
With your card details visible, you can now use your digital debit card to make online purchases. Simply enter your card information at checkout on any website that accepts credit or debit card payments, including major retailers like Amazon and Walmart.
5. Depositing Cash
You don't need to wait for your physical card to deposit cash. Use the barcode in your app to make cash deposits at supported locations.
Benefits and Drawbacks of Using a Digital Card
Security: Digital cards offer an extra layer of security for online transactions. They can be easily locked or replaced if compromised, reducing the risk of identity theft and unauthorized transactions.
Immediate Use: Start shopping online or depositing cash without waiting for your physical card.
Control: Manage your card details directly from your Común app, making it easy to track spending and update information as needed.
Convenience: No need to carry a physical card, reducing the risk of losing it.
Potential Drawbacks of Using a Digital Card
Limited Acceptance: Some merchants may not accept digital cards, especially for in-store transactions where a physical card is required.
Technology Dependence: Access to your digital card depends on having your mobile device and an internet connection. If you lose your phone, it's stolen, or the battery dies, it could be difficult to access your card details.
Transition to a Physical Card: Once your physical card arrives, you'll need to activate it and update any saved payment methods, which can be an extra step.
Potential Security Risks: While digital cards are generally secure, they aren't immune to phishing attacks or other online scams. It's essential to stay alert and practice good security habits.
How to Avoid the Drawbacks of a Digital Card
While digital cards offer many benefits, being aware of potential drawbacks and mitigating them ensures a smooth, secure experience. Here are some tips on how to avoid common issues associated with digital cards:
Confirm Merchant Acceptance:
Before making a purchase, especially in-store, confirm that the merchant accepts digital cards or mobile wallet payments like Google Pay or Apple Pay. For online purchases, most major retailers will accept digital cards without issue.
Prepare for Technology Dependence:
Always have a backup plan. Keep a secondary payment method, like a physical card or another digital wallet, available in case your mobile device isn't accessible. Charge your phone regularly and consider carrying a portable charger.
Smooth Transition to a Physical Card:
When your physical card arrives, activate it right away and update your payment information across all your regular services. This includes updating saved card details on online shopping sites and digital wallets to ensure continuity.
Improve Security Measures:
Protect your digital card against phishing attacks by only entering card details on trusted websites. Use a secure browser extension or app to generate unique digital card numbers for different transactions, adding an extra layer of security.
Enable notifications for all transactions to monitor for any unauthorized activity. This helps you quickly detect and respond to any suspicious transactions.
Stay Informed and Proactive:
Regularly review your account settings and transaction history in the Común app to stay on top of your finances.
Set spending limits on your digital card to manage your budget and avoid overspending. Keeping an eye on your available balance ensures you don't face declined transactions due to insufficient funds.
Use Customer Support:
If you run into any issues or have questions about using your digital card, don't hesitate to contact Común customer service. They can provide additional assistance and help you resolve any issues quickly.
Get your digital card with Común right now!
Open your bank account¹ in 3 minutes with your country's ID²
Integrating Digital Cards With Digital Wallets
For added convenience, you can integrate your digital card with digital wallets like Google Pay and Apple Pay. This lets you use your digital card for both online and in-store purchases without needing the physical card. Simply add your digital card details to your preferred digital wallet app and start spending safely and conveniently.
Managing Your Digital Card
Using your digital card effectively means staying on top of your account settings and spending limits. Here are some tips for managing your digital card:
- Monitor Transactions: Regularly review your transaction details in your Común app to make sure all charges are correct.
- Set Spending Limits: Control your spending by setting limits on your digital card, helping you avoid overspending and better manage your budget.
- Update Payment Information: Keep your payment information up to date, especially if you receive a new digital card or need to change your billing address.
Conclusion
Setting up and using your digital card from day one is a simple process that offers immediate access and convenience. While there are numerous benefits, including greater security and instant availability, it's important to be aware of potential drawbacks. By understanding both the pros and cons, you can make informed decisions about how best to use your digital card.
Take advantage of the ease of modern banking by activating your digital card today and enjoy the benefits of instant access to your funds. Whether you're making online purchases or depositing cash, your digital card provides a flexible, secure way to manage your finances. Visit Común to learn more about setting up your digital card and explore other innovative banking solutions we offer.
Checking account
The Pros and Cons of Using Checks at Banks in the U.S. | Común
8 min de lectura
Cashing a Check at Your Own Bank
When it comes to cashing a check, one of the simplest options is visiting your own bank or financial institution. Here's a step-by-step process for depositing or cashing a check:
- Endorse the Check: Flip the check over and sign your name on the back in the area designated for endorsement. Make sure your signature matches what's on file with the bank.
- Visit Your Bank: Head to the local branch of the bank where you have an account. Bring a valid form of ID, like a driver's license or passport.
- Approach a Teller: Depending on your preference and the bank's options, you can present the check to a teller for processing or use an ATM equipped with check deposit functionality to get your money.
- Provide Necessary Information: If you're dealing with a teller, you may need to provide additional account information, like your account number, the issuing bank, and the check amount. For ATM deposits, follow the on-screen prompts to enter the relevant details.
- Confirm Deposit or Receive Cash: After processing, you'll receive confirmation of the deposit into your account or the cash in hand if you chose to cash the check.
'Cashing' a Check Electronically
Beyond traditional in-person methods, many banks offer electronic options for depositing checks. This convenient approach lets you deposit checks without visiting physical locations or even cash checks without ID. Here's how it works:
- Mobile Deposit: Most banks provide a mobile app that lets you deposit checks using your smartphone or tablet. Simply endorse the check, take photos of the front and back, and submit them through the app.
- Online Banking: Some banks offer online banking portals where you can scan and upload images of checks for deposit. This method generally follows steps similar to mobile deposit and is accessible through a web browser.
- Electronic Funds Transfer: In some cases, you may have the option to electronically transfer a check's funds directly to your account without needing physical processing.
Pros and Cons of Checking Accounts
Checking accounts serve as the hub for many financial transactions, offering both benefits and drawbacks. Understanding these pros and cons is crucial to effectively managing your resources.
Advantages of Having a Checking Account
- Convenience: Checking accounts provide a convenient way to access and manage your funds for everyday expenses, like paying bills and making purchases with a debit card.
- Writing Checks: With a checking account, you can issue checks to people or businesses, offering a secure, traceable payment method.
- Direct Deposit: Many employers offer direct deposit, letting your paychecks be automatically deposited into your checking account, providing quick access to money.
- Online Banking: Most banks offer online banking services for checking accounts, letting you monitor account activity, transfer money, and pay bills from the comfort of home or on the go.
- Overdraft Protection: Some checking accounts come with overdraft protection options, which can help prevent declined transactions and fees in the event of insufficient funds.
Disadvantages or Limitations of Checking Accounts
- Fees: Some checking and money market accounts may have monthly maintenance fees, overdraft fees, limited withdrawals, or ATM fees, which can reduce your balance if not carefully managed.
- Minimum Balance Requirements: Certain checking accounts require you to maintain a minimum balance to avoid fees, which can be a challenge for those living paycheck to paycheck.
- Limited Interest: While some checking accounts offer interest on balances, rates are typically lower compared to savings accounts, resulting in minimal earnings on your deposits.
- Fraud Risk: Issuing checks or using a debit card linked to your checking account exposes you to the risk of fraud or unauthorized transactions, requiring vigilance and prompt reporting of any suspicious activity.
By carefully weighing the advantages and disadvantages of checking accounts and considering key factors when selecting the right account, you can effectively manage your finances and get the most out of your banking experience.
Where to Cash a Check
When it comes to cashing a check, you have several options available, ranging from a traditional bank to a retail store. However, not all locations are equal, and it's essential to weigh the pros and cons of each option before making a decision.
- Banks: Your bank is often the simplest option for cashing a check. You can visit a branch or use an ATM equipped with check deposit functionality. Many banks and credit unions also offer mobile deposit options, letting you deposit checks using your smartphone.
- Retail Stores: Some retail stores, like supermarkets, convenience stores, and big-box retailers, offer check-cashing services for a fee. This can be a convenient option if you don't have a bank account or need access to cash outside of banking hours.
- Check-Cashing Stores: Dedicated check-cashing stores specialize in cashing checks for a fee. While these establishments provide quick access to cash, their fees can be higher compared to other options, reducing the amount you receive.
- Prepaid Debit Card: Certain prepaid debit cards let you load checks onto the card electronically, providing instant access to funds. This can be a convenient option if you regularly use prepaid cards for financial transactions.
Where to Avoid Cashing a Check Due to Potential Fees or Limitations
- Payday Lenders: Avoid cashing checks at payday loan establishments, since they often charge exorbitant fees and may engage in predatory lending practices.
- Pawn Shops: While some pawn shops offer check-cashing services, their fees can be high, and they may require collateral or impose additional charges and higher costs to cover transactions.
- High-Fee Retailers: Be careful when cashing checks at retailers that charge high fees for the service, since these fees can significantly reduce the amount of cash you receive.
When deciding where to cash a check, consider factors like convenience, fees, and access to money. Choose a reputable establishment and service with transparent fee structures to make sure you get the most value from your check-cashing experience.
Comparing Checking and Savings Accounts
Understanding the differences between checking and savings accounts is crucial for effective financial management. Here's a concise comparison:
Interest Rates and Benefits of Savings Accounts
- Interest Rates: A savings account generally offers higher interest rates compared to a checking account, making it ideal for growing your money over time.
- Benefits:
- Goal-Oriented Saving: Savings accounts are great for setting aside funds for specific goals.
- Safety Net: They provide a financial cushion for unexpected expenses.
- Access to Funds: While there may be a limit on withdrawals, savings accounts offer relatively easy access to your money.
Considerations for Having Both Accounts at the Same Bank
- Convenience: Managing both a savings and checking account at the same bank offers ease in transferring money, viewing balances, and accessing statement cycles and bundled services.
- Relationship Benefits: Some banks or credit unions offer perks for customers with multiple accounts, like higher interest rates or waived fees.
- Simplified Experience: Consolidating a savings and checking account simplifies banking tasks like bill payments and money transfers.
- Diversification: However, having accounts at different banks provides diversification and can mitigate risks associated with a single financial institution.
Ultimately, the decision to have a savings and checking account at the same bank or spread across multiple financial institutions depends on your preferences, financial goals, and banking needs.
Loading a Check Onto a Prepaid Card
Loading a check onto a prepaid card is a convenient alternative to traditional banking methods, offering flexibility and accessibility for people who may not have or prefer not to use traditional accounts. Let's briefly break down the process and considerations associated with this method.
Prepaid Cards and Their Suitability
- Prepaid Cards: Reloadable payment cards not linked to traditional bank accounts.
- Loading Checks: Prepaid card providers offer options to load checks electronically through mobile apps or online portals.
- Suitability: Ideal for those without a bank account or who prefer alternative financial services.
Pros and Cons of Using Prepaid Cards
Pros:
- Accessibility and convenience for loading checks.
- Control over spending and security features.
Cons:
- Monthly fees for various transactions.
- Limited features compared to traditional bank accounts.
- Reload limits and lack of FDIC insurance.
Consider the convenience and accessibility of prepaid cards for check transactions, keeping in mind the associated fees and limitations.
You Can Open a Checking Account With Común Right Now!
Open your checking account¹ in 3 minutes with your country's ID²
Conclusion
Navigating the check banking landscape today requires a balanced understanding of the advantages and disadvantages inherent to this payment method. While checks offer flexibility and accessibility, they also come with potential fees and security risks. By weighing the pros and cons outlined in this article and exploring alternative banking options, people can make informed decisions to optimize their financial and cash management strategies.
Instant payments
What is Cash App and how does it work?
8 min de lectura
What is Cash App and how does it work?
Cash App is a peer-to-peer (P2P) payment app that allows users in the United States and the United Kingdom to send and receive money digitally. Over time, Cash App has expanded beyond transfers and now also offers features such as debit cards, direct deposits, savings tools, and investing options.
If you recently moved to the United States or are exploring digital financial tools, you have probably heard of Cash App. The app is widely used for sending money between friends, paying for purchases, and managing certain financial activities directly from a smartphone.
For many immigrants in the United States, understanding how Cash App works is important because it may appear similar to a traditional bank account, but it is not exactly the same thing.
What is Cash App?
Cash App is a mobile financial app that allows users to send, receive, store, and spend money digitally through their phones. The app is commonly used for:
- Sending money to friends or family
- Receiving payments
- Paying for purchases
- Using a debit card linked to your balance
- Receiving direct deposits
- Buying stocks or Bitcoin
Unlike traditional banks, Cash App primarily operates through its mobile app rather than physical branches.
How does Cash App work?
To start using Cash App, you need to download the app, create an account with a U.S. phone number or email, and link a bank account or debit card. Once the account is set up, you can send or request money by searching for another person by their $Cashtag, phone number, email, or QR code.
Standard transfers typically arrive in 1 to 3 business days to a linked bank account. Instant transfers to a debit card usually carry a percentage-based fee.
How much does Cash App charge? — Fee table
| Service | Typical Cost |
|---|---|
| Standard bank transfer (1–3 business days) | No additional fee |
| Instant transfer to debit card | Percentage-based fee |
| Sending money using linked credit card | Additional fee may apply |
| ATM withdrawals | Fee may apply depending on conditions |
| Account opening | No monthly fee |
Fees and terms may change over time. Always review the official Cash App website before using financial services.
Is Cash App safe?
Cash App uses encryption and security features like Face ID and Touch ID. However, like any P2P payment platform, it is important to use it only with people you know. Once sent, money generally cannot be recovered if the transaction went to the wrong person.
Is Cash App available in Spanish?
Spanish-language support availability on Cash App may vary. The app's primary experience is mainly in English, which can be a limitation for users who prefer to operate in Spanish.
Can an immigrant open a Cash App account?
Cash App has its own eligibility requirements for account opening. Requirements may include a U.S. phone number or email address, and additional verification information may be required. It is recommended to review Cash App's current terms directly.
Limitations of Cash App for Latino immigrants
- Does not support international remittances to Latin America
- Spanish-language experience may be limited
- May not accept Latin American IDs for account opening
- No dedicated 24/7 Spanish-language support
Cash App vs. Común — Quick comparison
| Feature | Cash App | Común |
|---|---|---|
| P2P payments in the U.S. | Yes | Yes |
| Debit card | Yes | Yes |
| Stock and Bitcoin investing | Yes | No |
| Remittances to Latin America | No | Yes |
| Spanish-language experience | Spanish-language support availability varies | Yes |
| Payroll direct deposit | Yes | Yes |
| Open account with Latin American IDs | Eligibility requirements apply | Yes |
| Monthly maintenance fee | Varies by service usage | No monthly maintenance commission |
| Minimum balance requirement | Not always required | $0 |
FAQ
Is Cash App available in Spanish?
The app primarily operates in English. Spanish-language support availability may vary.
Can I send money to Mexico with Cash App?
No. Cash App does not support international money transfers to Mexico or other Latin American countries.
How much does Cash App charge for instant transfers?
Cash App charges a percentage-based fee for instant transfers to a debit card. Verify current fees on the official Cash App website.
Is Cash App safe?
Cash App uses encryption and identity verification. However, P2P transfers are difficult to reverse. Use it only with people you know and trust.
What is the difference between Cash App and Común?
Cash App focuses on domestic payments in the U.S. Común also offers domestic payments but additionally includes remittances to Latin America, full Spanish-language support, and the ability to open an account with more than 100 Latin American IDs.
Común is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank, Member FDIC. Peer-to-peer payments services are provided by Cross River Bank. No minimums, no monthly maintenance commission.
Instant payments
Safe and fast ways to send money without a bank account
8 min de lectura
Did you know it is possible to send money without having a bank account? The lack of access to financial services is a problem that negatively affects the quality of life of thousands of immigrant workers in the United States.
For example, according to a recent survey, the rate of the Latino community in the United States without a bank account dropped from 15% to 10% over the last two years. However, it remains high compared to the national average of 4.5%.
While having a bank account facilitates financial transactions such as transfers, in-store payments, and online purchases, there are now alternatives that allow you to access banking services without needing an account.
Below, you will discover how to transfer money from one card to another without an app or bank account, as well as the safest and simplest methods available to you.
Sending Money Online
Not having a U.S. bank account is not an obstacle to sending money domestically or internationally, as there are methods widely used among immigrant workers who regularly send remittances and conduct other transactions using prepaid cards and cash payments.
International Money Transfer Providers
This is one of the most popular ways to send money without a bank account due to the accessibility, variety of payment methods, and broad coverage typically offered.
International money transfer providers are companies that specialize in facilitating money transfers from one country to another. The key features of these services include:
- Specialization in international money transfers, unlike traditional banks, which have certain limitations, such as high commissions, unfavorable exchange rates, extensive delivery time, and participation of intermediaries that increase costs.
- More affordable fees.
- Various sending methods.
- Multiple Money Transfers Locations
How to Send Money Without a Bank Account Through an International Transfer Platform
Comun allows you to send money to your loved ones for a modest transfer fee starting at USD 2.99 up to the applicable limits. It is very simple; just follow these steps:
1. Open your account with Comun; it will only take a few minutes!
2. Choose the most convenient delivery method for your recipient, such as cash pick up at a physical store like Oxxo, Grupo Elektra, 7 Eleven, and more.
3. You may also send money directly to a bank and have it picked up at one of its branches.
4. Track the delivery directly in your Comun mobile application.
Comun is an excellent option for our community, as it provides Spanish-language service, which is highly appreciated by the immigrant community. Open your account today and start sending money without complications.
What Information Do You Need to Send Money Without a Bank Account?
To send money without a bank account, you only need the following information about your recipient:
- Full name of the recipient, exactly as it appears on their official ID.
- Recipient’s phone number.
- If the transfer is made to a bank account, you will also need:
- Recipient’s address.
- Bank account number, depending on the receiving country.
P2P Services
P2P (peer-to-peer or person-to-person) services allow immediate money transfers between individuals without intermediaries. These options are useful for everyday needs such as paying rent, shared services, splitting transportation costs, and sending money to your relatives in the US or internationally.
How to Send Money Without a Card Using P2P Services
- Choose a reliable provider, such as Cash App or Venmo.
- Enter the recipient’s phone number in the mobile app.
- Confirm the transaction and track it.
Sending Money by Mail
Other alternatives involve sending a cashier’s check, a certified check, or a money order through the postal service.
Cashier’s Check
This type of check is issued with the bank’s funds. The customer must pay in cash or directly from their account, and the check is made payable to the recipient.
Certified Check
This check is issued using the customer’s funds. The issuer must have a bank account so that the bank can verify the availability of funds. The recipient may cash the check directly at a bank branch.
Money Order
Another way to send money without a bank account is by using a money order, which is a type of prepaid payment order. To do so, you will need to:
1. Go to a post office or authorized retailer, such as USPS or Walmart, to purchase a money order.
2. Write the beneficiary’s name in the “pay to the order of” section.
3. Write your name in the “purchaser” section.
4. Sign in the space designated for the purchaser, generally on the front of the document.
5. Keep the receipt with the serial number.
6. Pay the amount to be sent plus applicable service fee.
7. Send the money order via regular or certified mail.
8. Write the recipient’s address in the center of the envelope and the sender’s address in the upper left corner.
9. Purchase a postage stamp at the post office and attach it to the envelope.
10. Drop off the envelope at the post office.
The recipient may cash the money order at an authorized branch upon presenting valid personal identification.
The downside of this alternative is that it takes longer to arrive, as it relies on a traditional mailing method.
Sending Money With Prepaid Load
There are other options available to send money without a bank account, such as prepaid cards and mobile applications.
Reloadable Prepaid Cards
Reloadable prepaid cards function similarly to debit cards, with the main difference being that they are not linked to a bank account. They also allow you to pay for services and make online purchases.
To send money using a prepaid card, you only need to:
1. Identify an international money transfer service that supports prepaid cards, such as Western Union or MoneyGram.
2. Select your preferred provider and choose the prepaid card option on their website.
3. Enter the recipient’s information, making sure it is compatible with the selected platform.
4. Confirm the transfer and pay the amount plus the applicable service fee.
Done! The recipient will receive the money on the prepaid card as if it were a bank transfer.
Mobile Wallets/Applications
Lastly, you may opt for mobile wallets or applications that offer money transfer capabilities. Some examples include Cash App, Venmo, and Remitly, which provide access to an mobile app you can use to send and receive money.
These applications do not require a bank account and are user-friendly. Some also offer physical cards that function similarly to debit cards.
7 Essential Tips for Sending Money Without a Bank Account
1. Verify the Identity and Information of the Recipient
Ensure that the recipient’s information, such as name, account number, or phone number, is entered correctly. Any discrepancies could prevent the recipient from collecting the funds.
2. Compare Fees and Exchange Rates
Each provider has its own rates depending on the receiving country, amount, and exchange rate. Remember, with Comun you do not pay excessive fees, and you ensure your family receives more for less.
3. Know the Sending Limits
Some platforms have sending limits that should be considered before selecting a service. For instance, Western Union has a daily limit of USD 7,499, while Cash App allows up to USD 7,500 per week for verified accounts.
4. Keep All Receipts and Reference Numbers
Even though these methods are secure, it is important to keep receipts and reference numbers in case a clarification or issue arises.
5. Use Reputable and Secure Services
It is essential to ensure that you use a trusted service. Check online reviews and verify that the provider has an official website and/or physical offices.
6. Be Cautious of Scams
Unfortunately, scams are common around financial services. No legitimate institution will request passwords or verification data. Always access official websites. If in doubt, visit an authorized branch.
7. Consider Delivery Time
Most options allow you to complete transfers in minutes, but some may take several days. Consider this before choosing your preferred service.
Frequently Asked Questions
Is it safe to send money without a bank account?
Absolutely. Comun is backed by leading financial institutions to protect your funds up to the applicable limits. Additionally, you can track your transfer directly through the Comun mobile app.
How much does it cost to send money without a bank account?
Comun offers a transfer fee starting at USD 2.99, regardless of the amount you send up to the applicable limits. Your first transfer is commission-free!
How long does it take for the money to arrive?
Cash is typically available within approximately 1 hour at the selected store or bank branch.
What documents do I need to send/receive money without an account?
You need the full name of your recipient, and they must present official identification.
Instant payments
Direct deposit vs wire transfer: comparison guide for U.S. immigrants
8 min de lectura
Direct deposit vs wire transfer: comparison guide for U.S. immigrants
These payment methods are both available in the U.S. but they are often used for different purposes. Direct deposit is commonly used for paychecks, tax refunds, and government benefits, while wire transfers are more often used for urgent or high-value transfers between financial institutions.
Understanding the difference between direct deposit and wire transfers can help you avoid unnecessary fees, choose the right payment method for your situation, and manage your money more confidently.
What's the difference between direct deposit and wire transfer?
The biggest difference is the purpose they serve. Direct deposit is commonly used for recurring payments such as salaries, benefits, and tax refunds. Wire transfers are commonly used to move money quickly between financial institutions, particularly for large or time-sensitive transactions.
| Feature | Direct deposit | Wire transfer |
|---|---|---|
| Common use | Paychecks, benefits, tax refunds | Large or urgent transfers |
| Network used | ACH network | Wire transfer network |
| Speed | Typically 1–3 business days | Often same day or next business day |
| Typical cost | Often no fee to receive | Fees may apply |
| International transfers | Limited | Commonly used |
| Recurring payments | Yes | Less common |
| Setup required | Routing + account number | Bank details + recipient information |
How direct deposit works
Direct deposit is one of the most common payment methods in the United States, particularly for employees receiving wages from an employer. Instead of issuing a paper check, an employer sends the payment electronically to the employee's bank account through the ACH network.
To set up direct deposit you need to provide your employer: your bank's routing number and your personal account number.
How wire transfer works
A wire transfer is an electronic transfer of funds between financial institutions through secure financial networks like Fedwire or SWIFT. Unlike direct deposit, wire transfers are better suited for large one-time payments, urgent payments, real estate transactions, or international transfers.
When to use each one
Use direct deposit for:
- Receiving your paycheck
- IRS tax refunds
- Social security or unemployment benefits
- Recurring business payments
Use wire transfer for:
- Real estate payments (down payment, closing)
- Urgent international transfers
- High-value business payments
- When the recipient specifically requires a wire transfer
How to set up direct deposit with Común
With your Común account, you can set up direct deposit by providing your Común routing number and account number to your employer. Your Común account has unique routing and account numbers available in the app. Visit comun.app to learn more.
FAQ
Is direct deposit faster than wire transfer?
Not necessarily. Domestic wire transfers can be faster (same day), while direct deposits usually take 1-3 business days. However, many accounts offer early access to direct deposits up to 2 days early.
How much does it cost to set up direct deposit?
Setting up direct deposit is generally no fee. Employers use the ACH network to send payroll electronically at no charge to the employee.
Común is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank, Member FDIC.
International Money Transfers
What are remittances?
8 min de lectura
Remittances are money transfers an immigrant sends to family back home. With Común, sending a remittance to Latin America costs as little as $2.99, with a competitive exchange rate and delivery within minutes in most cases.
Living and working abroad? Remittances might be for you if you want to send money to family members, friends, or other beneficiaries in another country.
Remittance is money transfers from one person to another, usually across borders. They are most commonly sent by immigrants who send a portion of their income to support their families back home. However, remittances can also be personal gifts, financial support, or payments between relatives or friends who maintain social or economic ties despite the distance.
Do you know the difference between a remittance and a bank transfer payment?
Remittances can be money transfers, however what is commonly understood as remittances are voluntary person-to-person transfers, usually between family members. For example: a worker in Texas sending money to their parents in Mexico, a nurse in Florida sending money to her siblings in Honduras, or a student helping their grandparents in Guatemala. Bank transfers on the other hand, can include payments between companies, international trade payments, foreign direct investment, loans between corporations, or government aid.
In summary, remittances are personal, cross-border, person-to-person transfers.
How can you send remittances from the United States to Latin American countries?
Today there are more options than ever to send money to Latin America from the U.S. The process is usually very simple:
#1 Choose a remittance provider
Your remittance service provider can be a financial mobile application, a traditional bank like Wells Fargo, a specialized money transfer service like Western Union or MoneyGram, or a fintech company like Remitly.
#2 Select the destination country and delivery method
Each company offers different delivery options depending on their services and local partnerships. Delivery options vary in cost depending on the provider and the urgency.
#3 Enter the amount and confirm the exchange rate and fee
The amount received by the recipient varies by the exchange rate used by the provider and the service fee they charge. Some companies might charge no fees, but their business model relies on the exchange rate markup.
#4 Pay for the remittance
With so many options available, remittances can be paid with various methods including:
- Bank account (ACH).
- Debit card.
- Credit card (often the most expensive).
- Cash
#5 The recipient receives the money
It can take minutes to days for the recipient to receive the funds, depending on how the funds are received or by the type of remittance provider used to send the remittance.
How much does it cost to send remittances from the United States?
The total cost depends on two main factors:
1. Service fees
This is the fee the provider charges to send the remittance. It can range from $0 to over $20 USD per transaction depending on the provider and payment method used.
- Bank account: typically the cheapest.
- Debit card: mid-range cost.
- Credit card: most expensive (fees + potential interest)
2. Exchange rate costs
Some companies have different exchange rates, making the remittance more expensive even if the service fee is advertised as “$0.” Sometimes the fee for the service provider is included within the added margins in exchange rates.
3. Other possible additional costs
These may include cash pickup fees, limits for high transaction amounts, or fees charged by participating banks. It is important to understand the fees in remittance costs to be able to manage your funds in a way that makes sense to you.
What should you consider before sending money abroad from the United States?
To choose the best option, you can always consider:
- Total costs (fee + exchange rate). Sometimes comparing only the fixed fee is not enough to fully understand the cost of a remittance or transfer.
- Delivery time. If the recipient needs the money the same day, it could be best to choose an quick service.
- Delivery method. Cash pickup can be useful if the recipient doesn’t have a bank account. Other options include bank deposit or digital wallets, which can be practical and low-cost.
- Convenience for the sender. If you send money frequently, it is recommended to evaluate apps that allow saved recipients, automatic payments, recurring transfers, or exchange-rate alerts or options that adjust and serve your needs.
- Limits and requirements. Not all money transfer service providers are the same. Some services require government-issued identification to provide their services, while others require a U.S. bank account and, in some cases, proof of identity (some providers accept foreign passports as proof of identity to send remittances if the sender can prove residency in the United States) for large transfers.
What Companies Offer Remittance Services from the United States?
In the U.S., there are several types of companies offering remittance services:
Traditional money transfer companies, for example: Western Union, MoneyGram, and Ria Money Transfer. These companies have physical branches in many locations. Fees could be higher than alternatives and the exchange rates can be less competitive.
Traditional banks: However, not all banks provide this service, but institutions like Bank of America and Wells Fargo allow international transfers through online banking or in-branch. However, it is important to consider that the fees can reach up to $60 USD depending on the bank, and transfers can take up to 5 business days. For this option, a bank account with the institution is needed or cash transfers are done directly at a branch.
Digital first companies (apps): Examples include Remitly, Wise, WorldRemit, and Xoom (from PayPal). These companies can offer more competitive pricing and faster transfers. These options are presented as an alternative to traditional banks or Western Union. Comun is one of these platforms, combining a fintech experience with extra benefits like a digital account and an easy-to-use app available in Spanish.
Convenience stores: For example, Walmart offers in-person remittance services. For example companies like Comun can also offer services like cash funding in retails or ATM locations. With a Comun open account you can deposit cash at one of over 90,000 retail locations (Walmart, 7-Eleven, Walgreens, and more) and then complete the remittances conveniently from your app.
What do I need to send remittances from the United States to Latin American countries?
Requirements vary by provider and they depend on:
-How the remittance is sent, and
-How the remittance is received.
For example, if sending money for cash pickup, the most important information is the recipient’s full legal name as it appears on their official ID, since they’ll potentially need to present it to pick up the money.
For a bank-to-bank international transfer, the essential information includes the bank details for the receiving account.
Traditional banks and companies like Western Union generally require:
- Recipient’s full name.
- Recipient’s account number.
- SWIFT code.
- Receiving country.
- Amount and currency
How can you send remittances using Comun?
Sending a remittance with Comun is very simple. You have two options at the palm of your hand, you can send it through the app or via WhatsApp. Here’s a detailed step by step on how to do it:
Through the Comun App
- Open your Comun app.
- Select “Transfer.”
- Select “International.”
- Under “How do you want to send your money?”, choose “Through the app.”
- You’ll see the current exchange rate.
- Select an existing recipient or add a new one.
*To add a recipient, you’ll need: full name as on their ID, phone number, and—if sending a bank transfer—their bank details.
- Confirm the recipient’s information.
- Choose the transfer method (bank deposit or cash pickup; options vary by country).
- Enter the sender’s ID type and ID number.
- Confirm transfer details.
- Enter the amount (the calculator shows the amount the recipient will receive in local currency and the transfer fee).
- Confirm the transaction.
And that’s it—your remittance is sent!
Through Comun’s WhatsApp
- Start from our website (by selecting “Send Money”), which will show the WhatsApp option — or.
- From the app, select “Transfer.”
- Select “International.”
- Choose “Via WhatsApp.”
- Follow the conversation flow.
- Choose “Send money.”
- Confirm the country.
- Enter the amount.
- You’ll receive a confirmation message showing the amount to be received in local currency.
- Choose the delivery method.
- Provide the recipient’s details: full name, ID type, ID number, and bank account (if applicable).
- Confirm your remittance.
- Verify your identity through the verification steps.
And you’re done—your remittance is sent!
Best Practices for Sending Remittances
To make sure your get the best out of your hard-earned money, it is recommended to keep some good practices in mind:
1. Verify the exchange-rate margin
Ideally, choose a provider that uses an exchange rate as close as possible to the real market rate as this impacts the actual amount your recipient will receive. Understanding transaction costs can help make better financial decisions for your needs.
2. Look for transparent, fixed fees
Comparing fees can be confusing because many services use variable pricing based on multiple factors. Ideally it is recommended to choose a provider that offers fixed fees and transparent pricing.
3. Consider timing and holidays in both countries
Keep in mind that transfers may be delayed during weekends or holidays in either country, so processing times may be slower than on regular business days.
What exactly is a remittance?
It's money a person sends from the country where they work back to their home country, typically to support family.
How do I send a remittance with Común?
In the app, select "Send a remittance," choose the destination country and delivery method, add the recipient, and confirm the amount and fee before sending.
Which countries can I send money to with Común?
Común supports remittances to Mexico and other Latin American countries; check the full list of available countries in the app.
Frequently asked questions
What's the difference between a remittance and a regular bank transfer?
A remittance is specifically designed for international transfers to family, usually with delivery methods like cash pickup or deposit to an account in the destination country.
How much does it cost to send a remittance with Común?
Starting at $2.99 per transfer, with your first transfer at no cost.
Do I need a Común account to send remittances?
Yes, remittances are sent from your Común account inside the app.
How long does a remittance take to arrive?
Most transfers arrive within minutes, depending on the country and delivery method.
Can I send remittances in cash, or only to a bank account?
Both options exist depending on the country; in Mexico, for example, you can use cash pickup at locations like Elektra or Oxxo.
Is it safe to send remittances through an app?
Común works with a licensed remittance provider and shows the full exchange rate before you confirm each transfer.
Financial Education
Exchange Rates and Currency Margins: A Simplified Explanation
8 min de lectura
Introduction: What Is the Foreign Exchange Market?
The foreign exchange (FX) market is the backbone of global trade, since it allows one currency to be exchanged for another. Whether you're traveling abroad, buying international products, or investing overseas, FX plays a crucial role in our financial lives. This article aims to demystify two key FX concepts: exchange rates and currency margins, explaining them in simple terms for new banking customers and anyone unfamiliar with these topics. Understanding these concepts is crucial for customers of Community Federal Savings Bank and other financial institutions that offer banking services.
What Is the Exchange Rate?
The exchange rate is the value of one currency in terms of another. For example, if 1 U.S. Dollar (USD) is worth 0.85 Euros (EUR), the exchange rate is 1 USD = 0.85 EUR. Exchange rates fluctuate based on supply and demand in the foreign exchange market. Several factors influence these rates, including:
- Supply and Demand: If a currency is in high demand, its value increases. Conversely, if there's more supply than demand, the currency's value decreases.
- Central Banks and Government Policies: Central banks, like the Federal Reserve in the U.S. or the European Central Bank, can influence exchange rates through interest rates and monetary policy. For example, higher interest rates offer better returns on investments in that currency, increasing demand and value.
How Do Exchange Rates Affect Us?
Exchange rates impact several aspects of our lives:
- International Travel: When you travel abroad, the amount of foreign currency you get for your money depends on the exchange rate. For Común customers, understanding exchange rates⁴ helps keep your money secure while traveling. Examples of fluctuating exchange rates include: 1 USD = 0.85 EUR or 1 USD = 109.75 Japanese Yen (JPY).
- Cost of Imported Products: Products priced in foreign currencies become more or less expensive depending on the exchange rate.
- International Business and Investment: Businesses dealing with international customers and suppliers, or investing abroad, are affected by exchange rate fluctuations, which influence their costs and revenue.
What Is the Currency Margin (FX Spread)?
The currency margin is the difference between the buy price and the sell price of a currency pair. The buy price is what buyers are willing to pay, while the sell price is what sellers are asking. The spread is essentially the cost of trading currencies.
For example, if the buy price for EUR/USD is 0.84 and the sell price is 0.86, the currency margin is 0.02. This margin is crucial because it represents the transaction cost of exchanging currencies, which is a key consideration for banks and financial institutions.
Why Does the Currency Margin Exist?
Several factors contribute to the existence of the currency margin:
- Market Liquidity: Greater liquidity (more buyers and sellers) generally results in a narrower margin. Lower liquidity leads to a wider margin.
- Currency Brokers and Financial Institutions: These intermediaries set the buy and sell prices, factoring in their profit margins.
- Transaction Costs: The costs of executing trades and maintaining currency inventories are also built into the margin.
How Does the Currency Margin Affect Transactions?
The currency margin impacts the cost of exchanging money. A smaller margin means lower costs, while a larger margin increases the cost. Here are some examples:
- Small Margin: If the buy-sell margin is small (for example, 0.01), the transaction cost is low, making it cheaper to exchange currency.
- Large Margin: A larger margin (for example, 0.05) means higher transaction costs.
To minimize the cost of exchanging currency, consider:
- Comparing Rates: Look for the best exchange rates and lowest margins, especially when using Community Federal Savings Bank banking services.
- Timing: Exchange money when market liquidity is high, typically during business hours in major financial centers.
Real-World Examples:
Understanding currency margins can help you make better financial decisions:
- Traveling Abroad: When exchanging money for a trip, the currency margin affects how much foreign currency you receive. Común¹ account holders can keep their money secure by understanding these margins.
- Online Shopping: Buying products on international websites involves currency conversion, where the margin influences the total cost.
To check the current exchange rate and currency margin, use online currency converters and financial news websites. Financial inclusion matters, and platforms like Común offer tools and support to help Latino immigrants and other users manage their money effectively.
Conclusion: Stay Informed
In summary, the exchange rate determines the value of one currency against another, while the currency margin is the cost of trading currencies. Understanding these concepts is essential for making informed financial decisions, whether you're a new banking customer or new to the world of FX. Stay informed and use this knowledge to navigate the complex world of currency exchange more effectively.
Additional Resources
- FDIC-Insured Banks: Make sure your funds are safe by choosing FDIC-insured banks like Común.
- Support and Security: Común offers customer support and security features to protect your personal information and funds.
- Remittances: For Latino families and immigrants, understanding exchange rates can help send money abroad efficiently.
Understanding exchange rates and currency margins can have a significant impact on your financial transactions. By staying informed, you can make better decisions and optimize your currency exchanges, improving your overall financial health.
Financial Education
Digital wallet: what it is, how it works, and how to use it in the U.S.
8 min de lectura
If you’re looking for a safe, simple way to manage your money, a digital wallet could be the ideal complement to your finances. It’s a mobile application that lets you bring together your cards and other financial products in one place.
In recent years, it has become a key tool for digital money management due to its convenience and security.
Below we explain in detail what a digital wallet is, common uses, advantages, and some examples of the most popular digital wallets in the United States.
What is a digital wallet and how does it work?
A digital wallet is an application for Android- or iOS-compatible devices that securely stores credit or debit card details, or bank account information and lets you access it quickly and safely to make digital payments and other transactions.
How it works is simple: you register your banking information in the app, where it’s encrypted to keep it secure and prevent third-party access. This lets you make electronic payments in seconds through several methods—scanning a QR code, using a smartphone with NFC technology, or selecting the digital wallet at checkout for online purchases.
There is a wide variety of digital wallets in the United States; the most popular include Apple Pay, Google Wallet, Samsung Pay, and PayPal.
Most common uses of a digital wallet
A digital wallet simplifies day-to-day transactions for the thousands of immigrants living in the United States. These are the most common uses of this type of tool:
Pay in-store and online
Using a digital wallet in a store is easy as long as the merchant accepts contactless payments. In that case, simply enable NFC on your phone and hold it near the payment terminal. The payment will process automatically without entering additional information.
To pay online, first make sure you’ve added your bank accounts to the wallet’s mobile app. Then go to the product or service page and choose your digital wallet as the payment option. You may be prompted to enter an authentication factor for security.
Send money to family and friends
Another common use of digital wallets—especially among immigrant users in the U.S.—is sending remittances quickly to their home countries. Depending on the app, these can be less costly than traditional banks.
Store cards and documents
A digital wallet is also a handy organizational tool for keeping not only financial products like debit and credit cards, but also other digital items such as transit cards, tickets, and discount coupons.
Manage your money better
These applications also make it easy to keep your finances organized, create monthly budgets, and stay on top of day-to-day transactions.
4 advantages of using a digital wallet
Managing your financial products with a digital wallet has several notable benefits that can completely change how you make digital payments.
1. Security: lower theft risk compared with carrying cash.
Carrying cash is always riskier than digital options because of loss or theft. A digital wallet removes the need to depend on cash and streamlines payments online and in physical stores.
In addition, your personal information is encrypted so only you can access it. You can also add app-level security like biometrics and passcodes, facial recognition, and Touch ID.
2. Convenience: everything is on your phone, without carrying multiple cards.
Beyond avoiding cash, a digital wallet also means you don’t need to carry physical cards everywhere—you can add your accounts in the digital wallet app and pay from your mobile device.
3. Financial inclusion: ideal for immigrants without easy access to traditional banks.
A common challenge for immigrants newly arrived in the United States is meeting the requirements to open a traditional bank account. In contrast, a digital account would be far more accessible option for everyday essentials like receiving money, paying bills, and sending remittances to Latin America quickly and easily.
4. Financial control: lets you review expenses and organize money more clearly.
With a digital account, you can more easily track your money by enabling notifications on your phone to stay aware of every payment.
It can also log all your transactions and help maintain a monthly budget to ensure your money covers your U.S. expenses while supporting family in Latin America.
Examples of popular digital wallets in the United States
- Apple Pay
This is Apple’s official payments service and is built into all its products by default, such as iPhone and Apple Watch. One major advantage is that more than 85% of merchants in the United States accept it.
Its wide acceptance makes it very convenient for immigrants, whether for everyday shopping or paying monthly bills.
It also offers Apple Cash, which functions like a digital card and allows sending and receiving money, but it’s only available in the United States.
- Google Wallet
This is a virtual wallet available to Android mobile users. It’s a more complete option than its predecessor Google Pay, with features such as tap-to-pay.
It’s very useful for immigrants because it also stores official documents like licenses and various IDs.
- PayPal
PayPal is one of the most popular digital wallets not only in the U.S. but worldwide. It lets you store payment information easily, and sending money to other countries is straightforward thanks to its wide coverage.
- Cash App
Cash App is an application that lets registered users send and receive money. It may be a suitable alternative if you need a debit card and ATM withdrawals.
Manage your money as an immigrant with Común
In this article we showed you that a digital wallet is an application to store all your financial information in one place, plus the advantages, how they work, and the most popular brands in the United States.
If you want to simplify your finances, get to know Común, the platform that offers you:
- A checking account with clear, competitive fees.
- A debit card you can link to a digital wallet.
- Fast money transfers with affordable fees.
- Mobile banking available in Spanish and English
Open your Común account today with official ID from your country and start using your digital wallet to manage your money in the U.S.
Frequently asked questions
If you still have questions, see the section below.
What is the most reliable digital wallet?
You can choose options like Apple Pay, Google Wallet, and PayPal, as they have sufficient reputation for handling personal information.
How do I activate a digital wallet?
Download the application via Google Play or the App Store, create an account, add your cards, and complete the necessary verification.
Is it safe to use a digital wallet?
Yes, because they use encryption and tokenization to keep your information secure.







Thousands of immigrants are already achieving more with their money. You can too.
Comun is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank; Member FDIC. The Comun Visa® Debit Card is issued by Community Federal Savings Bank, pursuant to a license from Visa U.S.A Inc. and may be used everywhere Visa Cards are accepted.
Comun is a fintech company and not a bank or licensed money transmitter.
* Results may vary. For a complete list of eligible IDs and application requirements, follow this link.
^ No minimums, no maintenance fees. ATM or transfer fees may apply. See app for fee details.
‡ Direct deposit funds are typically available when we receive the payment file, up to two days before the scheduled payment date. This early availability is not guaranteed.
** A service provided by Service UniTeller, Inc. Service UniTeller, Inc. is licensed in all states that require a license. Remittance fees start at $2.99 but may vary. Please check the app for more details. Comun Inc. may earn revenue from the conversion of foreign currencies.
† Funds in your account are FDIC insured up to $250,000 by ownership category through Community Federal Savings Bank (CFSB), Member FDIC, in the event CFSB fails.


