
Financial Education
The Definitive Guide to Managing Checks in the Digital Age
Digital checks make your banking easier and safer. With Común, deposit and cash checks from your phone, no lines, no extra costs. Open your account today.
8 min read

15 Jun 2024

The shift from physical to digital checks marks a significant transformation in financial services, driven largely by technological advances and the widespread adoption of mobile devices and online banking platforms. This shift reflects a broader trend in the digital era, where convenience and efficiency come first. The importance and benefits of having a checking account in this context can't be overstated, since it enables direct deposit and check deposit through ATMs, saving users significant time and money.
How Banks and Financial Institutions Are Adapting
Banks and financial institutions have been at the forefront of this digital shift. Recognizing their customers' needs and preferences, these institutions have invested heavily in developing secure, user-friendly online banking services and mobile apps. These platforms let users complete a wide range of transactions that traditionally required a visit to a bank branch. Now, customers can access their bank accounts and manage payroll checks through direct deposit — a feature that improves the efficiency of receiving paychecks and issuing personal checks directly from their smartphones or computers. This functionality doesn't just simplify the process — it also makes it accessible anytime, anywhere, removing the physical limitations of traditional banking.
Convenience and Accessibility
The integration of online and mobile banking solutions has made financial services more accessible, letting users complete transactions remotely. One example is the PayPal app, which lets users deposit checks into their PayPal account using a photo, accessing their money for free within 10 days or instantly for a fee. This is particularly beneficial for users who need to deposit payroll checks without the delay of mail services or the inconvenience of visiting a physical bank or check-cashing store. For people living in areas without easy access to traditional banking facilities, or those with mobility issues, these digital options provide essential financial access, improving their ability to manage personal finances efficiently.
Enhanced Security Features
Along with convenience, security is a priority in the evolution of digital check processing. Financial institutions have implemented sophisticated security measures to protect users and their transactions. These include encryption, two-factor authentication, and secure sockets layer (SSL) technology, which protect data transmitted during online and mobile banking sessions. Additionally, features like automated fraud detection systems monitor unusual activity, helping prevent unauthorized access and transactions.
Verification processes for digital check transactions have also become more robust. Digital checks often require multi-factor authentication, which can include biometrics (like fingerprint or facial recognition), security questions, or mobile code confirmation. These layers of security help ensure only authorized users can issue, cash, or deposit checks, significantly reducing the risk of fraud.
The shift to digital check processing through online banking and mobile devices illustrates a broader trend in financial transactions toward greater technology integration, prioritizing user convenience and security. As this trend continues, we can expect these platforms to evolve even further, offering more features and efficiencies for managing financial transactions in the digital age.
Navigating Check-Cashing Services and Fees in the Digital Age
Traditional banks continue to offer check-cashing services at their branches, but the rise of digital platforms has diversified how consumers can cash a check and access their money. For those without a bank account, a check-cashing service provides a vital option for turning checks into cash, often at physical locations. Digital services like PayPal let users deposit checks directly into their PayPal accounts just by taking a photo of the check, making a PayPal account an essential tool for digital check deposits. Mobile apps like Ingo Money offer similar services, allowing check deposits directly to prepaid cards, PayPal accounts, or even as Amazon credit. These tools offer a level of convenience and speed traditional banks often can't match, since they skip the need to visit a physical location.
Understanding Check-Cashing Fees
Each check-cashing option has its own set of fees. Traditional banks may charge non-customers a fee to cash checks, and these fees can be particularly high for personal or third-party checks. Grocery stores and check-cashing stores typically charge a percentage of the check amount, which can vary widely depending on the type and amount of the check. Services like Western Union also facilitate check cashing, but often with higher fees, especially for instant-cash services.
Digital platforms vary in their fee structures. PayPal, for example, offers free check deposit if the user is willing to wait a few days for funds to settle, but a faster-access option is available for a small fee. Ingo Money also charges fees for instant access but offers a fee-free option if the user is willing to wait for funds.
Reducing Costs and Increasing Convenience With Digital Solutions
Digital solutions offer significant advantages in terms of reducing check-cashing costs and increasing convenience. By enabling direct deposits into checking accounts or onto prepaid cards like the Walmart MoneyCard, these digital platforms eliminate the need for physical check-cashing locations. This not only saves on the cost associated with cashing checks at physical locations, but also reduces the time spent processing transactions.
Additionally, the ability to deposit checks anytime, anywhere via a mobile device or computer means funds are available faster and without the inconvenience or expense of traveling to a bank or check-cashing store. This accessibility is particularly beneficial for people in remote areas or those with mobility issues, for whom visiting a physical location is a challenge.
In summary, the digital transformation of check-cashing services has given consumers a wider range of options for accessing their money quickly and securely, often at lower costs than traditional methods. The convenience of digital platforms extends to the ability to send money quickly and securely, further improving the user experience in managing financial transactions. As technology continues to advance, we can expect further innovations that will improve the efficiency and convenience of these financial transactions.
The Role of Third-Party Checks in Modern Financial Transactions
Handling third-party checks and pre-printed checks is critical within the digital banking framework. These checks, essential for numerous transactions like payroll payments and government payments, must be managed with strict security measures to ensure the integrity of financial processes.
Handling Third-Party Checks
Third-party checks involve transferring funds from the payer to an intermediary recipient, who then endorses the check to another party, known as third-party check endorsement. This process is particularly useful when the original recipient needs to endorse a third-party check to someone else, either because they lack valid ID or face limitations that prevent them from cashing the check themselves. The complex nature of these transactions requires rigorous verification processes. Financial institutions require valid ID from anyone attempting to cash or deposit third-party checks to verify their legitimacy. Both the original recipient and the endorser must sign, explicitly authorizing the transfer of funds. This verification helps mitigate risks like fraud, which are higher with third-party checks due to the multiple parties involved.
Managing Pre-Printed Checks
Pre-printed checks are commonly used for direct deposit of payroll and government benefits. They include fixed details like the issuing bank's name, the amount, and the recipient's account information, which are printed by the financial institution or company issuing the check. These checks are usually processed through specialized check-cashing services, which use advanced digital scanning technology to validate the check's details against secure databases, ensuring the payment comes from a legitimate source and is deposited into the correct bank account.
Modern Solutions in Check Cashing
Digital solutions have revolutionized how checks are processed, improving convenience and reducing check-cashing fees. Online banking platforms and mobile devices enable check deposits through mobile check deposit services. These platforms, like those offered by banks and financial services like PayPal and Ingo Money, let users cash checks by taking a photo and uploading it through an app. This method not only streamlines the processing of two-party personal checks and government checks, but also speeds up the availability of funds in checking accounts or on prepaid cards like the Walmart MoneyCard.
In conclusion, the digital transformation in handling third-party and pre-printed checks is improving security, reducing fees, and increasing convenience across the board. This shift doesn't just respond to growing demand for more efficient financial services — it also reflects broader trends toward digitization across every aspect of banking and financial transactions.
Embracing Digital Change in Check Management
The transformation of check management in the digital age is a clear reflection of the broader trend toward technology-driven financial services. This evolution presents a unique mix of challenges and opportunities. As we've explored, the shift from physical to digital checks brings improved security, greater convenience, and significant cost savings, making it an essential trend for both consumers and financial institutions.
The future of check management depends on deeper integration of innovative technologies. Banks and financial institutions are continually improving their digital services to offer users smoother experiences. Innovations like blockchain and artificial intelligence are poised to redefine security and efficiency in financial transactions, offering even more robust protections against fraud and errors.
For individuals, the ability to manage checks through mobile devices and online platforms means easier access to their finances, less time spent on manual processes, and reduced fees associated with traditional check-cashing services. For businesses and financial institutions, digital check processing reduces administrative burden and speeds up capital flow, improving economic efficiency.
In summary, managing checks in the digital age involves a dynamic mix of adapting to current technologies and anticipating the future needs of the financial market. This ongoing evolution promises to make financial management more accessible, secure, and efficient for everyone involved.
About Común
Común aims to support the Latino community in the United States. It offers a debit account that can be opened with more than 100 valid Latin American IDs and an app available in Spanish.
Visit Común's website or download the app for free to learn more about the full offer and applicable terms.
Olivia Rhye
Community Partner

Financial Education
Banking Services for Small Businesses: A Complete Guide
8 min de lectura
Small Businesses
Running a small business involves making numerous financial decisions, and choosing the right banking services is crucial for success. Separating personal assets from business assets in an LLC structure is important for protecting personal property in case of business bankruptcy. Community banks and modern financial platforms offer a variety of services tailored to meet small businesses' unique needs. This complete guide explores the essential banking services for small businesses, highlighting their benefits and how they can support growth and stability.
Understanding Different Types of Small Businesses and Their Banking Needs
Before exploring specific banking services, it's essential to understand the range of small businesses and their unique financial needs. Different types of small businesses — like sole proprietorships, partnerships, LLCs, corporations, nonprofits, home-based businesses, and startups — require tailored banking solutions to support their growth and stability. Keeping business and personal bank accounts separate offers benefits like accurate record-keeping, simplified tax preparation, better financial organization, and enhanced professionalism. By recognizing these differences, you can better appreciate how community banks and financial platforms like Común meet small business owners' diverse needs. This understanding lays the groundwork for selecting the most appropriate banking services to ensure financial health and success.
Business Checking and Savings Accounts
Having a dedicated business checking account is fundamental to managing your finances effectively. It lets you separate personal and business transactions, simplifying bookkeeping and ensuring clear financial records. Many banks offer business checking accounts with features like free transactions, low fees, and online banking capabilities.
When opening a business bank account, gather the required documentation, like your Employer Identification Number (EIN), and decide whether you want to apply online or visit a branch. Understanding the fees and essential steps to open the account is crucial.
A business savings account is also vital. It helps you set aside funds for future investments, emergencies, or growth opportunities. Look for accounts with competitive interest rates and flexible access to your funds.
Business Loans and Lines of Credit
Access to credit is often essential for small business growth. Community banks and other financial institutions provide various loan products, including term loans, lines of credit, and SBA loans. These financial products can help you finance new equipment, expand operations, or cover unexpected expenses.
- Term Loans: Term loans issue lump sums of capital that are repaid over fixed periods of time with predetermined interest rates. They're suited for large, one-time investments, like purchasing equipment or renovating a workspace. The predictable repayment schedule helps with budgeting and long-term planning.
- Lines of Credit: Lines of credit offer flexible borrowing options, letting you draw funds as needed and pay interest only on the amount you use. This flexibility can be a lifesaver during cash flow shortages or when financing immediate needs, like inventory purchases or emergency repairs. Lines of credit are revolving, meaning funds become available again as you repay them, making them an ongoing financial resource.
- SBA Loans: Small Business Administration (SBA) loans are partially government-guaranteed, making them more accessible to small businesses that might not qualify for traditional loans. They offer competitive interest rates and longer repayment terms, which can be particularly beneficial for startups and businesses with less-established credit histories.
Working with a community bank for loans and lines of credit means you benefit from personalized service. Bank representatives can provide tailored advice, helping you choose the right loan product for your needs and guiding you through the application process. This relationship-based approach ensures you get the support needed to grow your business sustainably.

Payment Processing, Payroll, and Cash Flow Management Services
Effective financial operations are critical to any small business's success. This includes processing payments, managing payroll, and ensuring efficient cash flow. Here's how comprehensive banking services can support these needs:
- Merchant Services: Merchant services are crucial for businesses that need to process customer payments. These services include credit card processing, point-of-sale (POS) systems, and online payment gateways. A reliable merchant services provider ensures transactions are processed quickly and securely, improving customer satisfaction and cash flow. By offering seamless payment solutions, banks help businesses deliver a better customer experience and streamline their revenue collection process.
- Payroll Services: Managing payroll can be complex and time-consuming. Many banks offer payroll services to simplify this process. These services handle everything from calculating wages and taxes to direct deposits and payroll tax filing. By outsourcing payroll, businesses can ensure accuracy and compliance with tax regulations, freeing up time to focus on core operations. Efficient payroll management not only saves time, but also helps maintain employee satisfaction by ensuring timely, accurate payments.
- Cash Management: Effective cash management is essential to maintaining healthy cash flow. Banks offer various cash management services, including remote deposit capture, ACH payments, and wire transfers. These tools help businesses efficiently manage incoming and outgoing funds, reducing time spent on manual processes and improving overall financial control. Proper cash management ensures businesses can meet their financial obligations and invest in growth opportunities without experiencing cash shortages.
By integrating these services, banks provide a comprehensive solution that supports small businesses in maintaining smooth, efficient financial operations.
Online and Mobile Banking
In today's digital age, online and mobile banking are indispensable. These services provide convenient access to your accounts, letting you monitor transactions, transfer funds, and pay bills anytime, anywhere.
- Digital Transformation: Community banks are adopting new technologies to improve the customer experience through online and mobile banking platforms. These platforms offer 24/7 access to your accounts, letting you manage your finances from the comfort of home or on the go. You can easily check balances, view transaction history, and transfer funds between accounts.
- Advanced Features: Many online and mobile banking services include features like bill pay, mobile check deposit, and budgeting tools. Bill pay lets you schedule payments to vendors and service providers directly from your account, ensuring timely payments and simplifying your bookkeeping. Mobile check deposit lets you deposit checks by taking a photo with your smartphone, saving trips to the bank.
- Security Measures: Online and mobile banking platforms use advanced security measures to protect customer data and ensure secure transactions. This includes encryption to protect information, multi-factor authentication to verify user identity, and regular security audits to identify and address potential vulnerabilities. Real-time fraud alerts help you quickly detect and respond to suspicious activity, improving your overall financial security.
Open your bank account¹ in 3 minutes with your country's ID²
Common Problems Small Businesses Face With Banking Services and Financial Health
While banking services are crucial to small business operations and growth, many small business owners face various challenges when managing their financial needs. Understanding these issues can help businesses make more informed decisions and find solutions that better fit their requirements.
- High Fees and Hidden Costs: Many small business owners find that banking services come with high fees, including monthly maintenance charges, transaction fees, and penalties for not maintaining a minimum balance. Hidden costs, like wire transfer fees, overdrafts, and additional services, can also add up, putting pressure on the business's cash flow.
- Limited Access to Credit: Securing loans and lines of credit can be particularly challenging for small businesses, especially startups or those with less-established credit histories. Traditional banks often have strict lending criteria, making it difficult for small business owners to access the funds they need for growth and operations.
- Inadequate Customer Service: Small business owners frequently report dissatisfaction with the customer service provided by their banks. Long wait times, lack of personalized service, and insufficient support for small-business-specific issues can hinder a business's ability to effectively manage its finances and resolve issues quickly.
- Complexity and Inaccessibility: Banking services can often be complex and difficult to navigate. Small business owners, who may not have extensive financial knowledge, can find it challenging to understand and use the full range of services offered. Additionally, inaccessibility to bank branches or limited online services can be a significant obstacle for businesses that require frequent banking interactions.
- Security Concerns: With the growing prevalence of cyber threats, security is a major concern for small businesses. Ensuring banking services offer robust security measures to protect sensitive financial data is crucial. However, not all banks offer the same level of security, leaving some businesses vulnerable to fraud and data breaches.
- Integration With Business Tools: Small businesses often use various tools and software to manage their operations, like accounting software and payment processing systems. Issues can arise when banking services don't integrate smoothly with these tools, leading to inefficiencies and increased administrative burden.
- Lack of Financial Education and Support: Many small business owners struggle with financial literacy, which affects their ability to make informed banking and financial decisions. Banks that don't offer enough financial education resources or support can leave business owners feeling overwhelmed and ill-prepared to manage their finances effectively.
- Limited Product Offerings: Some banks may not offer a wide range of products tailored to small businesses' specific needs. This can include specialized loan products, cash management services, or flexible payment solutions. Limited product offerings can restrict a business's ability to find suitable financial tools that support its growth and operational needs.
Understanding these common issues can help small business owners better navigate the challenges they face with banking services. By seeking out community banks or financial platforms like Común that prioritize transparency, customer service, security, and integration with business tools, small businesses can find banking solutions better suited to their needs and supportive of their financial success.
Conclusion:
Choosing the right banking services is essential for your small business's success and growth. From checking and savings accounts to loans, merchant services, and digital banking, the right financial products and support can help you manage your finances effectively and reach your business goals. By partnering with a community bank and leveraging platforms like Común you can access the tools and expertise needed to thrive in today's competitive market.
Integration and Support
Many community banks pride themselves on offering personalized service and financial advice. Building a relationship with your bank can provide valuable insight into managing your finances, accessing credit, and planning for future growth. Take advantage of workshops, seminars, and one-on-one consultations offered by your bank to improve your financial literacy and business knowledge.
For small businesses looking to leverage modern financial technology, integration with platforms like Común can improve their banking experience. Común offers a range of features tailored to small businesses, including instant notifications, secure login, and personalized customer support available seven days a week. By combining the strengths of traditional community banking with the convenience of digital banking, Común provides a comprehensive solution for managing your business finances.
Open your bank account¹ in 3 minutes with your country's ID²
Instant payments
Banks that support Zelle in 2026: Sending and receiving money in the U.S.
8 min de lectura
Banks that support Zelle in 2026: sending and receiving money in the U.S.
Zelle is built directly into many bank accounts in the U.S., which is why it has become one of the most widely used ways to send money. Today, more than 2,000 banks and credit unions offer access to the service.
Understanding how that network works is key to knowing whether you can use it with your account. That distinction matters more today than it did a few years ago. Since April 2025, Zelle is no longer available as a standalone app. Access depends entirely on whether your bank is part of the network.
What Is Zelle?
Zelle is a peer-to-peer payment network owned by Early Warning Services LLC (EWS), a company co-founded by seven of America's largest banks: Bank of America, Capital One, Chase, PNC, Truist, U.S. Bank, and Wells Fargo. It allows you to send money directly from your bank account to another person's bank account using only a phone number or email address. Transfers are typically completed within minutes.
What are the benefits of Zelle?
The main appeal of Zelle is its speed, simplicity, and convenience. Transfers are typically completed within minutes and move directly between bank accounts without the need to load funds into a separate app or digital wallet. In most cases, there are no fees for sending or receiving money, making it a practical option for everyday payments such as rent, shared expenses, or paying friends and family.
Because Zelle is integrated into your bank's app, there is usually no additional setup beyond enrolling your email address or mobile number. Funds are deposited directly into your account and are generally available quickly.
Why does bank support matter?
As of April 1, 2025, Zelle can only be accessed through participating financial institutions. If your bank or credit union does not support Zelle, you generally can't use the service.
Zelle supported banks list
Zelle partners with more than 2,300 financial institutions. To search for a specific bank or credit union, visit zellepay.com/get-started.
Below is a representative, not exhaustive list of financial institutions that currently offer Zelle:
| Name | Transfer limit |
|---|---|
| TRADITIONAL FINANCIAL INSTITUTIONS | |
| Bank of America | Up to $3,500 USD per day |
| Chase | Dynamic limit; typically $500 to $10,000 USD per day |
| Citi Bank | Up to $2,500 USD per day for accounts open longer than 30 days |
| TD Bank | $1,000 USD for instant transfers; up to $2,500 USD for scheduled transfers |
| PNC Bank | Typically $500 to $2,500 USD per day |
| Wells Fargo | Up to $3,500 USD per day |
| DIGITAL BANKS | |
| Ally Bank | Up to $600 USD per day |
| Discover Bank | $500 USD per transaction; $1,000 USD per day |
| SoFi | Up to $1,000 USD per day |
| Truist Bank | Typically $2,000 USD per day to $10,000 USD per month |
| EverBank | Up to $2,000 USD per day |
| CREDIT UNIONS | |
| BECU (Boeing Employees Credit Union) | $1,500 USD per day (instant); $3,000 USD per day (standard) |
| Bethpage Federal Credit Union | Limits vary by account and membership |
| Delta Community Credit Union | Limits vary by account and membership |
| First Tech Federal Credit Union | Limits vary by account and membership |
| Navy Federal Credit Union | Limits vary by account and membership |
Please note that Zelle limits often depend on factors such as account age, transaction history, recipient details, and other risk-based criteria established by the financial institution. Please refer to your financial institution for the most up-to-date information.
How to enroll in Zelle with your bank?
Since the standalone Zelle app has been discontinued, you must enroll through a participating bank or credit union app. The following steps generally apply to most participating financial institution apps:
- Open your bank's mobile app and locate 'Zelle' in the payments or transfer section
- Select 'Enroll with Zelle' or 'Send Money with Zelle'
- Enter your U.S. mobile number or email address
- Verify your identity using a one-time verification code
- You're then able to send and receive money using a recipient's phone number or email address
Please note that both the sender and recipient generally must be enrolled with Zelle through participating financial institutions for transfers to be completed. If the recipient isn't enrolled, they may receive instructions on how to enroll. If enrollment is not completed within the applicable timeframe, the transaction may be canceled and refunded.
Is Zelle Safe? Common scams to avoid
Zelle uses bank-level encryption and security protocols and operates within participating financial institution apps. However, many reported issues involving Zelle are associated with fraud or social engineering scams rather than technical failures.
Because Zelle transfers are typically processed quickly and may be difficult or impossible to reverse once authorized, scammers may attempt to pressure users into sending funds.
Common Zelle Scams in 2026:
Fake bank fraud alerts:
Scammers may send text messages appearing to come from your bank asking whether you authorized a transaction. After you respond, you may receive a call from someone falsely claiming to represent the bank and instructing you to transfer funds to 'reverse' fraud. In reality, the funds are being sent to the scammer.
Impersonation scams:
Scammers may claim to represent a bank, government agency, utility company, or another trusted organization and pressure victims into sending money immediately.
Marketplace scams:
Fraudsters on platforms such as Facebook Marketplace or Craigslist may request payment through Zelle. After funds are sent, the item may never arrive or the payment may later prove fraudulent.
Overpayment scams:
A scammer may claim to have 'accidentally' sent money and ask for it to be returned. Their original payment may later be reversed or determined to be fraudulent.
How to stay safe:
- Use Zelle primarily with people you know and trust
- Never send money to 'verify' your account or reverse fraud
- If you receive an unexpected call claiming to be from your bank, hang up and contact the bank using the number on the back of your debit card
- Enable transaction alerts through your banking app
- Treat every Zelle payment as potentially final before authorizing it
Are there alternatives to Zelle for people without a traditional bank account?
Zelle's transition away from a standalone app in April 2025 created challenges for individuals who do not have accounts with participating financial institutions.
Venmo and Cash App
Remain popular alternatives for domestic transfers and may not require a traditional bank account to get started. However, they generally do not support international money transfers.
Wise
Allows users to receive and send funds internationally using local bank details in many currencies. It is commonly used for international transfers and is known for transparent pricing and exchange rates based on the mid-market rate.
Común
Is a financial platform that promotes financial inclusion for individuals who may face barriers with traditional U.S. banks, offering user-friendly, Spanish-language support. With Común you can make transfers within and outside the U.S. and send money to friends and family throughout Latin America, with fees starting at $2.99 per transfer. Visit comun.app to learn more.
FAQ
Does Zelle charge fees?
Zelle itself generally doesn't charge fees to send or receive money. However, your financial institution may have its own fee structure for the underlying account. It is important to check the specific details with your financial institution.
What if my bank doesn't use Zelle?
Since the standalone Zelle app was discontinued in April 2025, your options may include opening an account with a participating financial institution or using an alternative service such as Venmo, Cash App, Wise, or Común.
Can I use Zelle without a U.S. bank account?
No. Zelle generally requires a U.S. bank or credit union account at a participating financial institution.
Can I send money internationally with Zelle?
No. Zelle supports transfers only between U.S. bank or credit union accounts at a participating financial institution. For international transfers, consumers may consider alternatives such as Wise, Remitly, or international money transfer providers.
What happens if I send money to the wrong person?
Contact your financial institution immediately. Once funds are delivered, cancellation or recovery may not be possible.
Access Matters When Choosing a Bank for Zelle
Choosing between banks that supports Zelle ultimately comes down to access and convenience. While the network is broad, access depends on maintaining an account with a participating financial institution. For some consumers, a traditional bank or credit union may meet their needs. Others may prefer platforms designed to support individuals who face barriers to accessing traditional banking services. If Zelle access is important to you, it may be helpful to consider not only which financial institutions support the service, but also which ones best fit your individual needs.
Financial Education
How to fill out a check in the United States in 5 simple steps (+ Example)
8 min de lectura
Have you ever filled out a check? Although most transactions today are digital, knowing how to fill out a check is essential—especially if you are just beginning your financial life.
According to recent data, one-third of Americans paid by check in 2024, demonstrating that checks still play an important role in the U.S. economy.
You might consider checks an outdated payment method; the reality is that they are useful in specific situations. For that reason, we will explain what a check is, the different types of checks, and how to complete them properly.
What Is a Check and What Is It Used For?
Despite the digital era, checks remain a relevant traditional payment method due to their formality and traceability. They are used for rent payments, purchases, and service payments.
Additionally, checks are a common payment method among the immigrant community, who often use them while adapting to the U.S. banking system.
But what exactly is a check and what are its characteristics? It is a physical document issued by an individual or business (the drawer) to order a bank to pay a specified amount to a third party. For the payment to be processed, the drawer must have sufficient funds in their checking account.
In general, a check contains the following information:
- Name of the drawer, whether an individual or a business
- Name of the payee
- Financial institution where the money will be drawn
- Amount to be paid, both in numbers and in words
- Signatures of the drawer
What Are the Different Types of Checks?
There are different types of checks in the United States. In this case, we will focus on the personal check, although you may choose the option that best suits your needs.
Personal Check
A personal check is a payment order issued by an individual to another individual using the funds in a checking account.
What Is a Personal Check Used For?
The most common uses for personal checks include:
- Rent and utility payments
- Purchase of everyday goods
- Legal agreements requiring documentary support
Certified Check
A certified check serves the same purpose as a personal check but is reviewed and guaranteed by the issuing bank, which verifies that the drawer has sufficient funds and holds them until the check is cashed.
A certified check provides certainty of available funds, making it a more secure method for making and receiving payments.
Cashier’s Check
Unlike a personal check, a cashier’s check is issued directly by the bank, offering greater security for the payee, as the bank is responsible for issuing and safeguarding the funds.
To obtain a cashier’s check, the drawer must visit a bank branch and pay the amount to be transferred. The bank then issues the check in the name of the payee, guaranteeing that it can be cashed using the institution’s own funds and not a personal account.
It is commonly used for high-value purchases such as homes and vehicles.
Money Order
While not strictly a check, it is a traditional payment method with similar functionality.
A money order is a financial instrument that allows funds to be sent via traditional mail using a certified check, which must be purchased and paid for by the drawer at an authorized location.
It allows secure money transfers without requiring a bank account.
How to Fill Out a Check in the U.S.
Before issuing this type of payment order, you must know how to do it properly. Below is an example of how to fill out a check easily, starting from step one:
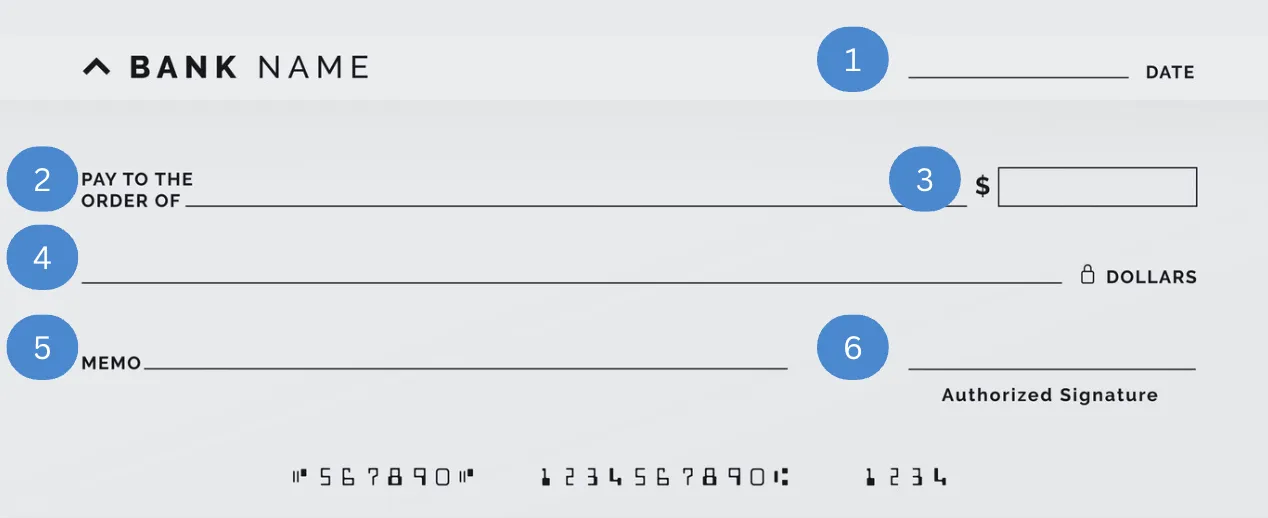
1. Write the Date
Remember that in the United States, the date format is mm/dd/yyyy.
2. Payee’s Name
Write the full name of the person to whom you are issuing the check, exactly as it appears on their official identification.
3. Amount in Numbers
Write the numerical amount clearly.
4. Amount in Words
Write the amount in words, including cents.
5. Add a Memo
You may include a note specifying the reason for the payment.
6. Sign the Check
Sign the check legibly in the space designated for the drawer.
7. Review the Information
Ensure that all information is accurate to avoid issues for the payee when cashing the check.
It is essential to complete checks legibly, without strike-throughs or corrections, as these may invalidate the document.
How to Correctly Write Numbers in Words on a Check
Writing amounts in words may be confusing when dealing with U.S. dollars. The following points should be kept in mind:
- Dollar amounts must be written in full words
- Cents must be written as fractions
- Avoid using dollar symbols or similar notations
- If there is leftover space at the end of the line, draw a line to prevent fraud
- For example, $1,000.75 is written as: One thousand and 75/100 dollars
Cash Checks and Manage Your Money Easily with Comun
As you can see, knowing how to fill out a check is useful for sending and receiving money in the United States. It is a reliable and accessible alternative if you do not have a banking account.
However, issuing and cashing a check can also require significant time and effort. That’s why you can skip the trip to the bank, avoid wasting time or money on gas, and cash your check directly from your phone using Comun—no lines, no questions, no complications.
Discover Comun, the only platform designed to serve the needs of immigrant communities in the United States, with support available in Spanish.
Why Choose Comun?
- Open your account with an official ID from your country
- Access a mobile app specifically designed for immigrants in the U.S.
- Make payments, receive your salary, and manage your finances
- Send money to your loved ones in LATAM for just a $2.99 transfer fee
Frequently Asked Questions
Still have questions about how to fill out a personal check? See our FAQ section.
What if I Make a Mistake Filling Out a Check?
If there are strike-throughs or inconsistencies in the amounts, the check must be voided and a new one used.
How Do I Void a Check?
Write the word VOID in large letters on the front of the check.
What Information Appears on the Back of a Check?
The back of the check contains the endorsement, meaning the payee’s signature for cashing the check.
Community
What You Need to Open an Account at Comun¹ 4
8 min de lectura
Unmatched Ease of Opening an Account
Opening a checking account with Comun is simple and hassle-free, addressing the barriers to financial exclusion typically faced by the immigrant community. Accepting over 100 forms of identification², including social security numbers from Latin American countries, Comun ensures that immigrants have access to essential banking services. The application process is quick, taking less than 5 minutes, and is free of additional or hidden fees, minimum balance requirements or monthly commissions. This inclusiveness is central to Comun's mission of fostering financial stability and growth.
Mobile Deposit Options
ComunComun offers a convenient mobile deposit feature that allows users to deposit cash at more than 88,000 locations in the United States, including major retailers such as Walgreens, Dollar General and Walmart. This extensive network ensures that users can easily find a deposit location near them, making the process of adding money to their accounts simple and hassle-free.
Traditional Banking: Although many traditional banks offer mobile deposit options, they often restrict these to check deposits through a mobile app. Cash deposits typically require a visit to an ATM or bank branch, which can be less convenient and more time-consuming than Comun's extensive cash deposit network.
Utility in Today's World: In today's fast-paced environment, the flexibility to deposit cash in a wide range of accessible locations is invaluable, especially for individuals who may not have easy access to traditional banking services or who work non-traditional hours when banks are closed.
International Remittances
ComunComun excels in facilitating international remittances⁴, allowing users to send money abroad quickly and with lower fees compared to many traditional banks and remittance services. The process is enhanced with real-time notifications, keeping the sender informed from the moment the money is sent until it is received.
Traditional Banking: Traditional banks generally offer international transfer services, but these can be expensive and slow, with transfers sometimes taking several days to complete. In addition, the fees associated with traditional bank remittances can be significantly higher.
Usefulness in Today's World: In a globalized economy, the ability to send money across borders quickly and affordably is crucial. Many families rely on remittances for financial support, and businesses need efficient ways to handle international transactions. Comun's streamlined and cost-effective service effectively meets these modern demands.
Advance Salary Access
Comun: Comun offers the ability to connect wages to the application and receive payment up to two days in advance³. This feature incurs no additional fees, providing significant relief during financial emergencies or when planning ahead.
Traditional Banking: Some traditional banks have begun to offer similar features, but they are often tied to specific types of accounts or require a minimum balance. The accessibility and ease of use of early access to Comun's salary is not always matched in traditional environments.
Usefulness in Today's World: With the rise of gig economy jobs and irregular pay schedules, having early access to wages can provide a buffer against financial instability. This feature is particularly valuable for those living paycheck to paycheck, offering a cushion that can help avoid overdraft fees and late payments.
Unlike traditional banking institutions, Comun's innovative features are designed to meet the needs of today's diverse and mobile population, particularly benefiting the immigrant community in the U.S. By providing services that offer greater convenience, lower costs and greater accessibility, Comun not only addresses common challenges faced by its users, but also empowers them toward greater financial freedom and stability. As we move toward a more interconnected and fast-paced world, the importance of responsive and inclusive financial services continues to grow, something Comun is uniquely positioned to offer.
Robust Security and Customer Support
Security and customer support are paramount at Comun. With FDIC-insured accounts and Visa protection on virtual Visa debit card transactions, Comun customers can manage their funds with confidence. Innovative security features such as biometric logins and instant transaction notifications keep your money safe. In addition, Comun offers 24/7 customer support in English and Spanish, ensuring that help is always available in your preferred language.
Commitment to Zero Fees and Upward Mobility
Comun stands out not only for offering zero fees for account opening, monthly maintenance or minimum balances, but also for its commitment to helping its users move up the financial ladder. Comun acts as a financial partner, supporting financial transactions without the burden of excessive fees. This commitment aligns with the goal of enabling upward mobility for immigrants, who contribute significantly to the U.S. economy.
Customized Features and Benefits
Comun goes beyond traditional financial services by offering features designed to meet the unique needs of the immigrant community. Users can send money abroad with low or no fees, deposit cash at more than 88,000 locations nationwide, including free ATM withdrawals, and connect their accounts to popular payment apps such as Zelle, CashApp and Venmo. Comun's platform also allows customers to receive their paychecks up to two days early through direct deposit, further enhancing their financial flexibility and stability.
Conclusion
Comun is not just a financial services provider, but a platform dedicated to transforming the banking experience for immigrants in the U.S. With its user-focused design, commitment to financial freedom and robust features, Comun is destined to become a vital tool for achieving financial stability and growth for its users. Whether you are looking to manage your daily finances or send money to loved ones abroad quickly and securely, Comun offers a reliable, inclusive and efficient banking solution.
Foundational Moment: Did you know?
Founded by entrepreneurs Mark Selcow and Andres Santos in New York, Comun was built to empower families and enable upward mobility, particularly for the immigrant family. The company has garnered significant investment from prominent firms such as Costanoa Ventures, FJ Labs and South Park Commons, underscoring the tremendous opportunity to serve the financial needs of immigrant families and improve the lives of every individual.

Instant payments
Safe and fast ways to send money without a bank account
8 min de lectura
Did you know it is possible to send money without having a bank account? The lack of access to financial services is a problem that negatively affects the quality of life of thousands of immigrant workers in the United States.
For example, according to a recent survey, the rate of the Latino community in the United States without a bank account dropped from 15% to 10% over the last two years. However, it remains high compared to the national average of 4.5%.
While having a bank account facilitates financial transactions such as transfers, in-store payments, and online purchases, there are now alternatives that allow you to access banking services without needing an account.
Below, you will discover how to transfer money from one card to another without an app or bank account, as well as the safest and simplest methods available to you.
Sending Money Online
Not having a U.S. bank account is not an obstacle to sending money domestically or internationally, as there are methods widely used among immigrant workers who regularly send remittances and conduct other transactions using prepaid cards and cash payments.
International Money Transfer Providers
This is one of the most popular ways to send money without a bank account due to the accessibility, variety of payment methods, and broad coverage typically offered.
International money transfer providers are companies that specialize in facilitating money transfers from one country to another. The key features of these services include:
- Specialization in international money transfers, unlike traditional banks, which have certain limitations, such as high commissions, unfavorable exchange rates, extensive delivery time, and participation of intermediaries that increase costs.
- More affordable fees.
- Various sending methods.
- Multiple Money Transfers Locations
How to Send Money Without a Bank Account Through an International Transfer Platform
Comun allows you to send money to your loved ones for a modest transfer fee starting at USD 2.99 up to the applicable limits. It is very simple; just follow these steps:
1. Open your account with Comun; it will only take a few minutes!
2. Choose the most convenient delivery method for your recipient, such as cash pick up at a physical store like Oxxo, Grupo Elektra, 7 Eleven, and more.
3. You may also send money directly to a bank and have it picked up at one of its branches.
4. Track the delivery directly in your Comun mobile application.
Comun is an excellent option for our community, as it provides Spanish-language service, which is highly appreciated by the immigrant community. Open your account today and start sending money without complications.
What Information Do You Need to Send Money Without a Bank Account?
To send money without a bank account, you only need the following information about your recipient:
- Full name of the recipient, exactly as it appears on their official ID.
- Recipient’s phone number.
- If the transfer is made to a bank account, you will also need:
- Recipient’s address.
- Bank account number, depending on the receiving country.
P2P Services
P2P (peer-to-peer or person-to-person) services allow immediate money transfers between individuals without intermediaries. These options are useful for everyday needs such as paying rent, shared services, splitting transportation costs, and sending money to your relatives in the US or internationally.
How to Send Money Without a Card Using P2P Services
- Choose a reliable provider, such as Cash App or Venmo.
- Enter the recipient’s phone number in the mobile app.
- Confirm the transaction and track it.
Sending Money by Mail
Other alternatives involve sending a cashier’s check, a certified check, or a money order through the postal service.
Cashier’s Check
This type of check is issued with the bank’s funds. The customer must pay in cash or directly from their account, and the check is made payable to the recipient.
Certified Check
This check is issued using the customer’s funds. The issuer must have a bank account so that the bank can verify the availability of funds. The recipient may cash the check directly at a bank branch.
Money Order
Another way to send money without a bank account is by using a money order, which is a type of prepaid payment order. To do so, you will need to:
1. Go to a post office or authorized retailer, such as USPS or Walmart, to purchase a money order.
2. Write the beneficiary’s name in the “pay to the order of” section.
3. Write your name in the “purchaser” section.
4. Sign in the space designated for the purchaser, generally on the front of the document.
5. Keep the receipt with the serial number.
6. Pay the amount to be sent plus applicable service fee.
7. Send the money order via regular or certified mail.
8. Write the recipient’s address in the center of the envelope and the sender’s address in the upper left corner.
9. Purchase a postage stamp at the post office and attach it to the envelope.
10. Drop off the envelope at the post office.
The recipient may cash the money order at an authorized branch upon presenting valid personal identification.
The downside of this alternative is that it takes longer to arrive, as it relies on a traditional mailing method.
Sending Money With Prepaid Load
There are other options available to send money without a bank account, such as prepaid cards and mobile applications.
Reloadable Prepaid Cards
Reloadable prepaid cards function similarly to debit cards, with the main difference being that they are not linked to a bank account. They also allow you to pay for services and make online purchases.
To send money using a prepaid card, you only need to:
1. Identify an international money transfer service that supports prepaid cards, such as Western Union or MoneyGram.
2. Select your preferred provider and choose the prepaid card option on their website.
3. Enter the recipient’s information, making sure it is compatible with the selected platform.
4. Confirm the transfer and pay the amount plus the applicable service fee.
Done! The recipient will receive the money on the prepaid card as if it were a bank transfer.
Mobile Wallets/Applications
Lastly, you may opt for mobile wallets or applications that offer money transfer capabilities. Some examples include Cash App, Venmo, and Remitly, which provide access to an mobile app you can use to send and receive money.
These applications do not require a bank account and are user-friendly. Some also offer physical cards that function similarly to debit cards.
7 Essential Tips for Sending Money Without a Bank Account
1. Verify the Identity and Information of the Recipient
Ensure that the recipient’s information, such as name, account number, or phone number, is entered correctly. Any discrepancies could prevent the recipient from collecting the funds.
2. Compare Fees and Exchange Rates
Each provider has its own rates depending on the receiving country, amount, and exchange rate. Remember, with Comun you do not pay excessive fees, and you ensure your family receives more for less.
3. Know the Sending Limits
Some platforms have sending limits that should be considered before selecting a service. For instance, Western Union has a daily limit of USD 7,499, while Cash App allows up to USD 7,500 per week for verified accounts.
4. Keep All Receipts and Reference Numbers
Even though these methods are secure, it is important to keep receipts and reference numbers in case a clarification or issue arises.
5. Use Reputable and Secure Services
It is essential to ensure that you use a trusted service. Check online reviews and verify that the provider has an official website and/or physical offices.
6. Be Cautious of Scams
Unfortunately, scams are common around financial services. No legitimate institution will request passwords or verification data. Always access official websites. If in doubt, visit an authorized branch.
7. Consider Delivery Time
Most options allow you to complete transfers in minutes, but some may take several days. Consider this before choosing your preferred service.
Frequently Asked Questions
Is it safe to send money without a bank account?
Absolutely. Comun is backed by leading financial institutions to protect your funds up to the applicable limits. Additionally, you can track your transfer directly through the Comun mobile app.
How much does it cost to send money without a bank account?
Comun offers a transfer fee starting at USD 2.99, regardless of the amount you send up to the applicable limits. Your first transfer is commission-free!
How long does it take for the money to arrive?
Cash is typically available within approximately 1 hour at the selected store or bank branch.
What documents do I need to send/receive money without an account?
You need the full name of your recipient, and they must present official identification.
Financial Education
The Future of Banking Services: Trends to Watch
8 min de lectura
What Today's Banking Customers Want
Today's banking consumers are no longer satisfied with just basic financial transactions. They want seamless digital experiences, personalized services, and round-the-clock accessibility. With the spread of smartphones and internet connectivity, customers expect banking services to be available at their fingertips, anytime and anywhere. They also demand transparency, security, and efficiency in every interaction with their financial institutions.
Understanding and meeting these changing needs is crucial for banks to attract and retain new customers in an increasingly competitive landscape.
Better Experiences Are Essential for Deposit Growth and Customer Loyalty
In an era where switching banks is easier than ever, delivering a superior customer experience has become essential for deposit growth and maintaining customer loyalty. Banks that prioritize user-friendly interfaces, intuitive mobile apps, and responsive customer support are more likely to succeed in building solutions integrated with customer data. Beyond the transactional aspect, customers value proactive financial advice, personalized product recommendations, and tailored communication.
By investing in emerging technologies that improve customer experiences, many banks can build stronger relationships with their customers and position themselves as trusted financial organizations for the long term.
Technological and Industry Shifts
In banking, the traditional advantages that once set institutions apart are gradually eroding. With the rise of fintech startups and tech giants entering the financial services space, banks face unprecedented competition. Legacy systems and processes that used to be barriers to entry are now being disrupted by innovative technologies and agile business models.
Banking Designed for Your Life in the USA
Open your bank account¹ in 3 minutes with your country's ID²
Banking Is Losing Its Traditional Advantages
Historically, banks held monopolies on financial services due to their physical presence, regulatory barriers, and established customer trust. However, the arrival of digital banking and the spread of online-only banks have challenged this status quo. Traditional advantages like branch networks and long-standing reputations are no longer as significant in a digital era where convenience and efficiency come first.
Technological Advances Shaping the Banking Industry
Technological advances are driving profound change in the banking industry, redefining how financial services are delivered and consumed. From artificial intelligence (AI) and machine learning to blockchain and cloud computing, banks are leveraging cutting-edge technologies to streamline operations, improve security, and improve customer experiences.
AI and Data Advances Accelerating Transformation Possibilities
AI and data analytics are revolutionizing banking by letting institutions gain deeper insight into customer behavior, automate repetitive tasks, and personalize offers at scale. Chatbots powered by natural language processing (NLP) provide instant customer support, while predictive analytics algorithms help identify trends and proactively mitigate risk.
Seamless Technology and Platform Integration Is a Top Priority
Seamless technology and platform integration is essential for banks to deliver cohesive, omnichannel experiences to their customers. Whether through mobile banking apps, online banking portals, or in-branch interactions, customers expect consistent, intuitive interfaces that smoothly meet their financial needs across various touchpoints.
[Video embed — keep as-is: https://www.youtube.com/watch?v=V4FKKe5Zs2A]
Embracing Responsible AI (GenAI)
As banks adopt AI and automation, it's crucial to do so responsibly, considering ethical implications and potential biases. Responsible AI, often called GenAI, involves ensuring fairness, transparency, and accountability in AI-driven decision-making processes. By adopting ethical AI frameworks and governance principles, banks can build trust with customers and mitigate risks associated with AI deployment.
Innovations in AI and data analysis are driving transformative possibilities, while seamless technology and platform integration is now a top priority. Banks must also embrace responsible Generative AI (GenAI) to stay ahead.
Banking as a Service (BaaS)
As traditional banking models evolve, Banking as a Service (BaaS) is emerging as a key trend reshaping the financial landscape. This section explores the key aspects of BaaS, from emerging industry trends to competitive arenas and business models, offering insight into the future of banking.
Emerging Trends in the BaaS Banking Industry
- Collaboration Over Competition: Traditional banks are increasingly partnering with fintech startups and third-party providers to offer specialized financial services. This collaborative approach lets banks leverage innovative technologies and expand their service offerings without needing extensive infrastructure investment.
- API-Driven Ecosystems: Application Programming Interfaces (APIs) play a central role in BaaS, enabling seamless integration of banking services into third-party apps and platforms. Open banking initiatives around the world are driving the adoption of standardized APIs, fostering a more interconnected financial ecosystem.
- Platformization of Banking: Banking services are shifting from product-centric models to platform-centric models, where banks act as enablers of financial transactions rather than just service providers. Platforms offer a diverse range of financial products and services curated from multiple providers, giving customers greater choice and flexibility.
Competitive Arenas and Emerging Business Models in Banking
- Digital Challenger Banks: Digital-only banks, or challenger banks, are disrupting the traditional banking landscape with their agile operations, innovative products, and customer-first approach. These agile startups leverage technology to deliver superior user experiences and challenge incumbents in key market segments. Such is the case with the Común app, which offers financial services for immigrants living in the U.S.
- Embedded Finance: Embedded finance refers to integrating financial services into non-financial apps, like e-commerce platforms, ride-share apps, and social networks. By embedding banking functionality directly into everyday activities, financial transactions become seamless and frictionless for users.
Banking Designed for Your Life in the USA
Open your bank account¹ in 3 minutes with your country's ID²
A Look at the Bigger Picture: Everyday Banking
- Mobile-First Solutions: Everyday banking is increasingly mobile-centric, with customers preferring the convenience of managing their finances on the go. Mobile banking apps offer a wide range of features, including account management, bill payments, peer-to-peer transfers, and financial insights, meeting customers' diverse needs.
- Personalization and Predictive Analytics: Banks are leveraging data analytics and AI algorithms to personalize their offerings and anticipate customer needs. By analyzing transactional data and behavioral patterns, banks can deliver personalized product recommendations, tailored financial advice, and proactive alerts, improving customer engagement and satisfaction.
Discover the Future of Banking: Embrace BaaS Innovations Today for Financial Evolution and Empowerment
- Enhanced Customer Experiences: BaaS lets banks deliver enhanced customer experiences by leveraging innovative technologies and partnerships. From frictionless onboarding experiences to personalized financial solutions, BaaS empowers customers to reach their financial goals more effectively.
- Financial Inclusion and Accessibility: BaaS has the potential to drive financial inclusion by extending banking services to underserved and unbanked populations. Through partnerships with fintechs and leveraging digital channels, banks can reach previously inaccessible markets and provide essential financial services to those who need them.
- Agility and Innovation: Embracing BaaS lets banks innovate quickly and adapt to changing market dynamics. By leveraging outside expertise and resources, banks can accelerate the development and rollout of new products and services, stay ahead of the competition, and meet changing customer expectations.
Everyday banking remains the biggest arena, and the future of banking will see financial evolution and empowerment through BaaS innovations.
Regulatory and Compliance Considerations
This section explores the imperative nature of investing in regulatory compliance, the importance of anticipating regulatory action, and the impact of regulatory developments on BaaS. It also discusses predictions for the future of BaaS in light of these regulatory considerations.
Investing in Regulatory Compliance Is Imperative
- Compliance Frameworks: Banks and BaaS providers must establish robust compliance frameworks to adhere to regulatory requirements and industry standards. This includes implementing Know Your Customer (KYC) procedures, anti-money laundering (AML) measures, and data protection protocols to safeguard customer information and mitigate financial risks.
- Risk Management: Investing in risk management practices is essential to navigate regulatory complexities and protect against potential threats. By conducting regular risk assessments and implementing risk mitigation strategies, banks can ensure regulatory compliance while maintaining operational resilience.
Anticipating Regulatory Action
- Proactive Compliance Measures: Anticipating regulatory action lets banks stay ahead of compliance requirements and mitigate regulatory risks effectively. By closely monitoring regulatory developments, engaging with regulatory authorities, and participating in industry forums, banks can proactively address emerging regulatory challenges and adapt their compliance strategies accordingly.
- Regulatory Engagement: Establishing open communication channels with regulatory authorities fosters collaboration and transparency, letting banks address regulatory concerns and seek guidance on compliance matters. By actively engaging with regulators, banks can demonstrate their commitment to regulatory compliance and build trust within the regulatory community.
Regulatory Developments Impacting BaaS
- Global Regulatory Landscape: Regulatory developments, like open banking initiatives and data protection regulations, have a significant impact on the BaaS ecosystem. Financial service providers must stay on top of regulatory changes across different jurisdictions and adapt their operations accordingly to ensure compliance with local laws and regulations.
- Compliance Challenges: Regulatory requirements related to data privacy, cybersecurity, and consumer protection pose significant challenges for BaaS providers. Meeting complex regulatory frameworks requires substantial investment in resources and expertise, demanding a proactive approach to effectively address regulatory concerns.
Banking Designed for Your Life in the USA
Open your bank account¹ in 3 minutes with your country's ID²
Predictions for the Future of BaaS
- Regulatory Evolution: The future of BaaS is expected to be shaped by ongoing regulatory evolution, with regulators adapting existing frameworks to address emerging risks and challenges. Predictions suggest regulators will focus on improving consumer protection, promoting market competition, and fostering innovation within the BaaS ecosystem.
- Regulatory Harmonization: As the BaaS landscape continues to evolve, there's a growing need for regulatory harmonization across different jurisdictions to facilitate cross-border operations and ensure a level playing field for market participants. Predictions indicate regulators will collaborate to standardize regulatory requirements and promote interoperability within the BaaS ecosystem.
- Compliance Innovation: Innovations in regulatory technology (RegTech) are expected to play a significant role in driving compliance innovation within the BaaS industry. Predictions suggest BaaS providers will leverage RegTech solutions to automate compliance processes, improve regulatory reporting capabilities, and enhance overall regulatory efficiency.
Investing in regulatory compliance is crucial, since regulatory actions and developments significantly impact BaaS. Predicting future regulatory landscapes helps institutions stay prepared and compliant.
Conclusion
The future of banking services is marked by technological innovation, shifting customer preferences, and evolving regulations. Banking as a Service (BaaS) is reshaping the industry, offering new avenues for collaboration and innovation. Embracing BaaS today unlocks new opportunities to improve customer experiences and drive economic growth.
Regulatory compliance is crucial. Banks must invest in compliance frameworks and anticipate regulatory changes to mitigate risks effectively. Looking ahead, success in banking will depend on agility, innovation, and customer focus. By staying on top of trends, leveraging technology, and prioritizing compliance, banks can thrive in the digital era.

Community
What You Need to Open an Account at Común¹
8 min de lectura
Unmatched Ease of Opening an Account
Opening a checking account with Común is simple and hassle-free, addressing the barriers to financial exclusion typically faced by the immigrant community. Accepting over 100 forms of identification², including social security numbers from Latin American countries, Común ensures that immigrants have access to essential banking services. The application process is quick, taking less than 5 minutes, and is free of additional or hidden fees, minimum balance requirements or monthly commissions. This inclusiveness is central to Común's mission of fostering financial stability and growth.
Mobile Deposit Options
Común: Común offers a convenient mobile deposit feature that allows users to deposit cash at more than 88,000 locations in the United States, including major retailers such as Walgreens, Dollar General and Walmart. This extensive network ensures that users can easily find a deposit location near them, making the process of adding money to their accounts simple and hassle-free.
Traditional Banking: Although many traditional banks offer mobile deposit options, they often restrict these to check deposits through a mobile app. Cash deposits typically require a visit to an ATM or bank branch, which can be less convenient and more time-consuming than Común's extensive cash deposit network.
Utility in Today's World: In today's fast-paced environment, the flexibility to deposit cash in a wide range of accessible locations is invaluable, especially for individuals who may not have easy access to traditional banking services or who work non-traditional hours when banks are closed.
International Remittances
Común: Común excels in facilitating international remittances⁴, allowing users to send money abroad quickly and with lower fees compared to many traditional banks and remittance services. The process is enhanced with real-time notifications, keeping the sender informed from the moment the money is sent until it is received.
Traditional Banking: Traditional banks generally offer international transfer services, but these can be expensive and slow, with transfers sometimes taking several days to complete. In addition, the fees associated with traditional bank remittances can be significantly higher.
Usefulness in Today's World: In a globalized economy, the ability to send money across borders quickly and affordably is crucial. Many families rely on remittances for financial support, and businesses need efficient ways to handle international transactions. Común's streamlined and cost-effective service effectively meets these modern demands.
Advance Salary Access
Común: Común offers the ability to connect wages to the application and receive payment up to two days in advance³. This feature incurs no additional fees, providing significant relief during financial emergencies or when planning ahead.
Traditional Banking: Some traditional banks have begun to offer similar features, but they are often tied to specific types of accounts or require a minimum balance. The accessibility and ease of use of early access to Común's salary is not always matched in traditional environments.
Usefulness in Today's World: With the rise of gig economy jobs and irregular pay schedules, having early access to wages can provide a buffer against financial instability. This feature is particularly valuable for those living paycheck to paycheck, offering a cushion that can help avoid overdraft fees and late payments.
Unlike traditional banking institutions, Común's innovative features are designed to meet the needs of today's diverse and mobile population, particularly benefiting the immigrant community in the U.S. By providing services that offer greater convenience, lower costs and greater accessibility, Común not only addresses common challenges faced by its users, but also empowers them toward greater financial freedom and stability. As we move toward a more interconnected and fast-paced world, the importance of responsive and inclusive financial services continues to grow, something Común is uniquely positioned to offer.

Robust Security and Customer Support
Security and customer support are paramount at Común. With FDIC-insured accounts and Visa protection on virtual Visa debit card transactions, Común customers can manage their funds with confidence. Innovative security features such as biometric logins and instant transaction notifications keep your money safe. In addition, Común offers 24/7 customer support in English and Spanish, ensuring that help is always available in your preferred language.
Commitment to Zero Fees and Upward Mobility
Común stands out not only for offering zero fees for account opening, monthly maintenance or minimum balances, but also for its commitment to helping its users move up the financial ladder. Común acts as a financial partner, supporting financial transactions without the burden of excessive fees. This commitment aligns with the goal of enabling upward mobility for immigrants, who contribute significantly to the U.S. economy.
Customized Features and Benefits
Común goes beyond traditional financial services by offering features designed to meet the unique needs of the immigrant community. Users can send money abroad with low or no fees, deposit cash at more than 88,000 locations nationwide, including free ATM withdrawals, and connect their accounts to popular payment apps such as CashApp and Venmo. Comun's platform also allows customers to receive their paychecks up to two days early through direct deposit, further enhancing their financial flexibility and stability.
Conclusion
Común is not just a financial services provider, but a platform dedicated to transforming the banking experience for immigrants in the U.S. With its user-focused design, commitment to financial freedom and robust features, Común is destined to become a vital tool for achieving financial stability and growth for its users. Whether you are looking to manage your daily finances or send money to loved ones abroad quickly and securely, Común offers a reliable, inclusive and efficient banking solution.
Foundational Moment: Did you know?
Founded by entrepreneurs Mark Selcow and Andres Santos in New York, Común was built to empower families and enable upward mobility, particularly for the immigrant family. The company has garnered significant investment from prominent firms such as Costanoa Ventures, FJ Labs and South Park Commons, underscoring the tremendous opportunity to serve the financial needs of immigrant families and improve the lives of every individual.
Immigration
H-1B visa: what it is, requirements, and process explained for immigrants
8 min de lectura
Finding a path that gives you job opportunities in the United States can be hard work, especially if you’re unfamiliar with the different visa types offered by the U.S. government.
The H-1B visa is an option that could open the door to a new life in the U.S. In this guide, we explain what it is, what it’s for, who can apply, when it applies, and its benefits and limitations.
It’s essential to understand this visa’s features—as well as how it differs from other work visas—so you can ensure it fits your professional goals in the country.
With this information, you’ll be able to plan a strategy to obtain the visa and fully establish yourself in the United States.
What is the H-1B visa in the United States?
The H-1B visa is authorization granted to foreign workers to temporarily perform specialty occupations that generally require specialized knowledge and prior experience.
It is a nonimmigrant visa with an initial duration of 3 years and, in most cases, can be extended up to a maximum of 6 years.
There are exceptions, such as when the temporary worker is in the process of obtaining permanent residence, in which case the visa may be extended for a longer period.
4 main requirements to obtain the H-1B visa
Before starting the immigration process, you should know the H-1B requirements and verify that your background aligns with them to determine eligibility.
1. Minimum education level
To obtain an H-1B visa, you must have a higher education degree or its U.S. equivalent. The job offer must also be related to the specialty area of the degree presented.
2. Job offer from a U.S. employer
As with the EB-3 visa, the H-1B also requires a job offer from a U.S. employer, who must file Form I-129 with USCIS.
3. Common professions where it applies
Keep in mind that this visa is used for jobs requiring specialized knowledge, and openings most often arise in the following areas:
- Various branches of engineering.
- Information technology, such as programming, software development, etc.
- Sciences, such as chemistry, biology, and physics.
- Healthcare.
- Finance, economics, and accounting.
- Architecture, mathematics, and technical fields.
4. Annual visa cap and the lottery process.
Another key point is that this visa has an annual issuance cap, divided as follows:
- Regular H-1B: 65,000 per fiscal year.
- Advanced degree exemption: more than 20,000 for U.S. master’s and doctoral degrees.
Because filings often exceed these limits, USCIS established a selection system consisting of electronic registration and a random lottery.
The draw occurs in two phases: first the 65,000 regular slots are selected, and then 20,000 additional slots are drawn for U.S. advanced degree holders.
Between March and April, employers receive notification of the lottery results. If not selected, you may wait for a second round if quotas aren’t filled or, otherwise, apply the following year.
What is the H-1B application process?
Below is how the H-1B application process works.
1. Register in USCIS’s system
First, the U.S. employer must register the candidate on USCIS’s official site during the designated window, generally in March. The registration fee—listed on the same site—must also be paid.
If the candidate is selected, the employer receives a USCIS notice and can proceed to the next stage.
Note that before filing with USCIS, the employer must obtain a certified Labor Condition Application (LCA) from the Department of Labor (DOL).
2. Employer files the petition
After selection, the employer has 90 days to file Form I-129, Petition for a Nonimmigrant Worker, along with required documentation.
At this stage, it’s necessary to show the position is a specialty occupation and that the candidate meets the requirements.
3. USCIS review and approval
USCIS reviews the filing and, if needed, issues a Request for Evidence to seek additional information or clarification.
If everything is in order, the employer receives an approval notice, and the candidate proceeds with consular processing or a change-of-status request.
4. Consular processing or change of status
If the candidate is outside the U.S., they must attend a U.S. consulate, complete Form DS-160, and appear for a consular interview.
If the candidate is already in the U.S. under another status, the employer files the H-1B petition indicating the worker is in the United States.
In both cases, USCIS approval is required before visa issuance can proceed.
Benefits and limitations of the H-1B visa
H-1B holders enjoy several benefits that can improve their lives and those of their families; however, it’s also important to note the limitations.
Benefits
Lawful work in the United States
Although temporary, the H-1B allows you to work legally in the United States in your field of specialty. This can open many doors and strengthen your professional experience.
Potential path to permanent residence
H-1B workers may later pursue permanent residence (a Green Card) and extend benefits to immediate family members such as a spouse and unmarried children under 21.
Limitations
Maximum duration of 6 years
As noted, this visa does not automatically confer permanent residence; it lasts a maximum of 6 years. Still, it can be a first step toward it.
Employer dependency
This visa depends entirely on the employer extending the job offer and completing the filing process.
Annual cap
The visa is numerically capped, and filings typically exceed the annual cap, reducing the likelihood of selection.
To prevent these limits from becoming obstacles, consider planning ahead if you intend to pursue permanent residence. You can also evaluate other work visas, such as EB-2 and EB-3, which may be more suitable for long-term plans in the United States.
Take the next step on your immigration path with Común
Here we covered how to file for the H-1B visa, the requirements, benefits, limitations, and who it’s ideal for.
When you arrive in the United States, you’ll need an ally to help you manage your finances easily. Meet Común!
- Debit card for everyday purchases and payments.
- Fast money transfers to your home country.
- Secure payment options.
Open your Común account today and manage your money in the U.S.
Frequently asked questions
How do I go from H-1B to a Green Card?
Your employer must sponsor permanent residence under an employment-based category, file PERM with the DOL, and then file Form I-140.
How long does the H-1B last?
A maximum of 6 years.
How much does an H-1B visa cost?
Form I-129: from $460 to $780.
An anti-fraud fee may apply.
Living in the United States
How to Buy a House in the United States as an Immigrant: Everything You Need to Know
8 min de lectura
Buying a house in the U.S. is a process that is not legally restricted for the immigrant population. However, it is more complicated for this group due to certain specific requirements requested.
According to a recent article, obtaining financing is more difficult for immigrants due to obstacles such as lack of credit history, immigration status, and the need to have an SSN or ITIN.
If you plan to live in the United States and believe you are far from meeting the necessary requirements to buy a house there, below we present the complete guide so you can acquire a property for the first time.
Is It Possible to Buy a House in the United States as a Foreigner?
Unlike several Latin American countries, in the USA it is possible to acquire a property without being a U.S. citizen, as long as a series of requirements are met to carry out the purchase process.
This process is completely legal and increasingly common, as it is possible with good financial preparation and the necessary documentation. According to Realtor, during 2024 more than 43,700 homes were acquired by immigrants. This confirms the viability of the transaction.
Although it is not necessary to have citizenship or permanent residence to buy a house, it is true that immigration status and the fulfillment of other requirements can influence the steps to access mortgage loans and other financing options.
Requirements to Buy a House in the United States
The first step in buying real estate in the United States is to gather the requested documentation and have the financial solvency needed to cover the price of the property.
Identity Documents
These are the essential documents you must gather before buying a house.
Passport
You must present your valid passport and visa as primary identifications that will serve to validate your identity.
Tax Identification Number
Generally, lenders request the SSN, but if you do not have one, it is also possible to present the ITIN.
Financial Preparation
If you have the price of the property in cash, it will be much easier to complete the purchase process. Otherwise, you must undertake the appropriate financial preparation to access financing programs suitable for you.
This is the step-by-step process we recommend you follow to ensure you can cover the installments of your first house in the United States.
Proof of Income
It is essential that you can prove stable income to obtain a mortgage, since lenders want to ensure that applicants are able to cover monthly installments and other payments associated with the purchase of a property.
Immigrants have the option of presenting documents issued inside and outside the country, but they must be translated and certified.
Employment Letters
An employment letter issued by the employer is a common way to prove income.
This document must include:
- Company name and contact details
- Applicant’s position
- Date of entry into the company
- Annual or hourly salary
- Signature and position of the issuer
Banking Account
The lender may also request bank statements from the last 3 months to verify steady income consistent with the declared salary. In addition, they evaluate the existence of overdrafts and the applicant’s savings capacity.
Funds Available for Down Payment and Closing
It is essential that you demonstrate solvency to cover the following payments.
- Down payment: ranges from 3% to 20% of the property value, depending on the type of loan
- Closing costs: notary fees, insurance, and loan fees
7 Steps to Buy a House in the United States
Step 1: Research the real estate market and define where you would like to buy
Before choosing a property, research the real estate market, the average price in each area, and access to basic services in the neighborhood of your interest. States like Texas are characterized by an 18% lower cost of living than the national average and a high presence of the immigrant community.
Below we show you a comparative table of the range of housing prices in different cities, according to Zillow.
Price table
| States / cities | Apartment | House |
|---|---|---|
| New York | 94,000 - 110,000,000 USD | 250,000 - 70,000,000 USD |
| Florida | 145,000 - 85,000,000 USD | 40,000 - 285,000,000 USD |
| Texas | 20,000 - 17,000,000 USD | 20,000 - 64,000,000 USD |
| Los Ángeles | 250,000 - 20,500,000 USD | 115,000 - 177,000,000 USD |
Step 2: Calculate How Much You Can Spend and Set Your Budget
It is very important that you carry out an analysis of your payment capacity, according to your income and monthly expenses.
Calculate how much money you spend per month and whether you will be able to cover the corresponding installments with the remaining money, as well as the amount you have saved at the moment.
Step 3: Choose a Real Estate Agent with Experience in International Clients
A real estate agent with experience in international clients will be of great help in streamlining the process, as they know well the special requirements as well as the most common barriers faced by immigrants. In addition, the real estate agent can help you with negotiation and with comparing housing prices.
Step 4: Request a Mortgage Pre-Approval if You Plan to Finance the Purchase
It is not mandatory to request mortgage pre-approval, although it does offer you certain benefits, such as greater solidity when presenting an offer, in addition to showing you the amount the bank could lend you.
Step 5: Visit Properties and Make a Formal Offer for the One You Are Interested In
Once you find a property ideal for your lifestyle, your real estate agent must prepare a formal written offer, which can be accepted, rejected, or renegotiated by the owner.
Generally, a guarantee deposit is delivered to endorse the purchase commitment.
Step 6: Carry Out the Inspection and Professional Appraisal of the Property
The inspection is vital to detect structural problems that affect the value of the house and to carry out the official appraisal that will be confirmed by the bank.
Step 7: Sign the Documents and Make the Final Payment at Closing
On the long-awaited closing day, you must sign a series of documents and carry out the following procedures:
- Mortgage signing, if applicable
- Signing of the property transfer
- Transfer of down payment and closing costs
- Registration of deeds in your name
Welcome to your new home!
Discover How Much It Costs to Buy a House in the United States
One of the most common mistakes of first-time buyers is calculating long-term payments based on the listed price, without considering the additional costs of the U.S. real estate market, such as:
Additional Costs to Consider
- Property taxes
- Home insurance
- Closing costs
Practical Tips for a Safe Purchase
Buying a house is a very important decision, which is why we recommend taking the necessary time to research and review all the details of the transaction.
In addition, it is advisable to have a banking account with real-time notifications and support in your language. This will help you better manage your finances and verify your income.
Común Helps You Prepare to Buy Your House in the United States
As you can see, buying a home in the United States is completely viable for immigrants, as long as they have the correct information, the support of experienced professionals, and proper financial planning.
Opening a banking account brings you closer to fulfilling the American dream, since it allows you to safely receive your salary and verify your income in the country.
Open your account today at Común with a qualifying official ID from your country of origin, organize your finances, and take the first step toward your new home.
Instant payments
Direct deposit vs wire transfer: comparison guide for U.S. immigrants
8 min de lectura
Direct deposit vs wire transfer: comparison guide for U.S. immigrants
These payment methods are both available in the U.S. but they are often used for different purposes. Direct deposit is commonly used for paychecks, tax refunds, and government benefits, while wire transfers are more often used for urgent or high-value transfers between financial institutions.
Understanding the difference between direct deposit and wire transfers can help you avoid unnecessary fees, choose the right payment method for your situation, and manage your money more confidently.
What's the difference between direct deposit and wire transfer?
The biggest difference is the purpose they serve. Direct deposit is commonly used for recurring payments such as salaries, benefits, and tax refunds. Wire transfers are commonly used to move money quickly between financial institutions, particularly for large or time-sensitive transactions.
| Feature | Direct deposit | Wire transfer |
|---|---|---|
| Common use | Paychecks, benefits, tax refunds | Large or urgent transfers |
| Network used | ACH network | Wire transfer network |
| Speed | Typically 1–3 business days | Often same day or next business day |
| Typical cost | Often no fee to receive | Fees may apply |
| International transfers | Limited | Commonly used |
| Recurring payments | Yes | Less common |
| Setup required | Routing + account number | Bank details + recipient information |
How direct deposit works
Direct deposit is one of the most common payment methods in the United States, particularly for employees receiving wages from an employer. Instead of issuing a paper check, an employer sends the payment electronically to the employee's bank account through the ACH network.
To set up direct deposit you need to provide your employer: your bank's routing number and your personal account number.
How wire transfer works
A wire transfer is an electronic transfer of funds between financial institutions through secure financial networks like Fedwire or SWIFT. Unlike direct deposit, wire transfers are better suited for large one-time payments, urgent payments, real estate transactions, or international transfers.
When to use each one
Use direct deposit for:
- Receiving your paycheck
- IRS tax refunds
- Social security or unemployment benefits
- Recurring business payments
Use wire transfer for:
- Real estate payments (down payment, closing)
- Urgent international transfers
- High-value business payments
- When the recipient specifically requires a wire transfer
How to set up direct deposit with Común
With your Común account, you can set up direct deposit by providing your Común routing number and account number to your employer. Your Común account has unique routing and account numbers available in the app. Visit comun.app to learn more.
FAQ
Is direct deposit faster than wire transfer?
Not necessarily. Domestic wire transfers can be faster (same day), while direct deposits usually take 1-3 business days. However, many accounts offer early access to direct deposits up to 2 days early.
How much does it cost to set up direct deposit?
Setting up direct deposit is generally no fee. Employers use the ACH network to send payroll electronically at no charge to the employee.
Común is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank, Member FDIC.
Immigration
ITIN vs. SSN: What's the Difference and Why Does It Matter?
8 min de lectura
What Is an SSN?
A Social Security Number (SSN) is a unique nine-digit code assigned by the U.S. Social Security Administration (SSA) to citizens, permanent residents, and certain eligible temporary residents. Originally designed to manage Social Security benefits, the SSN is now widely used for tax filing, credit history, and access to government services.
People must submit their SSN application to the address provided by the Social Security Administration.
Key facts about SSNs:
- Eligibility: U.S. citizens, permanent residents, and certain non-citizens authorized to work are eligible for an SSN.
- Uses: SSNs are used for employment, tax filing, Social Security benefits, and access to government services.
- Financial access: SSNs are often required to open bank accounts, apply for credit, and get loans.
An Individual Taxpayer Identification Number (ITIN) is also a nine-digit number, but it's issued by the IRS (Internal Revenue Service) rather than the SSA. People must file Form W-7 to apply for an ITIN. The ITIN is specifically for people who are required to file U.S. tax returns but aren't eligible for an SSN. This includes non-citizens without legal work authorization in the U.S., foreign investors, and dependents of U.S. citizens or residents.
An ITIN is required to file a U.S. tax return and is also used to submit a federal tax return.
Key facts about ITINs:
- Eligibility: ITINs are available to non-citizens who are required to file U.S. taxes but don't qualify for an SSN.
- Uses: ITINs are used solely for tax filing purposes and don't authorize work or provide eligibility for Social Security benefits.
- Financial access: While ITINs can be used to open bank accounts and apply for credit at some institutions, they don't grant the same level of access as an SSN.
Differences Between ITIN and SSN
The main difference between an ITIN and an SSN comes down to who can get them and what they're used for:
- Eligibility:
- SSN: Issued to U.S. citizens, permanent residents, and certain temporary residents authorized to work.
- ITIN: Issued to non-citizens who are required to file taxes but aren't eligible for an SSN. The number of days present in the U.S. affects residency status for tax purposes.
- Purpose:
- SSN: Used for a wide range of activities, including employment, tax filing, and access to Social Security benefits.
- ITIN: Used exclusively for tax filing and reporting by non-citizens without SSNs. An Employer Identification Number (EIN) is used for business entities, estates, and trusts.
- Legal status:
- SSN: Grants work eligibility and access to certain government benefits.
- ITIN: Does not grant work authorization or eligibility for Social Security benefits.
- Access to financial services:
- SSN: Provides broader access to financial services, including easier access to credit, loans, and government benefits.
- ITIN: While it can be used to open bank accounts and access some financial services, options are more limited compared to what's available with an SSN.
ITIN vs. SSN: Why Does the Difference Matter?
Understanding the difference between an ITIN and an SSN matters for several reasons:
- Tax compliance: Knowing which number to use is crucial for filing taxes correctly. Using the wrong identifier can result in errors, penalties, or delays in processing refunds. For U.S. citizens or residents, it's essential to use the correct identifier, such as an SSN or an Adoption Taxpayer Identification Number (ATIN), when an SSN can't be obtained in time for tax filing.
- Access to financial services: The type of tax ID you have can affect your access to banking, credit, and other financial services. For example, some banks and credit unions accept ITINs, while others may require an SSN.
- Employment eligibility: An SSN is required to work legally in the U.S. If you're a non-citizen without work authorization, applying for an SSN can lead to legal complications. In those cases, an ITIN is the appropriate identifier for tax purposes.
- Government benefits: An SSN is required to receive Social Security benefits and other government services, which aren't accessible with an ITIN.
Conclusion
Both the ITIN and the SSN play critical roles in the U.S. financial and tax systems, but they serve different populations and purposes. Understanding the differences between these identifiers is essential for anyone navigating tax filing, financial access, and legal employment in the U.S. Whether you're a U.S. citizen, a non-citizen authorized to work, or a foreign investor, knowing which number you need — and why — can help you avoid potential legal issues and ensure you have the financial access your circumstances require.
Immigration
The 100 Questions about American Citizenship in Spanish
8 min de lectura
The 100 Questions about American Citizenship in Spanish
Reaching the point where you're preparing for the citizenship exam is already a major milestone. It reflects time, effort, and a commitment to building your future in the United States.
In this guide, you'll find the 100 civic questions for the U.S. Citizenship exam provided by the U.S. Citizenship and Immigration Services (USCIS), the government agency that reviews and processes citizenship applications. These are the questions from the civics test, translated into Spanish with their answers and organized by category aimed to support you while you prepare. The exam is administered by USCIS and is oral, not written. You'll be asked up to 10 questions out of the 100.
How does the US citizenship test work?
The U.S. citizenship exam generally consists of two parts, an English test and a civics test. Understanding how each one of them works could make the process feel more manageable. The English evaluation is conducted through an interview, in which an officer evaluates your English language skills through simple speaking, reading, and writing exercises. In the civics portion, the officer asks up to 10 questions out of a list of 100. They are about U.S. history, government, geography and holidays. To pass the test you must answer at least 6 of them correctly. It is important to consider that this entire part of the exam is oral.
If you do not pass a section the first time, you will usually have a second opportunity to retake the failed portion within 60 to 90 days. To start the application for citizenship, you must submit a form called Form N-400, which is the official application for naturalization, and as of 2026, the filing cost is $760, however, fees are subject to change.
Who can take the exam in Spanish?
If you are 65 or older and have been a permanent resident for at least 20 years, you may qualify to take the civics test in Spanish. This special rule, provided by USCIS, is designed to make the process more accessible for long-term residents. In this case, you do not need to study all 100 questions, you only need to study 20 of the 100 questions. In our list we will mark them with an asterisk (*). It is recommended to always consult and review the specific requirements of your own case with the corresponding authorities.
The 100 Official Citizenship Civics Test Questions (with answers in Spanish)
Here you will find the 100 official questions that USCIS may ask you during your citizenship exam, along with their answers in Spanish. However, keep in mind that the actual interview is conducted in English, unless you qualify for an exemption.
Part A: The American government (questions 1-57)
Principles of American Democracy (1–12)
1. What is the supreme law of the land?
- the Constitution
2. What does the Constitution do?
- sets up the government
- defines the government
- protects basic rights of Americans
3. The idea of self-government is in the first three words of the Constitution. What are these words?
- We the People
4. What is an amendment?
- a change (to the Constitution)
- an addition (to the Constitution)
5. What do we call the first ten amendments to the Constitution?
- the Bill of Rights
6. What is one right or freedom from the First Amendment?*
- speech
- religion
- assembly
- press
- petition the government
7. How many amendments does the Constitution have?
- twenty-seven (27)
8. What did the Declaration of Independence do?
- announced our independence (from Great Britain)
- declared our independence (from Great Britain)
- said that the United States is free (from Great Britain)
9. What are two rights in the Declaration of Independence?
- life
- liberty
- pursuit of happiness
10. What is freedom of religion?
- You can practice any religion, or not practice a religion.
11. What is the economic system in the United States?*
- capitalist economy
- market economy
12. What is the "rule of law"?
- Everyone must follow the law.
- Leaders must obey the law.
- Government must obey the law.
- No one is above the law.
System of Government (13–47)
13. Name one branch or part of the government.*
- Congress
- legislative
- President
- executive
- the courts
- judicial
14. What stops one branch of government from becoming too powerful?
- checks and balances
- separation of powers
15. Who is in charge of the executive branch?
- the President
16. Who makes federal laws?
- Congress
- Senate and House (of Representatives)
- (U.S. or national) legislature
17. What are the two parts of the U.S. Congress?*
- the Senate and House (of Representatives)
18. How many U.S. Senators are there?
- one hundred (100)
19. We elect a U.S. Senator for how many years?
- six (6)
20. Who is one of your state's U.S. Senators now?*
- Answers will vary.
- [District of Columbia residents and residents of U.S. territories should answer that D.C. (or the territory where the applicant lives) has no U.S. Senators.]
21. The House of Representatives has how many voting members?
- four hundred thirty-five (435)
22. We elect a U.S. Representative for how many years?
- two (2)
23. Name your U.S. Representative.
- Answers will vary.
- [Residents of territories with nonvoting Delegates or Resident Commissioners may provide the name of that Delegate or Commissioner. Also acceptable is any statement that the territory has no (voting) Representatives in Congress.]
24. Who does a U.S. Senator represent?
- all people of the state
25. Why do some states have more Representatives than other states?
- (because of) the state's population
- (because) they have more people
- (because) some states have more people
26. We elect a President for how many years?
- four (4)
27. In what month do we vote for President?*
- November
28. What is the name of the President of the United States now?*
- Visit uscis.gov/citizenship/testupdates for the name of the President of the United States.
29. What is the name of the Vice President of the United States now?
- Visit uscis.gov/citizenship/testupdates for the name of the Vice President of the United States.
30. If the President can no longer serve, who becomes President?
- the Vice President
31. If both the President and the Vice President can no longer serve, who becomes President?
- the Speaker of the House
32. Who is the Commander in Chief of the military?
- the President
33. Who signs bills to become laws?
- the President
34. Who vetoes bills?
- the President
35. What does the President's Cabinet do?
- advises the President
36. What are two Cabinet-level positions?
- Secretary of Agriculture
- Secretary of Commerce
- Secretary of Defense
- Secretary of Education
- Secretary of Energy
- Secretary of Health and Human Services
- Secretary of Homeland Security
- Secretary of Housing and Urban Development
- Secretary of the Interior
- Secretary of Labor
- Secretary of State
- Secretary of Transportation
- Secretary of the Treasury
- Secretary of Veterans Affairs
- Attorney General
- Vice President
37. What does the judicial branch do?
- reviews laws
- explains laws
- resolves disputes (disagreements)
- decides if a law goes against the Constitution
38. What is the highest court in the United States?
- the Supreme Court
39. How many justices are on the Supreme Court?
- Visit uscis.gov/citizenship/testupdates for the number of justices on the Supreme Court.
40. Who is the Chief Justice of the United States now?
- Visit uscis.gov/citizenship/testupdates for the name of the Chief Justice of the United States.
41. Under our Constitution, some powers belong to the federal government. What is one power of the federal government?
- to print money
- to declare war
- to create an army
- to make treaties
42. Under our Constitution, some powers belong to the states. What is one power of the states?
- provide schooling and education
- provide protection (police)
- provide safety (fire departments)
- give a driver's license
- approve zoning and land use
43. Who is the Governor of your state now?
- Answers will vary. [District of Columbia residents should answer that D.C. does not have a Governor.]
44. What is the capital of your state?*
- Answers will vary. [District of Columbia residents should answer that D.C. is not a state and does not have a capital. Residents of U.S. territories should name the capital of the territory.]
45. What are the two major political parties in the United States?*
- Democratic and Republican
46. What is the political party of the President now?
- Visit uscis.gov/citizenship/testupdates for the political party of the President.
47. What is the name of the Speaker of the House of Representatives now?
- Visit uscis.gov/citizenship/testupdates for the name of the Speaker of the House of Representatives.
Rights and responsibilities (48–57)
48. There are four amendments to the Constitution about who can vote. Describe one of them.
- Citizens eighteen (18) and older (can vote).
- You don't have to pay (a poll tax) to vote.
- Any citizen can vote. (Women and men can vote.)
- A male citizen of any race (can vote).
49. What is one responsibility that is only for United States citizens?*
- serve on a jury
- vote in a federal election
50. Name one right only for United States citizens.
- vote in a federal election
- run for federal office
51. What are two rights of everyone living in the United States?
- freedom of expression
- freedom of speech
- freedom of assembly
- freedom to petition the government
- freedom of religion
- the right to bear arms
52. What do we show loyalty to when we say the Pledge of Allegiance?
- the United States
- the flag
53. What is one promise you make when you become a United States citizen?
- give up loyalty to other countries
- defend the Constitution and laws of the United States
- obey the laws of the United States
- serve in the U.S. military (if needed)
- serve (do important work for) the nation (if needed)
- be loyal to the United States
54. How old do citizens have to be to vote for President?*
- eighteen (18) and older
55. What are two ways that Americans can participate in their democracy?
- vote
- join a political party
- help with a campaign
- join a civic group
- join a community group
- give an elected official your opinion on an issue
- call Senators and Representatives
- publicly support or oppose an issue or policy
- run for office
- write to a newspaper
56. When is the last day you can send in federal income tax forms?*
- April 15
57. When must all men register for the Selective Service?
- at age eighteen (18)
- between eighteen (18) and twenty-six (26)
Part B: American history (questions 58-87)
Colonial Period and Independence
58. What is one reason colonists came to America?
- freedom
- political liberty
- religious freedom
- economic opportunity
- practice their religion
- escape persecution
59. Who lived in America before the Europeans arrived?
- American Indians
- Native Americans
60. What group of people was taken to America and sold as slaves?
- Africans
- people from Africa
61. Why did the colonists fight the British?
- because of high taxes (taxation without representation)
- because the British army stayed in their houses (boarding, quartering)
- because they didn't have self-government
62. Who wrote the Declaration of Independence?
- (Thomas) Jefferson
63. When was the Declaration of Independence adopted?
- July 4, 1776
64. There were 13 original states. Name three.
- New Hampshire
- Massachusetts
- Rhode Island
- Connecticut
- New York
- New Jersey
- Pennsylvania
- Delaware
- Maryland
- Virginia
- North Carolina
- South Carolina
- Georgia
65. What happened at the Constitutional Convention?
- The Constitution was written.
- The Founding Fathers wrote the Constitution.
66. When was the Constitution written?
- 1787
67. The Federalist Papers supported the passage of the U.S. Constitution. Name one of the writers.
- (James) Madison
- (Alexander) Hamilton
- (John) Jay
- Publius
68. What is one thing Benjamin Franklin is famous for?
- U.S. diplomat
- oldest member of the Constitutional Convention
- first Postmaster General of the United States
- writer of "Poor Richard's Almanac"
- started the first free libraries
69. Who is the "Father of Our Country"?
- (George) Washington
70. Who was the first President?*
- (George) Washington
1800s
71. What territory did the United States buy from France in 1803?
- the Louisiana Territory
- Louisiana
72. Name one war fought by the United States in the 1800s.
- War of 1812
- Mexican-American War
- Civil War
- Spanish-American War
73. Name the U.S. war between the North and the South.
- the Civil War
- the War between the States
74. Name one problem that led to the Civil War.
- slavery
- economic reasons
- states' rights
75. What was one important thing that Abraham Lincoln did?*
- freed the slaves (Emancipation Proclamation)
- saved (or preserved) the Union
- led the United States during the Civil War
76. What did the Emancipation Proclamation do?
- freed the slaves
- freed slaves in the Confederacy
- freed slaves in the Confederate states
- freed slaves in most Southern states
77. What did Susan B. Anthony do?
- fought for women's rights
- fought for civil rights
Recent American History and Other Important Historical Information
78. Name one war fought by the United States in the 1900s.*
- World War I
- World War II
- Korean War
- Vietnam War
- (Persian) Gulf War
79. Who was President during World War I?
- (Woodrow) Wilson
80. Who was President during the Great Depression and World War II?
- (Franklin) Roosevelt
81. Who did the United States fight in World War II?
- Japan, Germany, and Italy
82. Before he was President, Eisenhower was a general. What war was he in?
- World War II
83. During the Cold War, what was the main concern of the United States?
- Communism
84. What movement tried to end racial discrimination?
- civil rights (movement)
85. What did Martin Luther King, Jr. do?*
- fought for civil rights
- worked for equality for all Americans
86. What major event happened on September 11, 2001, in the United States?
- Terrorists attacked the United States.
87. Name one American Indian tribe in the United States.
- [USCIS Officers will be supplied with a list of federally recognized American Indian tribes.]
- Cherokee
- Navajo
- Sioux
- Chippewa
- Choctaw
- Pueblo
- Apache
- Iroquois
- Creek
- Blackfeet
- Seminole
- Cheyenne
- Arawak
- Shawnee
- Mohegan
- Huron
- Oneida
- Lakota
- Crow
- Teton
- Hopi
- Inuit
Part C: Geography and civic integration (questions 88-100)
Geography
88. Name one of the two longest rivers in the United States.
- Missouri (River)
- Mississippi (River)
89. What ocean is on the West Coast of the United States?
- Pacific (Ocean)
90. What ocean is on the East Coast of the United States?
- Atlantic (Ocean)
91. Name one U.S. territory.
- Puerto Rico
- U.S. Virgin Islands
- American Samoa
- Northern Mariana Islands
- Guam
92. Name one state that borders Canada.
- Maine
- New Hampshire
- Vermont
- New York
- Pennsylvania
- Ohio
- Michigan
- Minnesota
- North Dakota
- Montana
- Idaho
- Washington
- Alaska
93. Name one state that borders Mexico.
- California
- Arizona
- New Mexico
- Texas
94. What is the capital of the United States?*
- Washington, D.C.
95. Where is the Statue of Liberty?*
- New York (Harbor)
- Liberty Island
- [Also acceptable are New Jersey, near New York City, and on the Hudson (River).]
Symbols
96. Why does the flag have 13 stripes?
- because there were 13 original colonies
- because the stripes represent the original colonies
97. Why does the flag have 50 stars?*
- because there is one star for each state
- because each star represents a state
- because there are 50 states
98. What is the name of the national anthem?
- The Star-Spangled Banner
Holidays
99. When do we celebrate Independence Day?*
- July 4
100. Name two national U.S. holidays.
- New Year's Day
- Martin Luther King, Jr. Day
- Presidents' Day
- Memorial Day
- Independence Day
- Labor Day
- Columbus Day
- Veterans Day
- Thanksgiving
- Christmas
Frequently Asked Questions about the Citizenship Exam
How many questions are asked on the citizenship exam?
During the civics portion, an officer from USCIS will ask up to 10 questions out of a list of 100. You need to answer at least 6 correctly to pass this part of the test.
Is the citizenship exam in English or Spanish?
The exam is conducted in English, including both the English and civics portions. However, applicants who qualify for the 65/20 exemption can take the civics test in Spanish. Make sure you verify if the exemption applies in your specific case with the corresponding authorities.
What happens if I don't pass the exam the first time?
If you fail either the English or civics section, you are given a second opportunity to retake the part you did not pass. This second interview typically takes place within 60 to 90 days.
How much does the citizenship exam cost in 2026?
The exam itself does not have a separate fee, but it is included in the naturalization application. As of 2026, the cost to file Form N-400 is $760, though it's always a good idea to verify updates directly with USCIS.
Do the citizenship exam questions change?
The list of questions is updated occasionally by USCIS. The current version is based on the reinstated 2008 civics test, which remains the standard as of 2026.
Can I study the citizenship questions in Spanish?
Yes, many applicants study the questions in Spanish to better understand the content. However, the actual exam is conducted in English unless you qualify for an exemption like the 65/20 rule.
5 Tips for Studying for and Passing Your Citizenship Exam
Preparing for the citizenship test doesn't have to feel overwhelming. Approaching it with a plan and consistency could be the key for a smoother experience. Here are some general tips we've enlisted for preparing for your citizenship exam:
Study by category, avoid trying to learn all of them at once.
Break the 100 questions into topics like history, government, and geography. This makes it easier to understand patterns instead of trying to memorize everything in one go.
Practice your answers out loud.
The exam is oral, so it's important to get comfortable saying your answers, not just recognizing them. This helps with confidence during the interview.
Start with questions that change.
Aim to focus first on answers that can vary, like the current president or your state's senators. Learning these early helps you avoid confusion later in the process.
Use flashcards and try to study with someone.
Flashcards are a great tool for repetition and reinforcing memory. If possible try practicing with a friend or family member to simulate the real experience of being asked questions.
Don't panic if you don't know everything.
You don't need a perfect score. You only need to answer 6 out of 10 questions correctly, so focus on being consistent, not perfect.







Thousands of immigrants are already achieving more with their money. You can too.
Comun is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank; Member FDIC. The Comun Visa® Debit Card is issued by Community Federal Savings Bank, pursuant to a license from Visa U.S.A Inc. and may be used everywhere Visa Cards are accepted.
Comun is a fintech company and not a bank or licensed money transmitter.
* Results may vary. For a complete list of eligible IDs and application requirements, follow this link.
^ No minimums, no maintenance fees. ATM or transfer fees may apply. See app for fee details.
‡ Direct deposit funds are typically available when we receive the payment file, up to two days before the scheduled payment date. This early availability is not guaranteed.
** A service provided by Service UniTeller, Inc. Service UniTeller, Inc. is licensed in all states that require a license. Remittance fees start at $2.99 but may vary. Please check the app for more details. Comun Inc. may earn revenue from the conversion of foreign currencies.
† Funds in your account are FDIC insured up to $250,000 by ownership category through Community Federal Savings Bank (CFSB), Member FDIC, in the event CFSB fails.


