Financial Education
Discover how small business banking services, like accounts, loans, and digital banking, can drive your business's growth and stability.
8 min read

23 Aug 2024

Small Businesses
Running a small business involves making numerous financial decisions, and choosing the right banking services is crucial for success. Separating personal assets from business assets in an LLC structure is important for protecting personal property in case of business bankruptcy. Community banks and modern financial platforms offer a variety of services tailored to meet small businesses' unique needs. This complete guide explores the essential banking services for small businesses, highlighting their benefits and how they can support growth and stability.
Understanding Different Types of Small Businesses and Their Banking Needs
Before exploring specific banking services, it's essential to understand the range of small businesses and their unique financial needs. Different types of small businesses — like sole proprietorships, partnerships, LLCs, corporations, nonprofits, home-based businesses, and startups — require tailored banking solutions to support their growth and stability. Keeping business and personal bank accounts separate offers benefits like accurate record-keeping, simplified tax preparation, better financial organization, and enhanced professionalism. By recognizing these differences, you can better appreciate how community banks and financial platforms like Común meet small business owners' diverse needs. This understanding lays the groundwork for selecting the most appropriate banking services to ensure financial health and success.
Business Checking and Savings Accounts
Having a dedicated business checking account is fundamental to managing your finances effectively. It lets you separate personal and business transactions, simplifying bookkeeping and ensuring clear financial records. Many banks offer business checking accounts with features like free transactions, low fees, and online banking capabilities.
When opening a business bank account, gather the required documentation, like your Employer Identification Number (EIN), and decide whether you want to apply online or visit a branch. Understanding the fees and essential steps to open the account is crucial.
A business savings account is also vital. It helps you set aside funds for future investments, emergencies, or growth opportunities. Look for accounts with competitive interest rates and flexible access to your funds.
Business Loans and Lines of Credit
Access to credit is often essential for small business growth. Community banks and other financial institutions provide various loan products, including term loans, lines of credit, and SBA loans. These financial products can help you finance new equipment, expand operations, or cover unexpected expenses.
Working with a community bank for loans and lines of credit means you benefit from personalized service. Bank representatives can provide tailored advice, helping you choose the right loan product for your needs and guiding you through the application process. This relationship-based approach ensures you get the support needed to grow your business sustainably.

Payment Processing, Payroll, and Cash Flow Management Services
Effective financial operations are critical to any small business's success. This includes processing payments, managing payroll, and ensuring efficient cash flow. Here's how comprehensive banking services can support these needs:
By integrating these services, banks provide a comprehensive solution that supports small businesses in maintaining smooth, efficient financial operations.
Online and Mobile Banking
In today's digital age, online and mobile banking are indispensable. These services provide convenient access to your accounts, letting you monitor transactions, transfer funds, and pay bills anytime, anywhere.
Open your bank account¹ in 3 minutes with your country's ID²
Common Problems Small Businesses Face With Banking Services and Financial Health
While banking services are crucial to small business operations and growth, many small business owners face various challenges when managing their financial needs. Understanding these issues can help businesses make more informed decisions and find solutions that better fit their requirements.
Understanding these common issues can help small business owners better navigate the challenges they face with banking services. By seeking out community banks or financial platforms like Común that prioritize transparency, customer service, security, and integration with business tools, small businesses can find banking solutions better suited to their needs and supportive of their financial success.
Conclusion:
Choosing the right banking services is essential for your small business's success and growth. From checking and savings accounts to loans, merchant services, and digital banking, the right financial products and support can help you manage your finances effectively and reach your business goals. By partnering with a community bank and leveraging platforms like Común you can access the tools and expertise needed to thrive in today's competitive market.
Integration and Support
Many community banks pride themselves on offering personalized service and financial advice. Building a relationship with your bank can provide valuable insight into managing your finances, accessing credit, and planning for future growth. Take advantage of workshops, seminars, and one-on-one consultations offered by your bank to improve your financial literacy and business knowledge.
For small businesses looking to leverage modern financial technology, integration with platforms like Común can improve their banking experience. Común offers a range of features tailored to small businesses, including instant notifications, secure login, and personalized customer support available seven days a week. By combining the strengths of traditional community banking with the convenience of digital banking, Común provides a comprehensive solution for managing your business finances.
Open your bank account¹ in 3 minutes with your country's ID²
About Común
Común aims to support the Latino community in the United States. It offers a debit account that can be opened with more than 100 valid Latin American IDs and an app available in Spanish.
Visit Común's website or download the app for free to learn more about the full offer and applicable terms.

Olivia Rhye
Community Partner

International Money Transfers
8 min de lectura
The total cost may depend on three main factors: the transfer fee, the exchange rate used to convert USD to Guatemalan quetzales (GTQ), and any charges applied when the recipient receives the money. The total cost can vary from one transfer to another, depending on the provider and delivery method.
For many Guatemalans living in the United States, sending money back home is important. Some people support their families by covering everyday expenses or helping during emergencies. According to the World Bank, Guatemala is the second-largest recipient of remittances in the Latin America and Caribbean region, after Mexico. Remittances play a vital role in supporting rural communities in Guatemala, which receive over half of total flows.
Today, there are many ways to send money to Guatemala from the United States, including banks, cash pickup services, and apps and digital platforms. Comparing costs, delivery times, and exchange rates before sending can help your family receive more money overall.
How much money can you send to Guatemala?
The amount you can send to Guatemala may depend on the provider you choose, your account verification level, and the payment method used for the transfer.
In general, there is no single universal limit imposed on personal remittances from the United States. However, money transfer companies and financial institutions usually apply their own transfer limits as part of fraud prevention and regulatory compliance requirements.
For example:
Before sending money, it is recommended to review the provider’s limits, accepted identification documents, and delivery methods available in Guatemala.
What determines the real cost of sending money to Guatemala?
The real cost of sending money to Guatemala may depend on three main factors:
Transfer fee
The transfer fee is the amount charged to process the remittance.
Some services use a flat fee structure, while others may adjust the pricing depending on the amount sent, payment method, or delivery speed. Some service providers may also offer promotional pricing for first-time transfers.
Although low fees can help reduce costs, they may not always represent the lowest total transfer cost once exchange rates and other charges are considered.
Exchange rate spread (USD to GTQ)
Another important factor is the exchange rate used to convert U.S. dollars into Guatemalan quetzales.
Some providers may apply a margin (also known as a spread) on top of the market exchange rate. Even small differences in the USD to GTQ conversion rate can affect how many quetzales your family receives, especially on larger transfers.
Comparing the final amount received in GTQ may provide a more accurate picture of the total transfer cost.
Recipient charges or withdrawal costs
In some cases, the recipient may face additional costs when receiving the money. These depend on the provider and delivery method.
There could be charges related to ATM withdrawals, cash pickup locations, bank processing, or currency conversion. These costs may vary depending on the institution or pickup network used in Guatemala.
What is the best way to send money to Guatemala from the United States?
The best way depends on your context and priorities. Today, there are many ways to send money to Guatemala from the United States, with different service providers offering features such as faster delivery times, multiple delivery methods, or lower overall transfer costs depending on the type of transaction.
Traditional banks
Some people choose to send money through traditional bank wire transfers. This option is available for people who already use a U.S. bank account.
However, international bank transfers can sometimes involve higher fees, slower processing times, special considerations such as banks in the U.S. generally being closed for federal holidays or additional requirements such as SWIFT codes and recipient banking information.
Cash transfer agencies
Cash pickup services continue to play an important role for many families in Guatemala, especially for recipients who primarily manage their finances in cash or who may not have easy access to traditional banking services.
Companies such as Western Union, MoneyGram, and Ria Money Transfer can offer extensive pickup networks across Guatemala through local banks, convenience stores, supermarkets, and remittance partners.
This option can be convenient for recipients who prefer immediate access to cash, although some traditional cash transfer services may involve higher fees or exchange rates that are less favorable compared to other options.
Digital apps and platforms
Another option is using apps and digital platforms specialized in international transfers.
Services such as Común, Félix Pago, Ria Money Transfer, and MoneyGram offer options to send money directly from your phone, either through an app or even WhatsApp. These services often include multiple delivery options available in Guatemala.
While some of these service providers focus mainly on remittances, others may also include features such as debit cards, mobile banking access, or account management tools. For example, Común (https://www.comun.app) offers a debit card that accepts more than 100 Latin American IDs for account verification, it also offers the option to send money on the app or using WhatsApp, and offers cash pickup options in Guatemala.
Comparing services for sending money to Guatemala
There are services available for sending money to Guatemala, but the fees, exchange rates, transfer speeds, and delivery methods can vary depending on the provider and transfer type. This table was created to provide a visual aid for comparing 5 popular remittance service providers in the United States to Guatemala.
| Service | Payment Options | Fee | Delivery Options | Exchange Rate | Speed |
|---|---|---|---|---|---|
| Común | Bank account, debit card, cash | Starting at 2.99 USD | Bank account or cash pickup | Competitive | Minutes to hours |
| Western Union | Bank account, card, cash | Varies depending on amount and method | Cash pickup, bank deposit, wallet | Varies with applicable spread | Minutes to days |
| Ria Money Transfer | Bank account, debit card, credit card, cash | Starting at $0.99; can be free for bank transfers up to $15,000 | Cash pickup, bank deposit, wallet | Varies with applicable spread | Minutes to days |
| MoneyGram | Bank account, debit card, credit card, cash | Varies depending on amount and delivery method | Cash pickup, bank deposit, wallet | Varies with applicable spread | Minutes to hours |
| Félix Pago | WhatsApp, debit card, cash | $2.99 USD for bank account transfers and $4.98 USD for cash pickup transfers | Bank account and cash pickup | Competitive | Instant to days |
The total amount received in GTQ is subject to change throughout the day due to exchange rate fluctuations, provider fees, and delivery methods.
To compare real-time transfer costs and exchange rates, you can use tools such as Común Compara (https://www.comun.app/compara) designed to help you have more clarity on remittance costs. If applicable, you may see a "Primer envío" toggle that reflects promotional pricing for eligible first transfers.
How does the recipient receive money in Guatemala?
It depends on the provider selected, as recipients in Guatemala can receive money through different delivery methods.
Bank deposit
Some service providers offer direct deposits into Guatemalan bank accounts in quetzales. The delivery speed can vary depending on the receiving bank and transfer verification process.
Cash pickup
Depending on the provider and the recipient's location, they can collect money from local banks, remittance agencies, supermarkets, or retail stores.
To receive the money, recipients often require a valid identification document and the transfer reference number.
Delivery times
Transfer times can vary depending on the provider, payment method, verification requirements, holidays, and delivery option selected.
Some digital transfers can arrive within minutes, while bank transfers or certain cash pickup options could take longer.
How can I send money to Guatemala with Común?
With Común, people can send money to Guatemala directly from the mobile app. To send money, you can follow the steps:
Transfer fees start at 2.99 USD per transaction, up to applicable limits.
Why choose Común to send money to Guatemala?
Común’s vision is to become the leading financial platform for immigrants in the U.S. Therefore, it can include elements that are helpful for people sending money to Guatemala from the United States.
Some of the services include:
As with any financial service, transfer costs, delivery speeds, and availability may vary depending on the transaction details. You can learn more about Común on our website (https://www.comun.app/about-us) or in the app (https://www.comun.app/).
FAQ
How much does it cost to send money to Guatemala?
The total cost may depend on the provider, transfer fee, exchange rate, delivery method, and whether the recipient faces additional charges.
How long does it take for money to arrive in Guatemala?
Transfer times can vary depending on the provider and delivery method selected. Some digital transfers may arrive within minutes, while others could take several business days.
What is the best app to send money to Guatemala?
The best app may depend on what matters most to you, whether that's lower fees, exchange rates, delivery speed, or cash pickup availability.
Do I need an SSN to send money to Guatemala?
Some providers may require an SSN, while others may also accept an ITIN or alternative identification documents depending on their verification policies. It is important to check each service provider’s verification requirements.
How much money can you send to Guatemala from the United States?
Transfer limits may vary depending on the provider, payment method, and verification level.
Where can my family receive money in Guatemala?
Depending on the provider, recipients may receive money through bank deposits, cash pickup locations, mobile wallets, or other delivery methods available in Guatemala.

International Money Transfers
8 min de lectura
Knowing how to receive money from the United States is essential, as remittances have become a key part of the economy for thousands of immigrant households. According to estimates, by 2030, migrant workers will send a total of $5 billion to their country of origin.
The growing need to send and receive money from abroad has encouraged the creation of new methods specifically designed for countries like Latin America. Below, we present the fastest, easiest, and safest options for receiving your money without complications.
You will learn everything about receiving money from the United States and Latin America: key aspects such as costs and security, requirements to open an account, and different applications for sending money from the United States. By the end of this article, you will know exactly which option is best suited to your needs.
Thanks to technological advances and financial openness, sending and receiving money through digital means is increasingly simple and accessible.
However, immigrant families still face various obstacles, such as high transfer fees, bank-imposed restrictions, and weak security measures.
Undoubtedly, this is not a decision to be taken lightly. Before accepting the terms and conditions of any provider, pay attention to the following key aspects:
Access to cash quickly is a fundamental need for users receiving money from the United States. The reception time varies depending on the sender and other important factors:
A fundamental aspect to consider when receiving money from the United States is the fees, which can exceed 10% of the total amount and significantly reduce household support.
Consider an option that offers affordable costs and a favorable exchange rate.
The theft of personal data, commonly known as phishing, is the primary risk in international money transfers. To avoid becoming a victim of such fraud, make sure to use a reliable service through an official website or mobile app. Additionally, do not share passwords or sensitive information with third parties.
According to the study Remittances to Latin America and the Caribbean 2024, 60% of migrant workers in the United States send money to their mothers. It is important to choose a provider that understands your needs and offers reliable, secure, and easy-to-use platforms.
If for any reason you cannot receive money through bank transfers, look for an option that offers cash pickup locations near you, such as Oxxo or Walmart.
Regardless of the bank you choose the requirements for receiving money can be summarized as your basic personal information:
The requested data may vary depending on the receiving country, so you may be asked for more or less information. Remember, no reputable institution will ask for passwords or access information to complete transfers or send money.
If you need to send and receive money from the United States to Mexico, you can choose from the following options:
This is a simple way to receive money from the United States, as it allows you to do so from the comfort of your home via a mobile application.
In the case of Mexico, most traditional banks tend to receive transfers from the United States under their own terms and conditions. This means that fees and exchange rates vary by financial institution.
For Banorte and BBVA, the cost for international transfers is $30 plus VAT, regardless of the amount sent.
Receiving money through traditional financial institutions can be expensive; fortunately, there are more affordable alternatives.
Comun allows you to send money from the United States to Latin America with no charge on your first transfer and accessible fees thereafter. It is the preferred option among the immigrant community, offering shared language, interests, and goals: bringing families closer together through secure and affordable financial solutions.
Open your account with Comun and start sending money from the United States to your home without complications. Your family can receive it in local bank accounts or collect it physically at partner locations.
Wise is another platform that offers international money transfers. It is geared toward independent workers around the world who earn income from the United States.
Although it is a common alternative for receiving money digitally from abroad, it does not offer physical pickup options, which may be a drawback for migrant families.
Western Union is one of the most popular options among migrant workers in the United States, as it allows for cash transfers without the need for a bank account, including to rural or hard-to-reach areas.
It is a suitable option in certain circumstances, but be aware that Western Union’s commission fees are typically high, and it uses a lower exchange rate than the market.
The cost of sending money depends on several factors, such as the method used and the destination country. However, the fee can reach up to 6%, not including the exchange rate difference.
Finally, MoneyGram is an international money transfer service operating in over 200 countries, including Mexico.
As you can see, sending and receiving money from the United States does not have to be complicated. Today, there are financial services that aim to bridge the gaps that hinder communication between businesses and individuals.
Comun is an accessible option for all, offering the best benefits for immigrant families:
Compare and choose the option that best fits your needs. Remember that you have an ally in Comun to receive money from the United States without complications.
Frequently Asked Questions
With Comun, your money arrives in minutes via bank transfers. Cash pickups at partner locations take as little as 1 hour.
Fees usually depend on the amount and destination country. Comun offers a transfer fee starting at $2.99, regardless of the amount sent up to the applicable limits.
Comun provides a checking account that includes a debit card and mobile application. However, it is not required, since you can receive money at physical locations.
Absolutely. Comun is backed by major financial institutions. Your Comun account funds are insured by the FDIC up to $250,000 per ownership category through Community Federal Savings Bank (CFSB), member of the FDIC, in the event of CFSB’s failure.

Immigration
8 min de lectura
Finding a path that gives you job opportunities in the United States can be hard work, especially if you’re unfamiliar with the different visa types offered by the U.S. government.
The H-1B visa is an option that could open the door to a new life in the U.S. In this guide, we explain what it is, what it’s for, who can apply, when it applies, and its benefits and limitations.
It’s essential to understand this visa’s features—as well as how it differs from other work visas—so you can ensure it fits your professional goals in the country.
With this information, you’ll be able to plan a strategy to obtain the visa and fully establish yourself in the United States.
The H-1B visa is authorization granted to foreign workers to temporarily perform specialty occupations that generally require specialized knowledge and prior experience.
It is a nonimmigrant visa with an initial duration of 3 years and, in most cases, can be extended up to a maximum of 6 years.
There are exceptions, such as when the temporary worker is in the process of obtaining permanent residence, in which case the visa may be extended for a longer period.
Before starting the immigration process, you should know the H-1B requirements and verify that your background aligns with them to determine eligibility.
To obtain an H-1B visa, you must have a higher education degree or its U.S. equivalent. The job offer must also be related to the specialty area of the degree presented.
As with the EB-3 visa, the H-1B also requires a job offer from a U.S. employer, who must file Form I-129 with USCIS.
Keep in mind that this visa is used for jobs requiring specialized knowledge, and openings most often arise in the following areas:
Another key point is that this visa has an annual issuance cap, divided as follows:
Because filings often exceed these limits, USCIS established a selection system consisting of electronic registration and a random lottery.
The draw occurs in two phases: first the 65,000 regular slots are selected, and then 20,000 additional slots are drawn for U.S. advanced degree holders.
Between March and April, employers receive notification of the lottery results. If not selected, you may wait for a second round if quotas aren’t filled or, otherwise, apply the following year.
Below is how the H-1B application process works.
First, the U.S. employer must register the candidate on USCIS’s official site during the designated window, generally in March. The registration fee—listed on the same site—must also be paid.
If the candidate is selected, the employer receives a USCIS notice and can proceed to the next stage.
Note that before filing with USCIS, the employer must obtain a certified Labor Condition Application (LCA) from the Department of Labor (DOL).
After selection, the employer has 90 days to file Form I-129, Petition for a Nonimmigrant Worker, along with required documentation.
At this stage, it’s necessary to show the position is a specialty occupation and that the candidate meets the requirements.
USCIS reviews the filing and, if needed, issues a Request for Evidence to seek additional information or clarification.
If everything is in order, the employer receives an approval notice, and the candidate proceeds with consular processing or a change-of-status request.
If the candidate is outside the U.S., they must attend a U.S. consulate, complete Form DS-160, and appear for a consular interview.
If the candidate is already in the U.S. under another status, the employer files the H-1B petition indicating the worker is in the United States.
In both cases, USCIS approval is required before visa issuance can proceed.
H-1B holders enjoy several benefits that can improve their lives and those of their families; however, it’s also important to note the limitations.
Although temporary, the H-1B allows you to work legally in the United States in your field of specialty. This can open many doors and strengthen your professional experience.
H-1B workers may later pursue permanent residence (a Green Card) and extend benefits to immediate family members such as a spouse and unmarried children under 21.
As noted, this visa does not automatically confer permanent residence; it lasts a maximum of 6 years. Still, it can be a first step toward it.
This visa depends entirely on the employer extending the job offer and completing the filing process.
The visa is numerically capped, and filings typically exceed the annual cap, reducing the likelihood of selection.
To prevent these limits from becoming obstacles, consider planning ahead if you intend to pursue permanent residence. You can also evaluate other work visas, such as EB-2 and EB-3, which may be more suitable for long-term plans in the United States.
Here we covered how to file for the H-1B visa, the requirements, benefits, limitations, and who it’s ideal for.
When you arrive in the United States, you’ll need an ally to help you manage your finances easily. Meet Común!
Open your Común account today and manage your money in the U.S.
Your employer must sponsor permanent residence under an employment-based category, file PERM with the DOL, and then file Form I-140.
A maximum of 6 years.
Form I-129: from $460 to $780.
An anti-fraud fee may apply.

Immigration
8 min de lectura
The United States offers a wide variety of visas to include as many profiles as possible that can contribute their knowledge to the country.
One example is the O1 visa, intended for foreign nationals who possess extraordinary abilities in fields such as science, sports, and the arts.
This visa has very specific criteria. Therefore, in this article, we explain the requirements established by the U.S. government to obtain it, the classification of O1 visa types, and the documents required during the application process.
If you are looking for an alternative to obtain a work visa in a highly competitive field, the O1 visa could open the door to a new life.
The O1 is a U.S. nonimmigrant visa aimed at foreign nationals with extraordinary abilities or outstanding achievements in specific areas.
The concept of “extraordinary ability” can seem a bit ambiguous, but in this context, USCIS refers to individuals who have reached such a level of excellence in their field that they have verifiable national or international recognition.
This visa is divided into two main categories:
For individuals with extraordinary achievements in science, education, business, or athletics.
For individuals with extraordinary ability in the arts, motion picture, or television industry.
As you can see, it is an immigration document that demands a high level of achievement from applicants in specific areas of work.
To qualify for an O1 visa, applicants must meet a series of requirements established by USCIS.
Below are the main requirements for the two categories of this visa.
Applicants with outstanding achievements in science, education, business, or athletics must demonstrate they meet the following eligibility criteria:
Applicants with outstanding achievements in the arts, film, or television industry can demonstrate eligibility if they meet the following requirements:
It is important to note that it is not necessary to meet all these requirements, but the more criteria the applicant fulfills, the easier it will be to obtain the visa.
In both cases, applicants must have a job offer or a sponsor in the United States.
In addition to meeting the criteria, the applicant must have the following documents to prepare a complete application.
This form must be filed by the U.S. employer or agent and should include the following details:
This letter is essential to support the applicant’s experience in their field. It must be issued by a group of peers, a union, or an expert entity.
It is a document signed by the applicant and the employer that sets out the terms and conditions of employment, responsibilities, and duration.
Additionally, the previously mentioned requirements can be supported with the following documentation:
If you have any doubts about your application process, consult an immigration attorney who can help you determine whether your profile fits this type of visa, which is often considered an elite category. Keep in mind that there are other options such as the EB-1 and H-1B visas.
In this article, we explained that the O1 is the visa for individuals with extraordinary abilities, aimed at people with outstanding performance in science, sports, and the arts. We also covered the approval requirements and documentation needed to demonstrate that you belong to the groups covered by this work authorization.
Arriving in a new country to work involves many changes and learning to adapt to customs and regulations. When it comes to managing money effectively, it is essential that immigrants have access to quality financial services.
Discover Común, the financial platform that makes life easier for immigrants in the U.S.!
Open your account with Común today and build your future in the U.S. with a financial platform designed for immigrants.
No, the O1 visa always requires a sponsor to initiate the process. This sponsorship may be provided by a U.S. employer or an agency that acts as an intermediary between the applicant and contractors in the United States.
Although this visa cannot be self-petitioned, there is an option to hire an agent to submit the initial petition.
The most common investor visa is the EB-5, which requires a minimum investment of $1,050,000 if the investment is made in a rural area or one with high unemployment.
A key requirement is that the project must create or maintain at least 10 full-time jobs in the United States.
Another investor visa option is the E-2, or treaty investment visa, which does not require a fixed amount but requires the applicant to prove that the investment is large enough to generate a positive impact.
The documents that usually carry the most weight for O1 visa approval are those that demonstrate sustained and verifiable recognition.
For example:
Although it is not necessary to present all these documents, the more evidence there is, the greater the chances of approval.
The initial duration is 3 years, depending on the project. Extensions of 1 year can be requested as long as the requirements continue to be met.

Instant payments
8 min de lectura
Are you looking for an option to send and receive money within the United States? In the digital era, it is essential to have access to an immediate, secure, and free transfer service.
Sometimes sending and receiving money can be challenging due to high fees or limited access to the banking system. For this reason, knowing how to register for Zelle and learning about alternative solutions such as Comun will be extremely useful for sending money without complications through the most efficient services.
In this guide, we will explain what Zelle is, how to register, what requirements are necessary to send and receive money, and why Comun works as a complementary solution to expand your options when facing restrictions that could hinder your access to mobile payment services.
Zelle is a digital P2P (peer-to-peer) payment service available in the United States. It is associated with more than 20,200 traditional and digital banks and credit unions, such as Bank of America, Wells Fargo, Ally Bank, Capital One, and Navy Federal Credit Union. Zelle is well known for its wide coverage and ease of transferring funds between users of this system.
Other advantages of Zelle include:
Please note that Zelle is only available within the United States. If you need to make international transfers, find the best options here.
Zelle operates through its connection with their affiliated banks’ applications. To send and receive money, you must first verify that your bank is part of this service’s network.
If so, complete your registration directly through your bank’s online platform and begin sending and receiving money to your account using a phone number or email address.
Using Zelle is very practical for daily transactions such as paying rent or purchasing goods and services. It is also a secure way to send money to family and friends.
In addition to Zelle, there are other alternatives for sending and receiving money within the United States. Discover the 6 best mobile apps of 2025.
Zelle announced an important change in its application that took effect in April 2025. The change consists of eliminating transfers through its standalone app, as the service can now only be accessed through the online banking platforms of U.S. financial institutions integrated into its network.
If you wish to download the Zelle app, you may still use it to review your payment history.
How to Download Zelle to My Phone: Key Requirements to Register and Use It Without Complications
To have a Zelle account, you only need to meet the following requirements:
Sometimes, opening an account is not accessible for many individuals, whether due to lack of required documentation or insufficient credit history.
If this is your situation, Comun is a great alternative for sending money to your loved ones safely, quickly, and at low cost.
Comun is a platform that understands the needs of immigrant communities in the United States. Open your account today and experience an accessible alternative for your finances.
If you are wondering how to open a Zelle account, simply follow these steps:
1. Open Your Bank’s Mobile Application (If It Is a Zelle Partner)
Once you verify that your bank works with Zelle, open the mobile application and register if you have not done so yet.
2. Locate the Transfers and Payments Section
In the main menu, click on the transfers and payments section, then select “Send Money with Zelle.”
3. Register Your U.S. Phone Number or Email Address
To send and receive money with Zelle, it is necessary to register a U.S. phone number and an email address.
4. Link Your Bank Account
Confirm your information and start sending and receiving money with Zelle quickly after completing a test transaction.
Undoubtedly, Zelle is an excellent tool for bank transfers, offering a fast and very simple service to use. Although it is only available to users of participating banks, it has broad coverage.
While Zelle represents a practical solution for many users, it has limitations such as requiring an eligible U.S. bank account.
Comun, on the other hand, is an alternative solution that goes beyond traditional limitations, as it allows you to send international transfers using your official national identification. It is designed for immigrants in the United States and offers simplified financial management. This service provides you with:
Download the Comun app and enjoy transparent, easy, and personalized finance designed for you.

Instant payments
8 min de lectura
Zelle is built directly into many bank accounts in the U.S., which is why it has become one of the most widely used ways to send money. Today, more than 2,000 banks and credit unions offer access to the service.
Understanding how that network works is key to knowing whether you can use it with your account. That distinction matters more today than it did a few years ago. Since April 2025, Zelle is no longer available as a standalone app. Access depends entirely on whether your bank is part of the network.
Zelle is a peer-to-peer payment network owned by Early Warning Services LLC (EWS), a company co-founded by seven of America's largest banks: Bank of America, Capital One, Chase, PNC, Truist, U.S. Bank, and Wells Fargo. It allows you to send money directly from your bank account to another person's bank account using only a phone number or email address. Transfers are typically completed within minutes.
The main appeal of Zelle is its speed, simplicity, and convenience. Transfers are typically completed within minutes and move directly between bank accounts without the need to load funds into a separate app or digital wallet. In most cases, there are no fees for sending or receiving money, making it a practical option for everyday payments such as rent, shared expenses, or paying friends and family.
Because Zelle is integrated into your bank's app, there is usually no additional setup beyond enrolling your email address or mobile number. Funds are deposited directly into your account and are generally available quickly.
As of April 1, 2025, Zelle can only be accessed through participating financial institutions. If your bank or credit union does not support Zelle, you generally can't use the service.
Zelle partners with more than 2,300 financial institutions. To search for a specific bank or credit union, visit zellepay.com/get-started.
Below is a representative, not exhaustive list of financial institutions that currently offer Zelle:
| Name | Transfer limit |
|---|---|
| TRADITIONAL FINANCIAL INSTITUTIONS | |
| Bank of America | Up to $3,500 USD per day |
| Chase | Dynamic limit; typically $500 to $10,000 USD per day |
| Citi Bank | Up to $2,500 USD per day for accounts open longer than 30 days |
| TD Bank | $1,000 USD for instant transfers; up to $2,500 USD for scheduled transfers |
| PNC Bank | Typically $500 to $2,500 USD per day |
| Wells Fargo | Up to $3,500 USD per day |
| DIGITAL BANKS | |
| Ally Bank | Up to $600 USD per day |
| Discover Bank | $500 USD per transaction; $1,000 USD per day |
| SoFi | Up to $1,000 USD per day |
| Truist Bank | Typically $2,000 USD per day to $10,000 USD per month |
| EverBank | Up to $2,000 USD per day |
| CREDIT UNIONS | |
| BECU (Boeing Employees Credit Union) | $1,500 USD per day (instant); $3,000 USD per day (standard) |
| Bethpage Federal Credit Union | Limits vary by account and membership |
| Delta Community Credit Union | Limits vary by account and membership |
| First Tech Federal Credit Union | Limits vary by account and membership |
| Navy Federal Credit Union | Limits vary by account and membership |
Please note that Zelle limits often depend on factors such as account age, transaction history, recipient details, and other risk-based criteria established by the financial institution. Please refer to your financial institution for the most up-to-date information.
Since the standalone Zelle app has been discontinued, you must enroll through a participating bank or credit union app. The following steps generally apply to most participating financial institution apps:
Please note that both the sender and recipient generally must be enrolled with Zelle through participating financial institutions for transfers to be completed. If the recipient isn't enrolled, they may receive instructions on how to enroll. If enrollment is not completed within the applicable timeframe, the transaction may be canceled and refunded.
Zelle uses bank-level encryption and security protocols and operates within participating financial institution apps. However, many reported issues involving Zelle are associated with fraud or social engineering scams rather than technical failures.
Because Zelle transfers are typically processed quickly and may be difficult or impossible to reverse once authorized, scammers may attempt to pressure users into sending funds.
Fake bank fraud alerts:
Scammers may send text messages appearing to come from your bank asking whether you authorized a transaction. After you respond, you may receive a call from someone falsely claiming to represent the bank and instructing you to transfer funds to 'reverse' fraud. In reality, the funds are being sent to the scammer.
Impersonation scams:
Scammers may claim to represent a bank, government agency, utility company, or another trusted organization and pressure victims into sending money immediately.
Marketplace scams:
Fraudsters on platforms such as Facebook Marketplace or Craigslist may request payment through Zelle. After funds are sent, the item may never arrive or the payment may later prove fraudulent.
Overpayment scams:
A scammer may claim to have 'accidentally' sent money and ask for it to be returned. Their original payment may later be reversed or determined to be fraudulent.
Zelle's transition away from a standalone app in April 2025 created challenges for individuals who do not have accounts with participating financial institutions.
Venmo and Cash App
Remain popular alternatives for domestic transfers and may not require a traditional bank account to get started. However, they generally do not support international money transfers.
Wise
Allows users to receive and send funds internationally using local bank details in many currencies. It is commonly used for international transfers and is known for transparent pricing and exchange rates based on the mid-market rate.
Común
Is a financial platform that promotes financial inclusion for individuals who may face barriers with traditional U.S. banks, offering user-friendly, Spanish-language support. With Común you can make transfers within and outside the U.S. and send money to friends and family throughout Latin America, with fees starting at $2.99 per transfer. Visit comun.app to learn more.
Zelle itself generally doesn't charge fees to send or receive money. However, your financial institution may have its own fee structure for the underlying account. It is important to check the specific details with your financial institution.
Since the standalone Zelle app was discontinued in April 2025, your options may include opening an account with a participating financial institution or using an alternative service such as Venmo, Cash App, Wise, or Común.
No. Zelle generally requires a U.S. bank or credit union account at a participating financial institution.
No. Zelle supports transfers only between U.S. bank or credit union accounts at a participating financial institution. For international transfers, consumers may consider alternatives such as Wise, Remitly, or international money transfer providers.
Contact your financial institution immediately. Once funds are delivered, cancellation or recovery may not be possible.
Choosing between banks that supports Zelle ultimately comes down to access and convenience. While the network is broad, access depends on maintaining an account with a participating financial institution. For some consumers, a traditional bank or credit union may meet their needs. Others may prefer platforms designed to support individuals who face barriers to accessing traditional banking services. If Zelle access is important to you, it may be helpful to consider not only which financial institutions support the service, but also which ones best fit your individual needs.

Living in the United States
8 min de lectura
Are you looking for ways to make extra money from the comfort of your home or during your free time? Thanks to technology, it is now possible with just a mobile phone and an internet connection. In this article, we present five apps that will let you earn money quickly and easily.
You can earn money from your phone in the U.S. with paid surveys (Eureka Surveys, Google Opinion Rewards), freelance work (Fiverr), selling used items (Mercari), or driving for Uber or Lyft. With Común, you can receive all of those payments in an account without SSN, without monthly fees, and in Spanish.
1. Eureka Surveys is a platform that lets you earn money by answering surveys in minutes on your own schedule. You will accumulate points that you can redeem for gift cards or cash through PayPal.
2. Google Opinion Rewards is an app created by Google that lets you earn money by answering short surveys. For each completed survey, you will receive a reward redeemable in Google Play.
3. Fiverr is a freelance services platform where you can offer your skills and knowledge in exchange for money. You can find jobs in design, writing, digital marketing, programming, and more. Remember to connect your Común account to Fiverr.
4. Mercari is a buying and selling app where you can sell new or used items. The app keeps a small commission for each sale made.
5. If you have a car and free time, you can take advantage of transportation apps like Uber or Lyft to earn extra money as a driver.
Making money quickly is easier than it seems thanks to these apps. Remember that with Común you get a free checking account and a VISA debit card with access to more than 57,000 ATMs.
Financial Education
8 min de lectura
Registering a business as an immigrant in the U.S. generally involves choosing a business structure, obtaining an EIN from the IRS, and registering with your state. You don't need an SSN to get an EIN — an ITIN or foreign status works for this process.
Starting a business as an immigrant in the U.S. is an exciting step toward financial independence and long-term success. Fortunately, you don’t need U.S. citizenship or a Social Security Number (SSN) to register a business. Many immigrants successfully operate businesses using an Individual Taxpayer Identification Number (ITIN) and other available options. This guide walks you through the key steps to officially register your business, get the right tax IDs, and open a business bank account.
If you choose a Sole Proprietorship, you may need to register a Doing Business As (DBA) name, which allows you to operate under a name different from your personal name. For an LLC or Corporation, you’ll need to check your state’s Secretary of State website to confirm that your chosen business name is available. Each state has specific rules about what names can be used, so ensure yours complies with local guidelines.
Common options include sole proprietorship (simplest, no separation between personal and business liability), and LLC (separates personal assets from business liability, more paperwork).
No — you can obtain an EIN (Employer Identification Number) from the IRS using an ITIN or by mail/fax if you don't have either an SSN or ITIN yet.
Choose a business name and structure, register with your state, obtain an EIN from the IRS, and open a business bank account once you have your EIN and formation documents.
Yes, you can obtain an EIN using an ITIN, or through an alternate IRS process if you have neither.
A sole proprietorship has no legal separation between you and the business; an LLC separates personal assets from business liability but requires more paperwork.
Apply directly through the IRS website or by mail/fax — it's free and doesn't require a lawyer.
Not necessarily for a simple structure like a sole proprietorship, though an LLC may benefit from professional guidance depending on complexity.
It's generally recommended to separate personal and business finances once your business is registered, for cleaner bookkeeping and liability protection.
Your EIN confirmation letter, formation documents (for an LLC), and any state registration certificates.

International Money Transfers
8 min de lectura
For millions of Latin Americans living in the United States, sending money back home is part of everyday life. For many, their families and friends back home often depend on fast and reliable remittances from the United States. Today, there are many service providers for sending money to Latin America available in the market, each offering different advantages and disadvantages and choosing the right one is key to make the most out of your hard-earned money. A useful approach is to understand how remittance pricing works, what factors affect the total cost, and how to compare the services based on your specific needs.
The real cost of a remittance is determined by different elements:
In practice, the exchange rate often has the biggest impact on how much money the recipient actually receives. For example, two providers may advertise similar fees while delivering noticeably different final amounts because of the FX spread built into the exchange rate.
The FX spread is the difference between:
This difference is where some remittance service providers generate revenue. The same reason why two services with the same "$0 fee" can have very different final costs.
Different services work better for different types of users. Here you can find a general overview of the providers most commonly used by the Latino communities in the United States.
Western Union is one of the largest remittance companies in the world, with an extensive cash pickup network across thousands of locations in Latin America.
Strengths:
Limitations:
Ria Money Transfer offers payments from the US to more than 165 countries across the world, with delivery options including cash collection and delivery to either a mobile money wallet or bank account.
Strengths:
Limitations:
MoneyGram is a service provider of international remittances that enables individuals to send and receive money internationally and domestically.
Strengths:
Limitations:
Félix Pago is a WhatsApp-based platform focused on servicing the Latino community in the U.S. to send money throughout Latin America.
Strengths:
Limitations:
Común offers the possibility to open a debit account in the USA and send money home from Común's app or WhatsApp.
Strengths:
Limitations:
Today, the remittance service provider market in the U.S. can be divided into two major categories:
Companies that offer physical networks and cash pickup infrastructure. For example: Western Union, Ria Money Transfer or MoneyGram.
These platforms focus on mobile experience, transparent pricing, digital account management, accessibility for immigrants in the U.S. and some offer Spanish-first experiences. Examples: Común and Félix Pago.
Exchange rates change every day and promotional offers can also change. This is why it's important to compare what's the best service provider for your current situation. If possible, it is recommended to use a tool to have a better perspective on your remittance costs. For example Común has a live calculator at comun.app/compara designed to help you understand the exact conditions of your transfer.
For many immigrants in the United States, choosing the best remittance services is not just based on who offers the best exchange rate. The accessibility to the services can shape the entire experience of sending money. Some people may not have a Social Security Number, a traditional U.S. bank account, or an easy way to verify their identity through conventional financial systems. Language can also play an important role for navigating financial apps especially with customer support and understanding the specific transfer policies. Being able to do financial transactions in a native language can make transactions feel less stressful.
The competitive market landscape in the U.S. makes it possible for Latin American immigrants to compare options for their remittances. Today, you can look beyond the exchange rate and consider factors like Spanish-language support, flexible identification requirements, mobile accessibility and transparency around fees and/or transfer conditions. The best remittance service provider is the one that offers pricing, services and access that fit your needs. Común's app is available in Spanish, accepts more than 100 Latin American IDs and offers transparent fees.
There is no universal "best" remittance provider. The right option depends on how often you send money, where you are sending it, how your recipient receives the funds, and what kind of financial access you have in the United States. Choosing based on your own priorities is often the best path.
Many remittance services offer promotional pricing or preferred exchange rates for first-time users. These promotions can temporarily improve the amount received by your family, but they do not always reflect the long-term cost of using the platform.
For example, some digital services may offer stronger FX rates on the first transfer, while traditional providers occasionally waive transfer fees for new customers. However, the total value still depends on the exchange rate, transfer speed, and delivery method.
Before sending your first remittance, it is important to consider:
To compare exchange rates you can always use a tool, for example, comun.app/compara is designed to help people understand the cost of their transfer.
Access to financial services can vary significantly for immigrants in the United States, especially for people who do not have a Social Security Number. This can make onboarding slower or more complicated for recent immigrants, ITIN holders, or people primarily using foreign identification documents.
Some remittance service providers have adopted more flexible verification models. Común, for example, accepts more than 100 Latin American IDs. It is recommended to check with every institution their specific verification requirements.
People who send remittances every month can benefit more from consistency than from temporary promotions. For frequent senders, it can be useful to review:
Cash pick-up continues to play a major role across many parts of Latin America, especially in smaller cities or rural communities where bank access may be limited.
Traditional remittance companies like Western Union, Ria Money Transfer, and MoneyGram offer large physical networks that allow recipients to collect money in person at supermarkets, convenience stores, banks, and local partner locations.
Before choosing a provider, it is helpful to verify:
In some cases, the best service is simply the one your recipient can access easily. Común offers cash pick ups with options in some stores and banks.
Over the past years, mobile-first experiences have become popular given the convenience of being able to send remittances from one's mobile phone.
Digital-first services can offer:
Platforms like Común and Félix Pago are examples of services designed around mobile experiences for Latino immigrants. For people who feel more comfortable managing their transfers from their phones, these platforms can feel faster and more convenient.
There is no single service that is always the cheapest. Costs depend on exchange rates, transfer fees, destination country, payment method, and whether you qualify for a first-transfer promotion. The best way to verify your exact case is to compare providers.
The FX spread is the difference between the real market exchange rate and the exchange rate offered by the remittance provider. A weaker exchange rate can reduce the amount your recipient receives.
The best way is to compare the total recipient amount, exchange rate, fees, and promotional conditions before sending money. Some service providers offer tools that calculate the costs before sending the remittance. Común's live comparison calculator is designed to help users verify this information in real time.
No. Some remittance providers specialize in bank deposits or digital wallet transfers, while others maintain extensive cash pickup networks across Latin America. Before sending money, it is important to confirm how your recipient prefers to receive funds and whether pickup locations are accessible in their area.
Each provider sets its own exchange rates based on market conditions, operating costs, transfer corridors, and promotional strategies. Because rates can change daily, comparing providers before each transfer can help users better understand the total cost of sending money.
The remittance industry has changed significantly over the past decade, today sending money to Latin America is no longer limited to one type of service or provider. Immigrants in the United States can choose between traditional cash pickup networks, digital-first platforms, and hybrid financial services depending on what works best for their families.
For many people, the real value comes from the full experience from the convenience of usage, accessibility to the services and knowing exactly how much money will arrive can matter just as much as costs. Común offers transparent pricing, an app available in Spanish and a comparison tool that helps users review transfer costs before sending money.

Community
8 min de lectura
Común is a digital financial platform designed specifically for the immigrant community in the United States, letting you open an account with Latin American IDs, no Social Security Number required.
Común does not have branches, but it has a team that supports its customers 24 hours a day, 7 days a week, from the comfort of their homes, in three different languages.
Building a better future for immigrants in the U.S. is a core principle of Común’s mission. Accessible and easy-to-understand banking options are a key part of the immigrant journey. However, the options are scarce.
Complex, cumbersome, and expensive options are the norm. Activities that may seem trivial and intuitive to those born in the U.S. are overwhelming and confusing for a newly arrived immigrant. Everything from setting up direct deposit with an employer to sending money home, making payments for goods and services, or understanding how to build a credit score seems too complex for anyone who has never had to do this in the U.S., let alone at all.
Hidden fees and costly charges add another layer of stress when starting a financial life in the U.S. Between minimum account balances, monthly fees, overdraft charges, large check deposit fees, extortionate international transfer fees, and everything else, maintaining and using a bank account in the U.S. can be expensive. For manual laborers, this can represent a significant percentage of their wages.
The physical locations of traditional banks can also be scarce in some areas. Since opening a bank account or depositing a check or cash into the account must be done at a branch, this is a significant burden for someone living in a remote area. Many immigrants, sometimes working on remote farms or factories, live miles away from the nearest bank branch. Transportation costs to those branches add to the already high fees of using and maintaining an account.
Even if the banking services provided were more intuitive, digital, and lower cost, another major barrier remains. Obtaining the necessary documentation to open a bank account can also make access to fair and simple financial services difficult. Immigrants fortunate enough to have work authorization still need to gather important documentation that is not always available to them. For those who have come to the U.S. seeking asylum or better work opportunities through a more unconventional path, the documents required to open an account are often prohibitive.
Building a 100% digital banking platform to solve the issues mentioned above is part of what Común seeks to achieve because we believe in helping unlock social mobility. But a digital, low-cost, and intuitive platform is not enough. To navigate this process, immigrants need help, and help is best found in a Community that understands them when they need it most.
That is why not only our customers are part of our Community, but also the people who help them 24 hours a day, 7 days a week through our app, social media, WhatsApp, or by phone. Beyond solving an immediate problem, the support provided goes further. It teaches and educates, empathizes, and strives to foster a sense of Community among people who understand them, in terms they comprehend and in the language they speak. This is the core of true digital community banking. Our team helps them set up direct deposit, get refunds for charges they disagree with, and everything else.
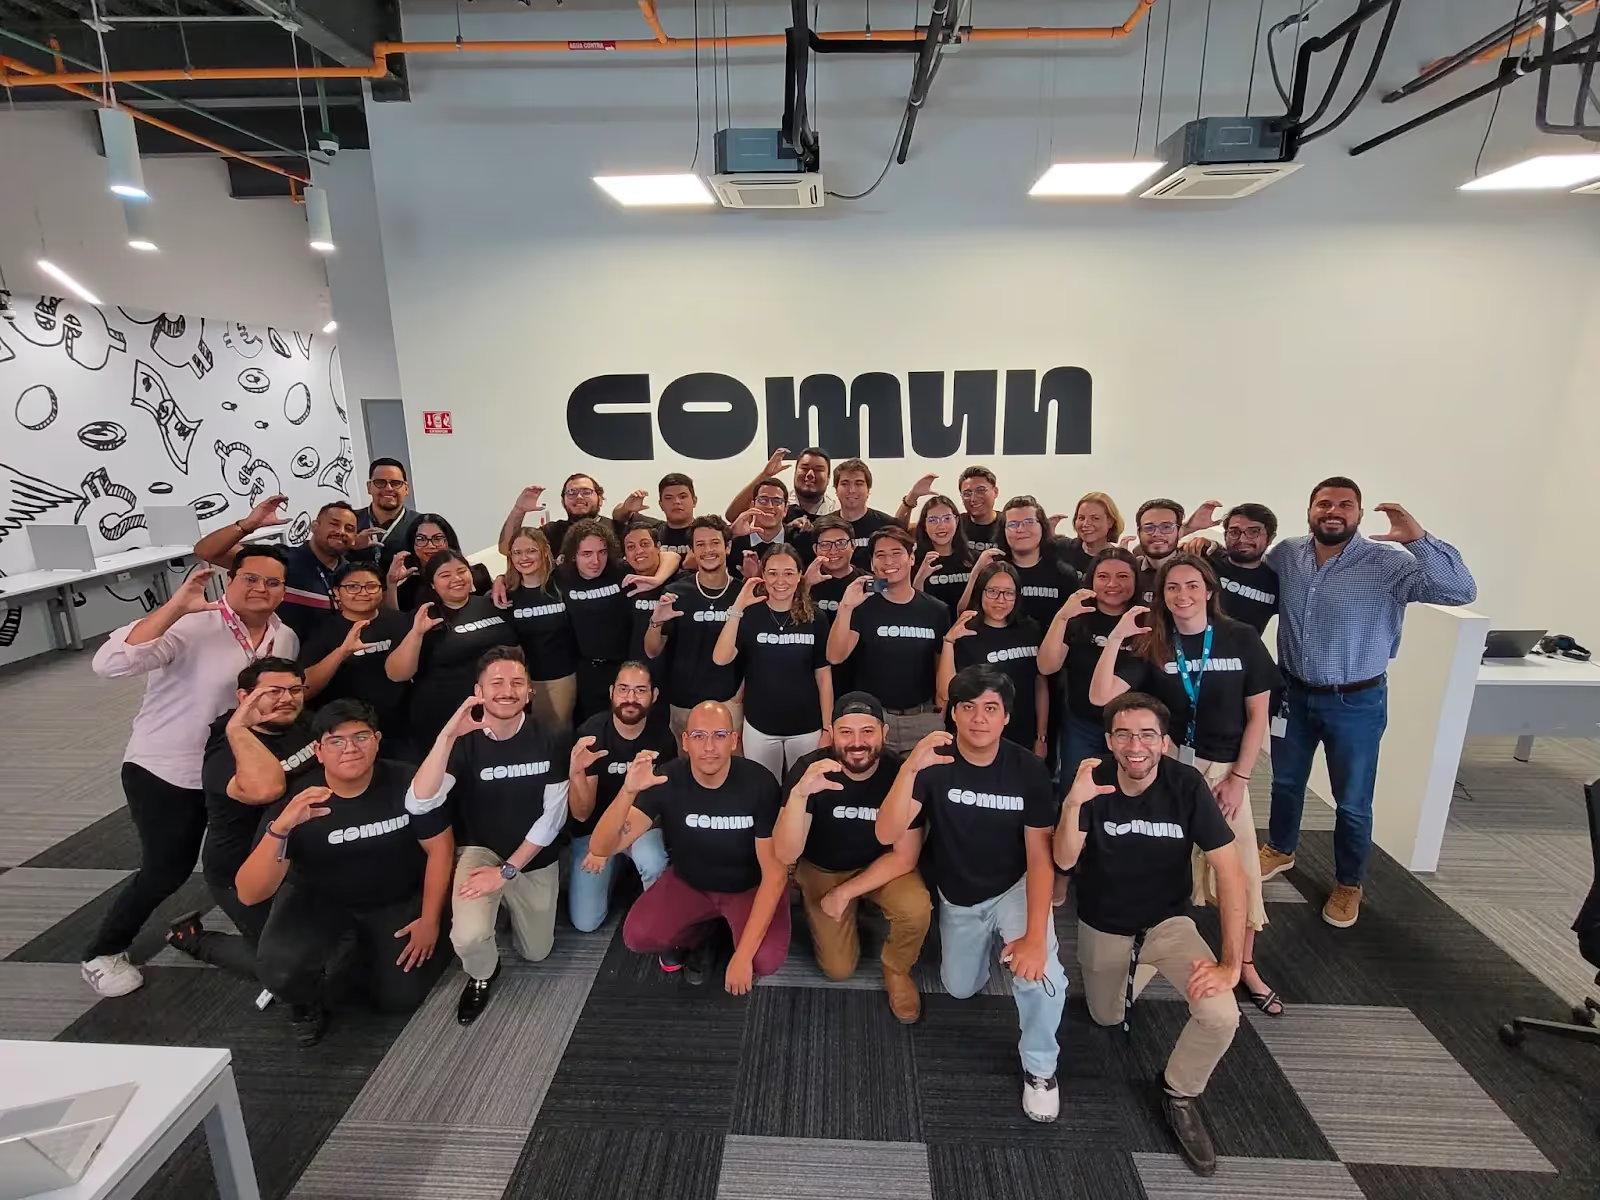
At Común, the first step in this journey has already begun. Our team in Mérida, Mexico, is part of our Community and the one we seek to serve. They are an extension of our mission and our digital platform, and a necessary ingredient in unlocking social mobility for millions of immigrants in the U.S.
Común accepts over 100 Latin American IDs (passport, consular ID, among others), doesn't require an SSN or ITIN, and doesn't charge a monthly fee or require a minimum balance.
With 100% Spanish-language support, an account opening process that takes minutes, and features built for common community needs, like low-cost remittances and cash deposit without needing a prior bank account.
A checking account with a Visa debit card, international remittances starting at $2.99, cash deposit at over 88,000 locations, and direct deposit.
For the Latin American immigrant community in the U.S. looking for accessible financial services without traditional documentation barriers.
Over 100 Latin American IDs, including passports and consular IDs — no SSN or ITIN required.
No, there's no opening fee, monthly fee, or minimum balance required.
Yes, the app and customer support are available in Spanish.
The process takes about 3 minutes, with instant approval in most cases.
Yes, starting at $2.99 per transfer, with your first transfer at no cost.

Financial Education
8 min de lectura
If you suspect your account was compromised, act immediately: lock your card from the app, review your recent activity, and contact support. With Común, locking your card is instant and support is available 24/7.
Recognizing the Signs of Identity Theft and a Compromised Account
The first step is recognizing the signs that your bank account may have been compromised. Unusual or suspicious transactions, unexpected changes to your account details, and alerts or notifications from your bank that you didn't trigger are clear indicators. Getting text or email alerts about activity you didn't do can also mean your account has been hacked. Staying alert and regularly reviewing your account activity can help you catch these signs early if your bank account is hacked.
Immediate Actions to Take When You Notice Suspicious Activity
1. Contact Your Bank Immediately. If you suspect your account has been compromised, call your financial institution directly. Most banks have a dedicated fraud department that can freeze your account to prevent further unauthorized transactions. Acting quickly is crucial to protecting your hard-earned money.
2. Change Your Account Passwords. Immediately change your online account passwords and any other online accounts linked to your financial information. Make sure your new passwords are strong, unique, and different from passwords you've used before.
3. Monitor Your Account for Further Activity. Keep a close eye on your account for any additional suspicious activity. Regularly review your bank statement and account activity, and report any discrepancies to your bank. Setting up text and email alerts for transactions can help you stay on top of your account status.
Learn how to monitor your accounts here
4. Report the Fraud. File a report with your bank's fraud department. Also report the incident to the Federal Trade Commission (FTC) and consider filing a police report. This can help protect your credit report and prevent further identity theft.
Additional Precautions: Enable Two-Factor Authentication
[Image: homepage of bank app — keep image as-is]
To Prevent Future Incidents, Take These Additional Security Measures:
1. Secure Your Devices. Make sure your devices are protected with the latest antivirus protection and security updates. Avoid using public Wi-Fi for online banking.
2. Enable Two-Factor Authentication. Turn on two-factor authentication (2FA) for an extra layer of security on your bank accounts and other online accounts. This makes it harder for unauthorized users to access your accounts.
3. Be Careful What You Share. Be careful about the information you share online, and avoid providing sensitive information like your Social Security number through unsecured channels. Watch out for phishing emails and malicious links that can lead to a compromised account.
4. Use Strong, Unique Passwords. Make sure to use strong, unique passwords for all your other accounts. Avoid reusing the same password across multiple accounts, and change your passwords regularly.
5. Set Up Fraud Alerts. Consider setting up fraud alerts with your bank and credit bureaus. This can help you stay informed about any suspicious activity on your accounts.
We'll show you how to open a bank account in the United States
Común's Security Features
At Común, we prioritize the security of our customers' accounts, just like leading financial institutions. Our platform includes advanced security measures like encryption and real-time monitoring to protect your financial information. If you ever suspect fraudulent activity, our customer service team is available to help you right away. Just send us a message through the Común app, and we'll walk you through the steps needed to secure your account.
Open your bank account¹ in 3 minutes with your country's ID²
Conclusion
Quick action is crucial when it comes to a compromised bank account. By recognizing the signs, taking immediate action, and using strong security features, you can protect your finances and regain control of your accounts. Stay alert and proactive to keep your bank account secure. Remember, responding quickly can prevent further losses and ensure your money stays in your hands.
Transactions you don't recognize, unexpected changes to your account details, or alerts about activity you didn't start.
Lock your card instantly from the app, review your recent activity, and contact support to report the suspicious activity.
Through in-app chat, email, phone, or WhatsApp, available 24/7.
Common signs include transactions you don't recognize, changes to your contact details, or alerts about activity you didn't start.
Yes, you can lock it instantly from the app without needing to call support first.
Review your recent activity in the app to identify any transaction you don't recognize.
Contact support through chat, email, phone, or WhatsApp, available 24/7.
Reporting right away reduces your liability; exact protections depend on the circumstances.
Turn on app notifications, review your activity regularly, and never share your access codes, even with someone claiming to represent Común.

International Money Transfers
8 min de lectura
Do you really know what remittances are? They are international money transfers made by people living and working abroad to family members or recipients in their home country.
For Latin American immigrants living in the United States, sending remittances is a crucial matter, as is having efficient financial services that allow them to send money to their families and friends quickly, safely, and at low cost.
According to recent sources, the flow of remittances from Mexico to the United States fell 12.4% year over year, which is attributed to recent immigration measures imposed by that country. For this reason, it is important that migrants have international money transfer services that understand their needs.

For the families of migrant workers in the United States, remittances represent much more than a simple transfer of money, as they often become the main support for millions of people in Latin America.
These Are the Main Reasons to Send Remittances:
This category includes basic expenses such as food, rent, utility payments, and everything related to daily costs, highlighting the importance of remittances for recipient families.
Includes payment of tuition, school supplies, transportation, preschool fees, and computing tools such as laptops or desktop computers.
If any family member requires specialized medical care, remittances play a central role in covering hospitalization, medications, treatments, and more.
It is also common for migrants to use remittances to build or renovate their family homes, thereby improving their quality of life.
Remittances may also be useful to cover unexpected travel expenses, related to unforeseen illnesses, flight cancellations, or unplanned charges.
Currently, there are several remittance service options you can rely on to send money to your relatives.
Traditional banks, such as Bank of America and Wells Fargo, allow you to make remittance transfers through their digital banking services or directly at branches.
There are also specialized sending agencies, such as Western Union, one of the most widely used and longest-standing remittance services in the United States, with a global presence in more than 200 countries.
The information that traditional banks and agencies will generally require to send money includes:
Finally, you can choose digital platforms, which allow you to send money through mobile apps and, in general, offer more competitive options regarding costs and delivery times.
Común is one of these platforms, integrating the fintech experience with various benefits, such as a digital account and an easy to use mobile app, that is available in Spanish. Común accepts more than 100 qualified official IDs from your country of origin to open an account and offers different options for receiving money: into a local bank account or cash pickup. With Común, send money to your relatives for clear and competitive rates, from $2.99 USD and send up to applicable limits.
These Are the Characteristics of Each Available Remittance Sending Option:
Traditional banks are a safe option to send money through wire transfer. The advantage is that they are fully established institutions in the U.S. financial system.
However, they have certain limitations, such as high fees, which can reach 60 USD depending on the bank. Additionally, transfers also tend to be slower, taking up to 5 business days.
To access this service, it is necessary to open a bank account at a traditional U.S. bank, or resort to sending cash directly at a branch.
Specialized agencies for international money transfer, such as Western Union, are also a reliable alternative you can use.
However, fees are usually high and exchange rates less competitive, similar to traditional banks. Although delivery times tend to be shorter.
If you are looking for an option to make international bank transfers, digital platforms are a great option. In addition to more accessible opening requirements, they offer far more competitive fees compared to the two previous alternatives.
Remember that Común offers you a comprehensive digital platform to connect with your loved ones in a simple and fair way.
The cost of sending remittances depends on three main factors:
For example, if the dollar price is 18 Mexican pesos, and the remittance service offers it at 17.50, when sending 500 USD, the total amount to be received will be reduced by 250 pesos.
To ensure your family receives the maximum amount possible, we recommend following these tips.
The ideal choice is a provider that uses the real exchange rate or as close as possible. Otherwise, your recipient will receive a significantly smaller amount.
Understanding sending fees can be confusing, since several services use ranges that vary according to numerous criteria. The recommended approach is to look for a provider that offers fixed fees and with no hidden costs.
Remember that, in addition to the sending fee, you must consider the exchange rate and how much the amount to be received is reduced after applying this margin.
Check your recipient’s information and make sure it is written correctly.
It is important to choose a service capable of answering your questions in your language and understanding your needs as a migrant.
Every month, millions of dollars are sent from the United States to Latin America, representing an emotional and financial bridge between immigrant families and their homes, for whom remittances are a primary source of income.
Before choosing a remittance service, don’t forget to check the total amount your household will receive, considering the fee, exchange rate, and possible receiving charges. We recommend choosing a financial solution with transparent costs, support available in Spanish, and you can open your account with qualifying official ID from your country of origin.
Discover Común, the comprehensive platform that offers you low fees, with fees starting from $2.99, and send up to the applicable limits, and support available in Spanish. Open your account today and connect with your loved ones, send them money transparently.
Remittances usually have a validity period established by the provider. Once that period expires, the money is not lost but the transaction may be canceled. In such cases, the sender may reissue it or request a refund depending on the provider’s policies.
The main difference between the two lies in their intended purpose. Remittances are money transfers with a personal motive, commonly used to send money to relatives in other countries, whereas the purpose of a bank transfer can vary, ranging from commercial to personal payments, among others.


Comun is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank; Member FDIC. The Comun Visa® Debit Card is issued by Community Federal Savings Bank, pursuant to a license from Visa U.S.A Inc. and may be used everywhere Visa Cards are accepted.
Comun is a fintech company and not a bank or licensed money transmitter.
* Results may vary. For a complete list of eligible IDs and application requirements, follow this link.
^ No minimums, no maintenance fees. ATM or transfer fees may apply. See app for fee details.
‡ Direct deposit funds are typically available when we receive the payment file, up to two days before the scheduled payment date. This early availability is not guaranteed.
** A service provided by Service UniTeller, Inc. Service UniTeller, Inc. is licensed in all states that require a license. Remittance fees start at $2.99 but may vary. Please check the app for more details. Comun Inc. may earn revenue from the conversion of foreign currencies.
† Funds in your account are FDIC insured up to $250,000 by ownership category through Community Federal Savings Bank (CFSB), Member FDIC, in the event CFSB fails.