
Community
What You Need to Open an Account at Comun¹ 4
Accessible, fee-free digital banking platform for the immigrant community, with bilingual support and international deposit and transfer facilities.
8 min read

Olivia Rhye
04 Jun 2025
Unmatched Ease of Opening an Account
Opening a checking account with Comun is simple and hassle-free, addressing the barriers to financial exclusion typically faced by the immigrant community. Accepting over 100 forms of identification², including social security numbers from Latin American countries, Comun ensures that immigrants have access to essential banking services. The application process is quick, taking less than 5 minutes, and is free of additional or hidden fees, minimum balance requirements or monthly commissions. This inclusiveness is central to Comun's mission of fostering financial stability and growth.
Mobile Deposit Options
ComunComun offers a convenient mobile deposit feature that allows users to deposit cash at more than 88,000 locations in the United States, including major retailers such as Walgreens, Dollar General and Walmart. This extensive network ensures that users can easily find a deposit location near them, making the process of adding money to their accounts simple and hassle-free.
Traditional Banking: Although many traditional banks offer mobile deposit options, they often restrict these to check deposits through a mobile app. Cash deposits typically require a visit to an ATM or bank branch, which can be less convenient and more time-consuming than Comun's extensive cash deposit network.
Utility in Today's World: In today's fast-paced environment, the flexibility to deposit cash in a wide range of accessible locations is invaluable, especially for individuals who may not have easy access to traditional banking services or who work non-traditional hours when banks are closed.
International Remittances
ComunComun excels in facilitating international remittances⁴, allowing users to send money abroad quickly and with lower fees compared to many traditional banks and remittance services. The process is enhanced with real-time notifications, keeping the sender informed from the moment the money is sent until it is received.
Traditional Banking: Traditional banks generally offer international transfer services, but these can be expensive and slow, with transfers sometimes taking several days to complete. In addition, the fees associated with traditional bank remittances can be significantly higher.
Usefulness in Today's World: In a globalized economy, the ability to send money across borders quickly and affordably is crucial. Many families rely on remittances for financial support, and businesses need efficient ways to handle international transactions. Comun's streamlined and cost-effective service effectively meets these modern demands.
Advance Salary Access
Comun: Comun offers the ability to connect wages to the application and receive payment up to two days in advance³. This feature incurs no additional fees, providing significant relief during financial emergencies or when planning ahead.
Traditional Banking: Some traditional banks have begun to offer similar features, but they are often tied to specific types of accounts or require a minimum balance. The accessibility and ease of use of early access to Comun's salary is not always matched in traditional environments.
Usefulness in Today's World: With the rise of gig economy jobs and irregular pay schedules, having early access to wages can provide a buffer against financial instability. This feature is particularly valuable for those living paycheck to paycheck, offering a cushion that can help avoid overdraft fees and late payments.
Unlike traditional banking institutions, Comun's innovative features are designed to meet the needs of today's diverse and mobile population, particularly benefiting the immigrant community in the U.S. By providing services that offer greater convenience, lower costs and greater accessibility, Comun not only addresses common challenges faced by its users, but also empowers them toward greater financial freedom and stability. As we move toward a more interconnected and fast-paced world, the importance of responsive and inclusive financial services continues to grow, something Comun is uniquely positioned to offer.
Robust Security and Customer Support
Security and customer support are paramount at Comun. With FDIC-insured accounts and Visa protection on virtual Visa debit card transactions, Comun customers can manage their funds with confidence. Innovative security features such as biometric logins and instant transaction notifications keep your money safe. In addition, Comun offers 24/7 customer support in English and Spanish, ensuring that help is always available in your preferred language.
Commitment to Zero Fees and Upward Mobility
Comun stands out not only for offering zero fees for account opening, monthly maintenance or minimum balances, but also for its commitment to helping its users move up the financial ladder. Comun acts as a financial partner, supporting financial transactions without the burden of excessive fees. This commitment aligns with the goal of enabling upward mobility for immigrants, who contribute significantly to the U.S. economy.
Customized Features and Benefits
Comun goes beyond traditional financial services by offering features designed to meet the unique needs of the immigrant community. Users can send money abroad with low or no fees, deposit cash at more than 88,000 locations nationwide, including free ATM withdrawals, and connect their accounts to popular payment apps such as Zelle, CashApp and Venmo. Comun's platform also allows customers to receive their paychecks up to two days early through direct deposit, further enhancing their financial flexibility and stability.
Conclusion
Comun is not just a financial services provider, but a platform dedicated to transforming the banking experience for immigrants in the U.S. With its user-focused design, commitment to financial freedom and robust features, Comun is destined to become a vital tool for achieving financial stability and growth for its users. Whether you are looking to manage your daily finances or send money to loved ones abroad quickly and securely, Comun offers a reliable, inclusive and efficient banking solution.
Foundational Moment: Did you know?
Founded by entrepreneurs Mark Selcow and Andres Santos in New York, Comun was built to empower families and enable upward mobility, particularly for the immigrant family. The company has garnered significant investment from prominent firms such as Costanoa Ventures, FJ Labs and South Park Commons, underscoring the tremendous opportunity to serve the financial needs of immigrant families and improve the lives of every individual.
About Común
Común aims to support the Latino community in the United States. It offers a debit account that can be opened with more than 100 valid Latin American IDs and an app available in Spanish.
Visit Común's website or download the app for free to learn more about the full offer and applicable terms.
Olivia Rhye
Community Partner

Checking account
What Is a Bank Account and What Are the Benefits of Having One?
8 min de lectura
A bank account is a financial account a customer holds at a bank. A bank account lets customers deposit and withdraw money, as well as write checks. That's why it's also called a checking account.
The advantages of having a bank account include:
- Easy access to your money — 24/7 banking access through the bank's website or app
- No need to carry cash
- The ability to earn interest on your deposits
- Building a credit history, which can matter when you want to apply for a loan in the future
How Do You Open a Bank Account?
Opening a bank account is relatively easy. You'll need to provide some personal information, like your name, date of birth, and address. You'll also be asked for ID — usually a Social Security Number (SSN) is enough. More modern banks, like Común, let you replace your SSN with a passport or consular ID. You may also be asked for documentation proving your address.
The Different Types of Bank Accounts Available
There are different bank accounts to choose from. The most common type is the checking account, which lets you deposit and withdraw money and write checks. A checking account is a great option if you want easy access to your money without carrying cash, since your account's debit card lets you pay at any business.
Another common type of bank account is the savings account. Savings accounts let you save money and earn interest on your deposits. It's a great option if you want to build up your savings over time.
There are also several specialized bank accounts, like accounts for students, seniors, and businesses. Be sure to research the different bank accounts available and choose the one that best fits your needs.
How to Manage a Checking Account Online
Many bank customers choose to manage their bank account online. You can do this through the bank's website or app. Managing your bank account online lets you access it 24 hours a day, 7 days a week.
Some things you can do online include:
- View your account balance and transaction history
- Transfer money between savings and checking accounts
- Pay bills
- Pay your credit card
- Deposit checks
- Set up banking alerts for specific events, like a low balance or a large deposit
What Does It Cost to Open a Bank Account in the United States?
Some accounts, like the one Común offers, come with no monthly fee and no minimum balance requirement. However, many banks do charge fees. These include some of the most popular banks in the United States: Bank of America, JPMorgan Chase, Citigroup, and Wells Fargo. Here are some of the fees they charge:
- Monthly service fee
- Minimum balance requirement
- Overdraft fee
- Check-cashing fee
Certain banks also limit Spanish-language support in their digital interfaces or customer service centers. Be sure to research the fees charged and the language support offered before opening an account with any bank.
FDIC Backing
The Federal Deposit Insurance Corporation (FDIC) is a government agency that insures consumer deposits at banks in its network. It's important to choose a bank with this backing, since you'll have up to $250,000 of your funds insured by the U.S. government if your bank fails.
The Benefits of Común
At Común, you'll find a checking account with no monthly fee and no minimum balance, in Spanish (from the mobile app to customer support), with the flexibility to apply using your passport, no matter your nationality. Opening an account is very easy, and you'll have 24/7 access, along with the ability to pay bills or deposit checks. Común is FDIC-insured, so your funds are protected up to $250,000 USD.
As with any financial service, be sure to research the different options available and choose the one that best fits your needs.
Financial Education
How to Call Colombia from the United States in 2025
8 min de lectura
How to call Colombia from the U.S. in 2025 easily and affordably
The Colombian community has a strong presence in the U.S., with many immigrants arriving each year to visit, live, study, and work.
Staying in touch with family across borders matters. That’s why it’s useful to know the different ways to make international calls from the U.S. While it can seem tricky, it’s easy if you have the right codes.
If you want to call loved ones back home in Colombia, below you’ll find step-by-step dialing instructions from the U.S., examples, and a full area-code table.
Basic steps to call Colombia from the USA
Before calling anyone in Colombia, know the sequence: international prefix + country code + local number.
1. Enter the U.S. exit code – 011
This is the international prefix from a landline. If you’re using a mobile phone, use the “+” sign instead.
2. Dial Colombia’s country code – 57
This identifies Colombia in the international telephone system.
3. Dial the local number in Colombia
For landlines include the city area code. For mobile phones, dial the full 10-digit mobile number.
Examples:
- Call Bogotá (landline): 011 + 57 + 1 #######
- Call Medellín (landline): 011 + 57 + 4 #######
Area codes and dialing examples for Colombian cities
There’s a difference between calling a landline and a mobile in Colombia from the U.S.: landlines need the regional area code; mobiles are dialed using the “+” format on cell phones.
Below you’ll find the area codes for Colombia’s main cities to ensure you dial correctly when contacting your family.
City
Area code
U.S. dialing example
Bogotá
1
011 57 1 #######
Medellín
4
011 57 4 #######
Cali
2
011 57 2 #######
Barranquilla
5
011 57 5 #######
Cartagena
5
011 57 5 #######
Bucaramanga
7
011 57 7 #######
Pereira
6
011 57 6 #######
Cúcuta
7
011 57 7 #######
Santa Marta
5
011 57 5 #######
Manizales
6
011 57 6 #######
Digital alternatives and budget-friendly plans to call Colombia
The phone is a favorite way to bridge distances and stay in touch with loved ones across borders.
Years ago, international rates were expensive, making frequent calls home difficult.
Today, digital options have lowered costs and made cross-border communication much easier.
Below we show some affordable options to help you stay in touch with the people who matter most.
- Internet-voice apps (VoIP):
Mobile apps are hugely popular worldwide. They enable texting, voice notes, and voice/video calls over Wi-Fi or data—significantly cutting costs.
WhatsApp is the most popular, and other solid options include FaceTime, Google Voice, and Skype.
- International calling plans from your U.S. carrier:
If you prefer traditional calling, look for an international plan from your U.S. provider with minutes to Colombia—great for frequent calls.
You can pick plans with minutes to landlines and mobiles or Colombia-specific bundles.
Examples of U.S. carriers include AT&T Prepaid, T-Mobile, Verizon, and Ultra Mobile. Options range from unlimited international add-ons and prepaid plans with international calling to limited-minutes bundles and mixed data/calling packages.
- Prepaid calling cards as a flexible option:
If you’re in the U.S. for only days or weeks, a mobile plan may be overkill. A prepaid calling card can be ideal—no PINs in many cases and you only pay for the minutes you use.
Stay connected with family in Colombia with Común
As you’ve seen, calling Colombia from the U.S. is straightforward—just use the correct codes. You can also choose affordable alternatives like mobile apps or prepaid cards.
Staying in touch shows care and support. It also helps to have accessible services to send money and support their well-being.
Meet Común your direct link to the ones you love!
- International money transfers: the simplest way to send remittances to family with fair, transparent pricing.
- Común’s mobile app in Spanish and English: open an account with 100+ eligible official IDs and get support in your language.
Ready to revolutionize how you connect with your finances?
Open your Común account today and complement your calls with a fintech platform that supports your financial life in the U.S.
Frequently Asked Questions (FAQ)
Still have questions? Check our FAQ section below.
What if I don’t dial 011 or “+”?
If you don’t dial 011 from a landline or “+” on mobile, your call won’t be recognized as international and will fail as a local call.
What’s the cheapest way to call Colombia from the USA?
There are several affordable options—apps like WhatsApp, Skype, or Google Voice; prepaid calling cards; or an unlimited international plan. The best choice depends on your habits and how often you call.
How much does it cost to call Colombia from the USA?
Costs vary by method. For example, AT&T offers unlimited add-ons around $15/month and Verizon offers 300 minutes for about $10/month.

Immigration
Bank Fees for Immigrants: Common vs. Competitors
8 min de lectura
For immigrants in the U.S., bank fees can amount to hundreds of dollars a year. Común stands out by offering a monthly-fee-free account, no minimum balance, and no SSN requirement. Compared with competitors like Seis and Majority, Común eliminates fixed fees while still providing full services in Spanish.
Choosing the right bank account can save you hundreds of dollars a year. For the immigrant community in the U.S., comparing fees is especially important because many traditional accounts charge fees that directly affect the monthly budget. We analyzed the main options available.
Fees at Traditional Banks
Major U.S. banks such as Bank of America, Chase, and Wells Fargo charge between $6 and $25 per month to maintain a checking account, with minimum balance requirements of $1,500 to $25,000 to avoid those fees. They also charge overdraft fees ($35 per transaction), out-of-network ATM withdrawal fees ($2.50-$5 per withdrawal), and international transfer fees ($25-$45 per wire transfer). For a newly arrived immigrant without credit history or a high balance, these costs add up quickly.
Común: No-Fee Account for Immigrants
Común offers a checking account with no monthly fee, no minimum balance required, and no overdraft penalty in many cases. It does not require an SSN — it accepts a passport, consular ID, and more than 100 Latin American IDs. Customer service is completely in Spanish. Account opening takes minutes from a mobile phone. It includes Zelle compatibility for free, instant domestic transfers. It is the option designed specifically for the Latino community in the U.S.
Majority: Monthly Membership with International Benefits
Majority charges $5.99 per month as a base membership (down from $14.99). In return, it offers unlimited international calls to selected countries, roaming mobile data in more than 50 countries, and discounts at participating merchants. If you actively use international calling and travel benefits, the membership may be worth it. However, if you only need a basic bank account, you are paying for services you may not use.
Seis: Account for Visa Workers
Seis is designed for expats and visa workers in the U.S. It offers an account without an SSN using a visa and passport. Fees vary by plan: the basic account has limits on the number of free transactions. It is more geared toward professionals with work visas (H-1B, L-1) than the immigrant community at large. Its interface is available in multiple languages, including Spanish.
Direct Fee Comparison
In terms of monthly fee, Común charges $0, Majority charges $5.99/month, and traditional banks charge between $6 and $25. The minimum balance requirement is $0 at Común, $0 at Majority, and between $1,500 and $25,000 at traditional banks. Regarding SSN requirement, Común does not require it, Majority does not either, while traditional banks generally do. All three have FDIC or equivalent deposit protection.
Which Option Is Best for You?
If you are looking for the account with the lowest total fees and do not need unlimited international calls, Común is the most economical option. If you travel frequently or call abroad often, Majority’s membership may be worth it. Traditional banks only make sense if you already have the required minimum balance or if you need specific services such as mortgages or investment accounts.
Frequently Asked Questions About Bank Fees
What bank fees are most common in the U.S.?
The most common are: monthly maintenance fee ($6-$25), overdraft fee ($35 per transaction), out-of-network ATM fee ($2.50-$5), and international wire transfer fees ($25-$45). Digital banks like Común eliminate most of these fees.
Can I avoid bank fees at a traditional bank?
Yes, usually by maintaining a monthly minimum balance (which varies by bank and account type), receiving direct payroll deposit, or being a student. However, for immigrants without credit history or with variable income, meeting these requirements can be difficult at first.
Are ATM fees unavoidable?
No. Multiple digital banks offer free access to ATM networks (Allpoint, MoneyPass) with thousands of fee-free locations across the U.S. Común provides access to fee-free ATMs within its network. Outside the network, typical charges are $2.50-$5 from the ATM plus whatever your bank charges.
What is an overdraft fee and how can I avoid it?
An overdraft fee occurs when you spend more money than you have in your account and the bank covers the difference by charging you a penalty (typically $35). You can avoid it by activating low-balance alerts, linking a savings account as backup, or choosing a bank that does not charge overdraft fees — some digital accounts decline the transaction instead of charging a penalty.
Is it worth paying a monthly membership for a bank account?
It depends on the included benefits. A $5.99-$14.99 monthly membership may be worth it if it includes services you actively use (international calling, travel insurance, cashback). If you only need an account for deposits, payments, and transfers, a free account like Común is more cost-effective.

Living in the United States
Back to School in the U.S.: A Guide for Immigrant Families
8 min de lectura
Starting a new school year in the United States can involve several administrative and financial tasks. Enrollment requirements, school supply lists, transportation arrangements, meal programs, and extracurricular activities can vary between districts and schools.
For many immigrant families, the process may also involve adapting to a school system that works differently from those in Mexico, Colombia, Guatemala, El Salvador, Honduras, and other countries. Understanding how schools operate, what documents are typically required, and how to prepare financially can make the transition smoother.
This guide explains what to expect during the back to school season in the U.S., how school enrollment works, what supplies children may need, and how to prepare for the school year with confidence.
When does the school year start in the U.S.?
Unlike some countries that follow a national academic calendar, school start dates in the United States are generally determined by states, school districts, and local education authorities.
Most public schools begin classes between early August and early September.
The table below shows common start periods for several major states during the 2026 school year.
| State | Typical 2026 school start period |
|---|---|
| Alabama | Early August |
| Alaska | Mid-August |
| Arizona | Late July to early August |
| Arkansas | Mid-August |
| California | Early to mid-August |
| Colorado | Mid-August |
| Connecticut | Late August to early September |
| Delaware | Early September |
| Florida | Early to mid-August |
| Georgia | Early August |
| Hawaii | Early August |
| Idaho | Late August |
| Illinois | Late August |
| Indiana | Early to mid-August |
| Iowa | Late August |
| Kansas | Mid-August |
| Kentucky | Early to mid-August |
| Louisiana | Early August |
| Maine | Early September |
| Maryland | Early August |
| Massachusetts | Late August to early September |
| Michigan | Early September |
| Minnesota | Early September |
| Mississippi | Early August |
| Missouri | Late August |
| Montana | Early September |
| Nebraska | Mid-August |
| Nevada | Early August |
| New Hampshire | Early September |
| New Jersey | Early September |
| New Mexico | Early August |
| New York | Early September |
| North Carolina | Late August |
| North Dakota | Late August |
| Ohio | Late August |
| Oklahoma | Mid-August |
| Oregon | Early September |
| Pennsylvania | Late August |
| Rhode Island | Early September |
| South Carolina | Late August |
| South Dakota | Mid-August |
| Tennessee | Early to Mid-August |
| Texas | Early to mid-August |
| Utah | Mid-August |
| Vermont | Early September |
| Virginia | Mid to late August |
| Washington | Early September |
| West Virginia | Late August |
| Wisconsin | Early September |
| Wyoming | Late August |
Source: https://us-school-calendar.com/first-day-of-school-2026
The school year generally runs from August or September through May or June. Winter break, spring break, teacher workdays, and holidays are scheduled throughout the year.
Because school calendars can differ even within the same city, families should always verify dates directly with the local school district.
What differentiates the U.S. school system from those in Latin America?
One of the most noticeable differences is the strong role of local school districts. Curriculum decisions, school calendars, transportation policies, and enrollment procedures can vary from one district to another.
Schools are generally organized into:
- Elementary school
- Middle school or junior high school
- High school
Grade levels may differ slightly depending on the district.
Another difference involves parental communication. Schools frequently use online portals, email notifications, text messages, and mobile applications to share grades, attendance records, schedules, and announcements.
Parents may also encounter:
- Parent-teacher conferences
- School volunteer opportunities
- Individual learning plans
- English language support services
- After-school activities and sports programs
Students who arrive from another country may qualify for English learner services designed to support language development while continuing their academic education.
How to enroll your children: documents and process
Most public schools ask families to provide documents during enrollment that are typically used to confirm a child's age, home address, vaccination history, and prior education.
Commonly requested documents include:
- Birth certificate
- Passport
- Proof of address
- Immunization records
- Previous school records or transcripts when available
- Parent or guardian identification
Enrollment can be completed online, in person, or through a district enrollment center.
One of the most important facts for immigrant families to understand is that children have a constitutional right to attend public elementary and secondary schools regardless of their immigration status. This protection comes from the U.S. Supreme Court decision in Plyler v. Doe
As a result, public schools generally cannot deny enrollment solely because a child or parent lacks immigration documentation.
School districts may still request documents that establish residency within the district and verify a child's age, but immigration status is not a requirement for access to public education.
Families who recently arrived in the United States and do not yet have all prior school records should contact the district directly. Many schools have procedures for assisting students during the enrollment process while records are being obtained.
The U.S. school supply list: what to expect and how to optimize spending
School supply requirements in the United States are often determined by individual schools or teachers rather than a national standard. In addition to notebooks and pencils, families may be asked to provide classroom supplies such as tissues, disinfecting wipes, folders, headphones, calculators, or art materials depending on the grade level. Unlike some countries like Mexico's Becas Benito Juárez, children in the U.S. do not receive cash stipends for school supplies.
Teachers often publish detailed lists before the school year begins. Depending on the grade level, families may be asked to purchase:
- Notebooks
- Folders
- Pencils and pens
- Colored pencils
- Markers
- Glue sticks
- Scissors
- Tissues
- Hand sanitizer
- Backpacks
- Calculators
- Headphones or earbuds
Some classrooms also request community supplies that are shared among students.
When it comes to school supplies, the costs can add up quickly. However there are some strategies that may help reduce expenses:
- Compare prices across multiple retailers
- Purchase supplies gradually during summer sales
- Reuse items that remain in good condition from the previous year
- Check whether local organizations distribute supplies at no cost
- Review teacher lists carefully before making purchases
Some teachers provide additional guidance during the first weeks of school.
How to budget for back to school as an immigrant family
The total cost of a school year is often easier to manage when families plan for it as an ongoing expense rather than isolated expenses. A budget that covers the entire academic year can help reduce unexpected financial pressure.
When preparing a back to school budget, families may also need to consider:
- Transportation
- School meals
- Uniforms when required
- Sports participation fees
- Extracurricular activities
- Technology expenses
- Field trips
- Childcare before or after school
Creating a seasonal budget can make these expenses easier to manage. A useful approach can be to divide costs into three main categories:
Enrollment expenses
These may include uniforms, school supplies, and transportation arrangements before classes begin.
Monthly school expenses
Lunch money, transportation, activity fees, and classroom contributions that continue throughout the year.
Unexpected expenses
Field trips, special projects, replacement supplies, and school events can appear with limited notice.
Considering those three categories can help families avoid relying on emergency funds during the school year. However, it is always important to consider your context and plan according to your own needs.
School support programs for immigrant families
Accessing available school support programs can help reduce some of the challenges families face during the academic year. School districts frequently partner with local organizations to provide services that support student success both inside and outside the classroom. These resources can help families navigate academic, language, and financial barriers that may arise during the school year.
Available resources vary by location but may include:
School meal programs
Eligible students may qualify for breakfast and lunch programs offered through their school district.
English learning services
Students developing English skills may receive language instruction and academic support.
After-school programs
Schools, community centers, and nonprofit organizations often provide academic enrichment and recreational activities.
School supply assistance
Some districts, churches, and community organizations distribute backpacks and school supplies before the academic year begins.
Family resource centers
Certain districts maintain offices that help families access educational resources, translation services, and community support programs.
These programs are designed to help students participate fully in school regardless of their family's circumstances. Checking what is available locally can help families take advantage of resources that support learning, nutrition, and school involvement.
How Común helps you manage school year expenses
Back-to-school season can involve a wide range of financial responsibilities. School supplies, transportation costs, lunch expenses, extracurricular activities, and classroom contributions can create recurring expenses throughout the year.
For families who also support relatives abroad, the back-to-school season may extend beyond the United States. Some immigrants may contribute to support the educational expenses for children back home.
Común offers remittance services that allow eligible customers to send money to Latin America directly through the app, with fees starting at $2.99.
For everyday financial management, eligible customers can open an account using an ITIN, a passport, or more than 100 accepted Latin American IDs. Común also offers features that can help families manage school-year spending, including direct deposit, debit card access, and customer support in Spanish through the app with no mínimum balance requirements or monthly maintenance fees.
For group expenses such as field trips, classroom activities, sports teams, or shared school purchases, ComunPay can help parents collect and send payments directly from the app.
This school year, organizing expenses in one place can make it easier to track spending, support family members, and prepare for school-related costs throughout the year.
FAQ
Do I need immigration documents to enroll my children in school?
Public schools cannot deny enrollment solely because of a child's or parent's immigration status. School districts commonly request proof of age, residency, and immunization records, but immigration documentation is generally not required for enrollment.
When does the school year start in the U.S.?
Most schools begin classes between early August and early September. Exact dates vary by state, district, and school system.
Are school supply lists longer in the U.S. than in Latin America?
It depends. Teachers often provide detailed lists that may include classroom supplies, technology accessories, and shared materials used throughout the school year.
What vaccinations do my children need to enter school in the U.S.?
Vaccination requirements vary by state and school district. Schools typically provide a list of required immunizations during enrollment, and additional guidance may be available through local health departments.
How can I help my children with the language if they don't speak English when they arrive?
Many public schools offer English learning programs that provide language support while students continue learning grade-level subjects. Additional tutoring and community programs may also be available locally.
Are there financial aid programs for school supplies for low-income families?
Some school districts, nonprofit organizations, religious institutions, and community groups distribute school supplies or provide financial assistance before the academic year begins. Availability depends on the location and program requirements.
Financial Education
How to Invest Money in the United States: A Beginner’s Guide
8 min de lectura
Ways to Invest Money and Secure Your Future in the United States
One of the constant concerns for people who leave their home country in search of better opportunities in the United States is financial uncertainty, often caused by poor management and a lack of knowledge about effective strategies to grow their money.
Saving products are an alternative that allows you to save money in the long term while earning interest—returns that depend on the term and the rate offered by the financial institution.
Knowing the different ways to save money is a way to ensure financial stability for you and your family. Below, we explain the types of investments and the safest ways to get started. Please note that investment products are NOT FDIC INSURED, NOT BANK GUARANTEED, and MAY LOSE VALUE.
What Does It Mean to Invest Money and Why Is It Important?
Investing means allocating money toward a goal with the aim of obtaining higher returns in the future. You can do it on your own, through a business, or with formal financial instruments that put the contributed money to work to pay interest over defined time frames.
Here are some benefits of using investment strategies:
- Financial security: gives you the confidence of having a savings fund for the future.
- Financial growth: puts your money to work to generate passive income and avoid losing value due to inflation.
- Family support: helps you plan long-term family projects, such as buying a home or paying for children’s higher education.
How to Define Your Goals and Risk Profile Before Investing
Before you begin, keep in mind that all investments involve some level of risk. If you’re a beginner, it’s essential to start at a level that matches your situation.
You should also be clear about your financial goals—the targets you want to reach in the short, medium, and long term.
Risk Profile
A risk profile is an investor’s ability to handle potential losses caused by market fluctuations.
These are the three main types.
Conservative
This profile is ideal for people not familiar with investing, as it involves low risk. Although returns are steady, they tend to be lower than other investment alternatives. Preferred options include savings accounts and short-term investment funds.
Moderate
This profile suits somewhat more experienced investors who are willing to take moderate risk by combining safer investments with slightly riskier ones to obtain better returns.
Aggressive
This profile is for those who have a strong command of investing. They have a high tolerance for losses and aim for high income through significant long-term investments, typically in the stock market, high-yield funds, and real estate.
Determine Your Risk Profile
Next, define the risk profile that aligns with your personal finances and your experience with these instruments.
Follow these tips to help you make a smart investment.
Step 1. Assess Your Current Financial Situation
Take stock of your finances—consider your income, monthly expenses, debts, and existing savings.
Step 2. Determine Your Investment Goals.
Set exactly what you want to achieve and in what timeframe—for example, buying a home, traveling abroad, paying for medical treatment, or simply building an emergency fund. Remember that long-term investments involve higher risk but can also offer higher returns.
Step 3. Decide How Much You Can Invest Initially.
Based on your budget, determine how much you can allocate to your initial investment and whether you can increase it later.
Step 4. Evaluate Your Risk Tolerance.
Analyze your willingness to accept potential losses and their impact on your personal finances.
Here is a comparative table for clarity.
Investment Profile
Risk Level
Time Horizon
Potential Return
Characteristics
Conservative
Low
Long – Medium
Low
Prioritizes safety over return.
Moderate
Medium
Medium – Long
Low – Medium
Balances safety and returns.
Aggressive
High
Long
High
Seeks to maximize long-term gains, with higher risk.
4 Accessible Investment Options for Beginners
A common misconception is that you need a significant amount of money to become an investor. In reality, there are accessible alternatives that let you start with small amounts, easily.
Here are four ideal options to start investing.
Index Funds
Index funds pool money from multiple investors to buy stocks or bonds.
Main Benefits:
- Automated operation.
- Easy diversification.
- Potential for good long-term returns with little effort.
Certificates of Deposit (CDs)
A certificate of deposit is an investment made directly with a financial institution for a fixed term, meaning you cannot withdraw the money during that period.
Main Benefits:
- A relatively secure way to start investing, as it’s offered by financial institutions.
- Generates steady, predictable returns.
Bonds
Bonds are loans to companies or governments that pay interest periodically and generally carry lower risk.
Main Benefits:
- Income is more predictable.
- A good option to diversify alongside slightly riskier investments.
Digital Investment Accounts
An accessible option that allows you to invest from a mobile application.
Main Benefits:
- Let you start with very small amounts of money.
- Very beginner-friendly for entering the world of investing.
Before choosing an investment vehicle, consider your risk profile. If you prefer stability over returns, CDs or bonds may be ideal.
Avoid “putting all your eggs in one basket.” The key to smart investing is diversifying across several instruments, even with small amounts.
Simple Habits to Invest and Review Your Strategy
When you start investing, it’s important to be realistic, stay patient, and remain consistent with your financial goals.
Here are some simple practices to keep your investments on track.
- Review your investments at least every 3 to 6 months.
- Adjust your strategy as your goals or financial situation change.
- Use digital tools to monitor your progress.
Use Común to Manage Your Money Easily as an Immigrant in the U.S.
Financial management is a responsibility you should entrust to an accessible platform.
Meet Común! The financial service that lets you send, receive, and withdraw money within and outside the United States, quickly, simply, and securely.
Común is a mobile app that allows you to open an account easily with a qualifying official identification from your home country, so it’s a great option for the immigrant community.
Open your account with Común and start sending, receiving, and withdrawing money. Enjoy Spanish and English language support, clear fees, and a digital platform ideal for the immigrant community in the United States.
Frequently Asked Questions (FAQ)
If you still have questions, see the section below. Please note that investment products are NOT FDIC INSURED, NOT BANK GUARANTEED, and MAY LOSE VALUE.
How much money do I need to start investing in the U.S.?
There are quite accessible investment options today, especially digital platforms. Some let you start with amounts as low as $1 or $5, which is ideal for learning to invest.
Is it safe to invest as an immigrant?
Yes—even if you are not a legal resident, you can invest money in the United States. Just make sure to use regulated institutions and platforms.
What if I want to change my investment strategy in the future?
It’s common to change your investment strategy to match your financial goals. Review your investments periodically and make the necessary adjustments according to the applicable timelines.

Immigration
ITIN vs. SSN: What's the Difference and Why Does It Matter?
8 min de lectura
What Is an SSN?
A Social Security Number (SSN) is a unique nine-digit code assigned by the U.S. Social Security Administration (SSA) to citizens, permanent residents, and certain eligible temporary residents. Originally designed to manage Social Security benefits, the SSN is now widely used for tax filing, credit history, and access to government services.
People must submit their SSN application to the address provided by the Social Security Administration.
Key facts about SSNs:
- Eligibility: U.S. citizens, permanent residents, and certain non-citizens authorized to work are eligible for an SSN.
- Uses: SSNs are used for employment, tax filing, Social Security benefits, and access to government services.
- Financial access: SSNs are often required to open bank accounts, apply for credit, and get loans.
An Individual Taxpayer Identification Number (ITIN) is also a nine-digit number, but it's issued by the IRS (Internal Revenue Service) rather than the SSA. People must file Form W-7 to apply for an ITIN. The ITIN is specifically for people who are required to file U.S. tax returns but aren't eligible for an SSN. This includes non-citizens without legal work authorization in the U.S., foreign investors, and dependents of U.S. citizens or residents.
An ITIN is required to file a U.S. tax return and is also used to submit a federal tax return.
Key facts about ITINs:
- Eligibility: ITINs are available to non-citizens who are required to file U.S. taxes but don't qualify for an SSN.
- Uses: ITINs are used solely for tax filing purposes and don't authorize work or provide eligibility for Social Security benefits.
- Financial access: While ITINs can be used to open bank accounts and apply for credit at some institutions, they don't grant the same level of access as an SSN.
Differences Between ITIN and SSN
The main difference between an ITIN and an SSN comes down to who can get them and what they're used for:
- Eligibility:
- SSN: Issued to U.S. citizens, permanent residents, and certain temporary residents authorized to work.
- ITIN: Issued to non-citizens who are required to file taxes but aren't eligible for an SSN. The number of days present in the U.S. affects residency status for tax purposes.
- Purpose:
- SSN: Used for a wide range of activities, including employment, tax filing, and access to Social Security benefits.
- ITIN: Used exclusively for tax filing and reporting by non-citizens without SSNs. An Employer Identification Number (EIN) is used for business entities, estates, and trusts.
- Legal status:
- SSN: Grants work eligibility and access to certain government benefits.
- ITIN: Does not grant work authorization or eligibility for Social Security benefits.
- Access to financial services:
- SSN: Provides broader access to financial services, including easier access to credit, loans, and government benefits.
- ITIN: While it can be used to open bank accounts and access some financial services, options are more limited compared to what's available with an SSN.
ITIN vs. SSN: Why Does the Difference Matter?
Understanding the difference between an ITIN and an SSN matters for several reasons:
- Tax compliance: Knowing which number to use is crucial for filing taxes correctly. Using the wrong identifier can result in errors, penalties, or delays in processing refunds. For U.S. citizens or residents, it's essential to use the correct identifier, such as an SSN or an Adoption Taxpayer Identification Number (ATIN), when an SSN can't be obtained in time for tax filing.
- Access to financial services: The type of tax ID you have can affect your access to banking, credit, and other financial services. For example, some banks and credit unions accept ITINs, while others may require an SSN.
- Employment eligibility: An SSN is required to work legally in the U.S. If you're a non-citizen without work authorization, applying for an SSN can lead to legal complications. In those cases, an ITIN is the appropriate identifier for tax purposes.
- Government benefits: An SSN is required to receive Social Security benefits and other government services, which aren't accessible with an ITIN.
Conclusion
Both the ITIN and the SSN play critical roles in the U.S. financial and tax systems, but they serve different populations and purposes. Understanding the differences between these identifiers is essential for anyone navigating tax filing, financial access, and legal employment in the U.S. Whether you're a U.S. citizen, a non-citizen authorized to work, or a foreign investor, knowing which number you need — and why — can help you avoid potential legal issues and ensure you have the financial access your circumstances require.
International Money Transfers
Alternatives to Western Union: Explore Reliable Options for Your Remittances
8 min de lectura
There is no doubt that Western Union has established itself as a leading company in the remittance industry, with over 145 years in the market.
Since its inception, Western Union has enabled people without access to a banking account to make quick money transfers, which has been particularly significant for rural and immigrant communities in the United States.
According to recent data, in 2023, 12% of remittances sent from the United States to Latin America and the Caribbean were carried out through Western Union, making it one of the leading money transfer services worldwide.
Today, remittances are essential to the lives of millions of Latin American migrants in the United States. In this article, we address alternatives to Western Union that solve problems such as high fees, unfavorable exchange rates, and complicated processes by offering more modern, accessible, and fair financial services.
Why Look for Alternatives to Western Union?
For over a century, Western Union has worked to bring families together through international money transfer services, offering multiple delivery options and broad coverage.
However, over the years, new services have emerged that address areas where Western Union can improve, such as:
High and Variable Fees
One of the main challenges faced by the immigrant community in the United States when sending money is the high money transfer fees, which significantly affect the final amount received.
For example, according to Western Union’s price calculator, the cost to send $500 USD to Mexico via an agency with cash pickup is $15 USD.
Uncompetitive Exchange Rates
In addition to fees, international transactions involve currency exchange, which can be detrimental to the recipient depending on the exchange margin used.
In the previous example of using the Western Union price calculator, the dollar exchange rate is 18.17 MXN, compared to the official rate of 18.64 MXN, meaning the recipient receives 9,081 MXN instead of 9,320 MXN.
Limits and Restrictions
Another factor that may negatively impact migrants sending remittances to Mexico is the limits and restrictions imposed, depending on factors such as payment method, receiving country, and identity verification.
Generally, for unverified users, the limit to send cash through Western Union is $3,000 USD per transaction. Upon verifying identity, that amount may increase.
Transaction Speed
The speed of money transfers through Western Union depends on the payment and delivery method, as detailed below:
- Debit/credit card to cash: minutes
- Debit/credit card to bank deposit: 1–2 business days
- Banking account to cash: 3–5 business days
- Banking account to banking account: up to 5 business days
- In-person cash to in-person cash: minutes
- Wire transfer to mobile wallet: up to 24 hours
Accessibility and Convenience
Western Union is known for its global reach and the accessibility of its international money transfer services.
However, for these same reasons, long lines and wait times may occur. If you need to speed up your transactions, this large-scale service might not be your most favorable option.
9 Alternatives to Western Union for Sending Money Home
If Western Union doesn't suit your needs, here are the best money transfer apps.
Comun
Comun is a comprehensive platform that not only allows money transfers within and outside the U.S., but also gives you access to a complete and efficient financial experience, including easy access to cash.
Enjoy 24/7 support also available in Spanish, and pay transparent fees starting at $2.99 USD for international money transfers, with no hidden fees.
Ria Money Transfer
Ria Money Transfer is a service similar to Western Union. It has coverage in a large number of countries worldwide and offers different payment and delivery methods, as well as partnerships with retailers like Walmart.
Wise (previously TransferWise)
Wise is a U.K.-based financial technology company that facilitates international money transfers and offers benefits such as a multi-currency account and real exchange rates.
Remitly
Remitly is a fintech that operates primarily in the United States, Canada, and Australia. It allows money transfers with options for cash pickup, bank deposit, or mobile wallet. While it is a good option for sending remittances to Latin America, it has fees and exchange rates that are not very competitive.
WorldRemit
WorldRemit is a global money transfer service with a presence in over 130 recipient countries. In addition to offering cash pickup and bank deposit options, it also allows transfers through mobile phone top-ups.
PayPal/Xoom
Xoom is a remittance company acquired by PayPal. It offers money transfers with multiple delivery methods, such as bank deposit, cash pickup, mobile wallet, or direct delivery.
MoneyGram
MoneyGram is a U.S.-based company specializing in international money transfers and person-to-person (P2P) payments. It operates in over 200 countries with various payment options.
OFX
OFX is a company specializing in international money transfers and currency exchange, with a presence in over 190 recipient countries.
Revolut
Revolut is a U.K.-based fintech offering multi-currency digital accounts, international money transfers, and investment services.
How to Choose the Most Suitable Alternative for Your Remittances
If you are still wondering which money transfer app is right for you, remember to consider the following factors before selecting an alternative to Western Union:
Fees and Real Exchange Rate
It is advisable to look for a payment service provider with clear, flat fees to ensure your family receives the maximum possible amount.
Transfer Speed
While in many cases, most apps offer quick money transfers, in others, the waiting time could be problematic for the recipient.
Sending and Withdrawal Methods
Make sure the sending methods suit your needs, whether via banking account, credit or debit card, or cash delivery.
Coverage in Your Country
Verify that the money transfer service has coverage in Latin America, and that this does not involve additional shipping fees.
Ease of Use and Customer Support
It is important to communicate easily in case of any issues. Choose an option with 24/7 Spanish-language support.
Security and Trustworthiness
Ensure the service has the necessary licenses and regulations for the places where it operates, as well as the appropriate security measures to protect your data.
Comun: A Great Financial and Remittance Alternative Designed for the Immigrant Community in the U.S.
Although Western Union is an excellent option for sending money abroad, there are better alternatives with more competitive and fair conditions that can make your money, and your family’s, go further.
It is essential to research and compare each international payment service in order to choose the option with the most suitable benefits for you.
Comun offers you an all-in-one service that allows low-cost international money transfers, along with a complete financial experience in your language.
- Open your account easily using official documentation from your country
- Make your first international money transfer free, and afterward pay a fee starting at $2.99 USD per transfer, up to the applicable limits
- Deposit cash at over 88,000 retail locations in the U.S.
- Manage your finances through a mobile app
- Access to Spanish-language support 24/7
Open your account today and discover an alternative to Western Union.
Frequently Asked Questions
Is it safe to use digital alternatives to Western Union?
Comun uses secure technology and follows U.S. financial regulations to help protect your money transfers. You can also choose from multiple payment and delivery options.
What are the hidden costs when sending money internationally?
International money transfers generate fees, in addition to the currency conversion rate.
Can I send money to a country if I don’t have a banking account?
With Comun, you can send cash even if you don’t have a traditional U.S. banking account.
What do I need to open an account with services like Comun?
A compatible Android or iOS phone and an official ID from your country.
How long does a money transfer take with these alternatives?
Money transfers with Comun are reflected within minutes or hours.
Disclosures (in footer):
“Comun is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank; Member FDIC. The Comun Visa® Debit Card is issued by Community Federal Savings Bank, pursuant to a license from Visa U.S.A Inc. and may be used everywhere Visa Cards are accepted.”
“Funds in your account are FDIC insured up to $250,000 by ownership category through Community Federal Savings Bank (CFSB), Member FDIC, in the event CFSB fails.”
“A service provided by Service UniTeller, Inc. Service UniTeller, Inc. is licensed in all states that require a license.”
“Remittance fees start at $2.99 but may vary. Please check the app for more details.”
“Comun Inc. may earn revenue from the conversion of foreign currencies.”

Checking account
How to Identify Where to Deposit Cash
8 min de lectura
Depositing cash into your Común account is simple and convenient. Whether you prefer using your physical card at an AllPoint+ ATM or generating a barcode in the app, here is a step-by-step guide to help you understand both methods.
Using a Physical Card
Step 1: Wait for Your Physical Card
After opening your online bank account, your physical debit card will be mailed to your home. This usually takes 7 to 10 business days.
Step 2: Activate Your Card
Before you can use your card, make sure to activate it through the Común app. Your card must be active for any transaction.
Step 3: Locate an AllPoint+ ATM
AllPoint+ ATMs are part of a broad network of ATMs, perfect for cash deposits. Here is how to find one:
- Open the Común app.
- Go to the "Move Money" section.
- Use the map to locate the nearest AllPoint+ ATM. These machines are usually found at popular retail locations.
Step 4: Deposit Cash at an AllPoint+ ATM
Once you are at the ATM:
- Insert your activated card.
- Follow the on-screen instructions to deposit cash into your checking account. Please note that deposits can only be made into checking accounts, not savings accounts.
- Make sure your deposit is within the limits: up to $250 per deposit and up to $1,000 per day, including deposits and withdrawals.
Tip: If there are no AllPoint+ ATMs near you, do not worry. You can also deposit cash using a barcode at many other locations!
Using the Barcode in the App
Step 1: Generate a Barcode
Here is how to generate a barcode in the Común app:
- Open the app and go to the "Cash" section.
- Select the option to generate a barcode for deposit.
- The barcode will appear on your screen, ready to use.
Step 2: Find Locations That Accept the Barcode
To find a nearby location that accepts the barcode:
- In the "Cash" section, look for the list of participating locations.
- You can also use the map feature to find the nearest store.
Step 3: Using the Barcode
Take your barcode to a participating location and show it to the cashier. They will scan the barcode, allowing you to deposit your cash.
Important Details:
- Expiration: The barcode expires after 15 minutes, but you can generate as many as you need.
- Limits: Keep in mind the deposit limits that may apply when using the barcode method.
Troubleshooting ATM Transactions
Problems Depositing Money
When troubleshooting ATM transactions, especially problems depositing money, it is important to make sure you are using an AllPoint+ ATM, since these machines do not charge fees for deposits. Your physical card must be activated; if it is not, you can easily activate it from the app. Also, make sure you enter the correct PIN. If you do not remember your PIN, you can view it or change it in the app settings section. Verify that your deposit is within the limits, which are up to $250 per deposit and up to $1,000 per day. Finally, always select "checking account," since Común accounts are checking accounts, not savings accounts.
Problems Withdrawing Money
If you run into problems withdrawing money, first make sure you have enough balance by checking your balance in the app before making a withdrawal. Use an AllPoint+ ATM to avoid withdrawal fees, since other ATMs may charge a fee. Enter the correct PIN; if you do not remember your PIN, you can view it or change it in the app settings section. Verify that your withdrawal is within the limits, which are up to $250 per withdrawal and up to $1,000 per day, including deposits and withdrawals. If you continue having problems, contact us through the chat in your app for more help.
Alternative Deposit Methods
If you cannot find a nearby store to deposit cash, Común offers other options:
- Receive Money: Use apps like Zelle, CashApp, Venmo, or PayPal.
- Direct Deposit: Set up direct deposit with your employer.
- External Transfers: Send money to your Común account from an external bank or other financial institutions.
Additional Tips and Information
Fraud Prevention
Always keep your account number and PIN secure. Do not share this information with anyone to avoid unauthorized transactions.
Know Your Limits
Be aware of the deposit amount limits. For example, you can only deposit up to $250 per deposit and up to $1,000 per day. This helps you manage your funds and avoid any unexpected issues.
Use Común Features
The Común app provides a map to find the nearest ATMs and stores that accept barcodes for deposits. This feature helps you quickly locate convenient deposit points.
Stay up to date with the latest features and benefits offered by Común through the app, ensuring you get the most out of your online banking experience.
Cash Deposit Fees
Depositing cash at an AllPoint+ ATM has no fees, while other ATMs may charge a fee. Always check for possible fees before making a deposit.
Mobile Check Deposits
In addition to cash deposits, Común also supports mobile check deposits, adding more flexibility to the way you manage your money..
Conclusion
In short, depositing cash into a bank account is a practical decision driven by safety, convenience, possible earnings, financial management, and legal compliance. By understanding these reasons, people can make informed decisions about how to handle and manage their cash effectively, ensuring financial stability and growth.
Whether you use your physical card at an AllPoint+ ATM or a barcode in the app, depositing cash into your Común account is simple and convenient. Always make sure your card is activated, check nearby locations, and keep deposit limits in mind. With these steps, you will be able to manage your cash deposits effortlessly.
Do not worry, if there are no locations near you, you can also deposit with a barcode at many more locations! Visit Común for more details and get started with your deposits today.
By understanding the process and using the tools provided by Común, you will be able to handle your cash deposits effectively and ensure your funds are always accessible.
Community
Común: Digital Banking for Immigrants in the U.S.
8 min de lectura
Común does not have branches, but it has a team that supports its customers 24 hours a day, 7 days a week, from the comfort of their homes, in three different languages.
Building a better future for immigrants in the U.S. is a core principle of Común’s mission. Accessible and easy-to-understand banking options are a key part of the immigrant journey. However, the options are scarce.
Complex, cumbersome, and expensive options are the norm. Activities that may seem trivial and intuitive to those born in the U.S. are overwhelming and confusing for a newly arrived immigrant. Everything from setting up direct deposit with an employer to sending money home, making payments for goods and services, or understanding how to build a credit score seems too complex for anyone who has never had to do this in the U.S., let alone at all.
Hidden fees and costly charges add another layer of stress when starting a financial life in the U.S. Between minimum account balances, monthly fees, overdraft charges, large check deposit fees, extortionate international transfer fees, and everything else, maintaining and using a bank account in the U.S. can be expensive. For manual laborers, this can represent a significant percentage of their wages.
The physical locations of traditional banks can also be scarce in some areas. Since opening a bank account or depositing a check or cash into the account must be done at a branch, this is a significant burden for someone living in a remote area. Many immigrants, sometimes working on remote farms or factories, live miles away from the nearest bank branch. Transportation costs to those branches add to the already high fees of using and maintaining an account.
Even if the banking services provided were more intuitive, digital, and lower cost, another major barrier remains. Obtaining the necessary documentation to open a bank account can also make access to fair and simple financial services difficult. Immigrants fortunate enough to have work authorization still need to gather important documentation that is not always available to them. For those who have come to the U.S. seeking asylum or better work opportunities through a more unconventional path, the documents required to open an account are often prohibitive.
Building a 100% digital banking platform to solve the issues mentioned above is part of what Común seeks to achieve because we believe in helping unlock social mobility. But a digital, low-cost, and intuitive platform is not enough. To navigate this process, immigrants need help, and help is best found in a Community that understands them when they need it most.
That is why not only our customers are part of our Community, but also the people who help them 24 hours a day, 7 days a week through our app, social media, WhatsApp, or by phone. Beyond solving an immediate problem, the support provided goes further. It teaches and educates, empathizes, and strives to foster a sense of Community among people who understand them, in terms they comprehend and in the language they speak. This is the core of true digital community banking. Our team helps them set up direct deposit, get refunds for charges they disagree with, and everything else.
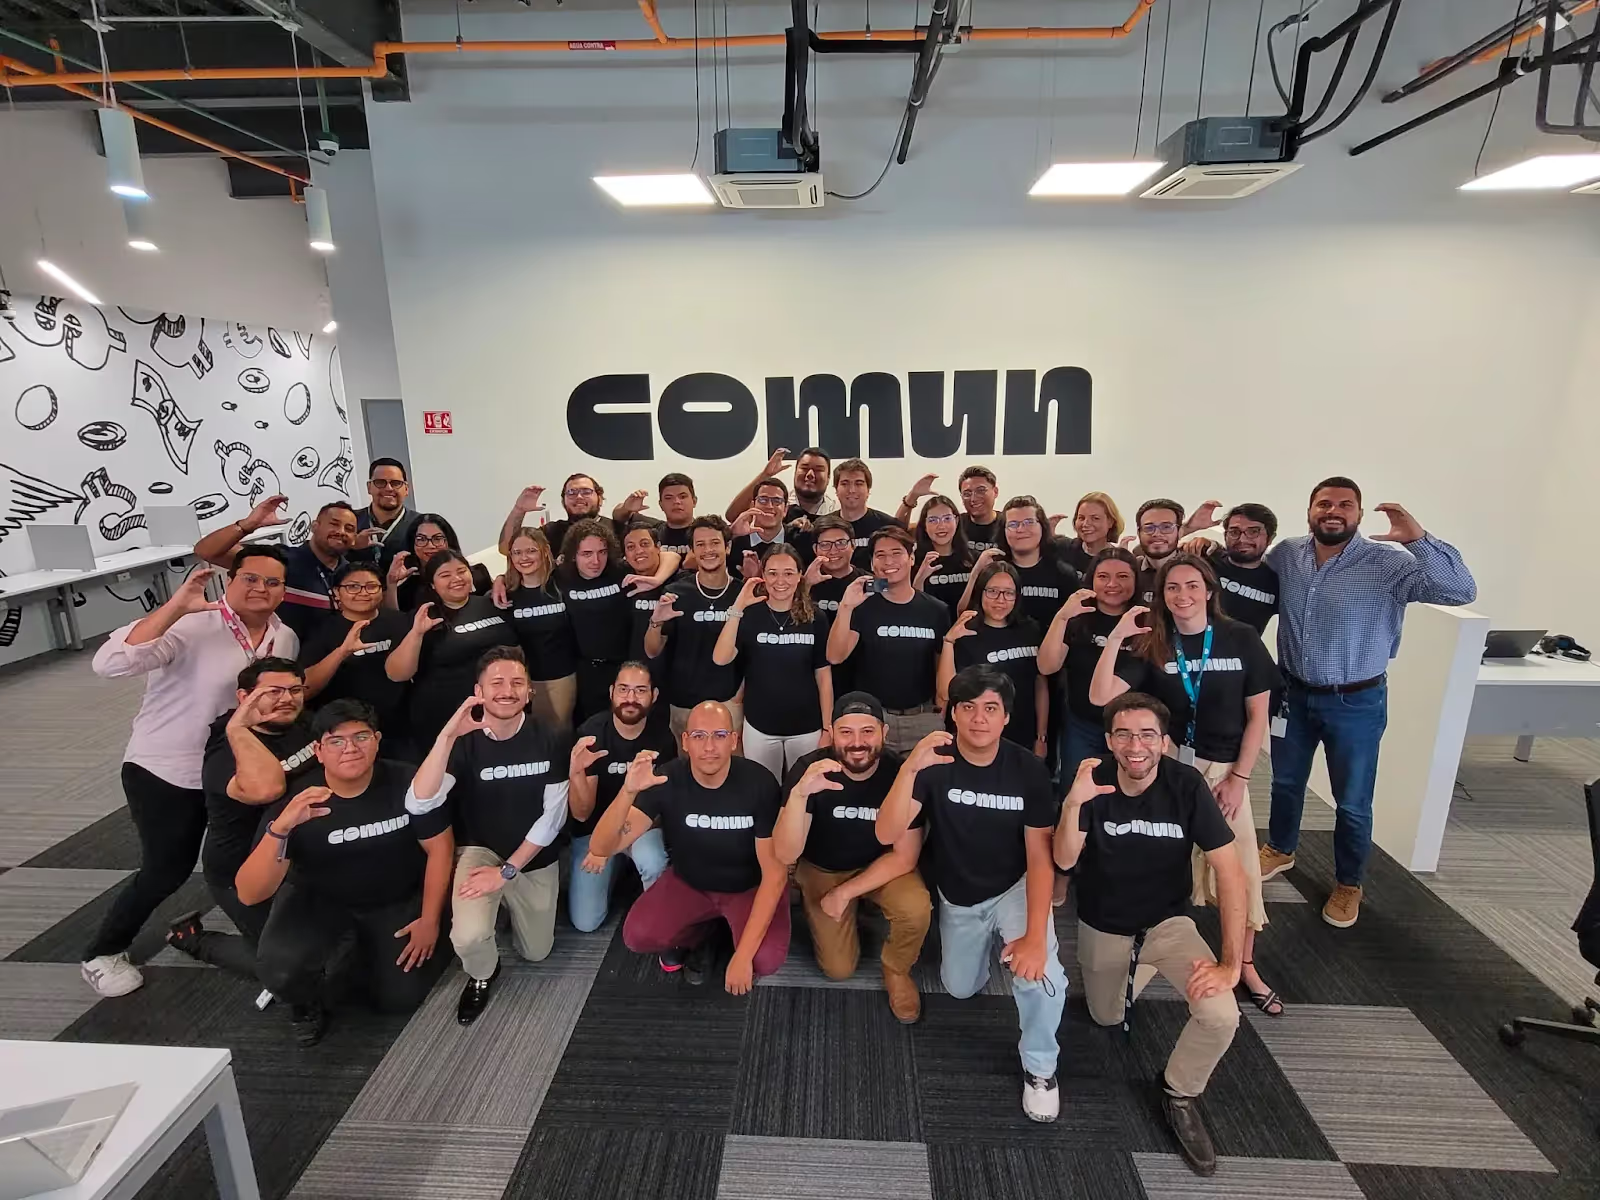
At Común, the first step in this journey has already begun. Our team in Mérida, Mexico, is part of our Community and the one we seek to serve. They are an extension of our mission and our digital platform, and a necessary ingredient in unlocking social mobility for millions of immigrants in the U.S.
Living in the United States
Requirements to rent a house in the United States if you are an immigrant
8 min de lectura
One of the main challenges immigrants face in the U.S. is formalizing a lease, since property owners often require a series of documents that can turn the search process into a maze.
Examples might include credit scores, proof of income, background checks, and references that many immigrants do not yet have. However, there are proven strategies that make it easier for newcomers to obtain a lease in the United States.
If this sounds familiar, keep reading—we’ll explain in detail how to prepare to rent safely and avoid the typical obstacles immigrants encounter when establishing themselves in the U.S.
What do you need to rent in the United States?
Before you start searching for your next home, you should keep in mind the key requirements for renting an apartment in the U.S. These help the landlord confirm that the tenant is reliable and has sufficient financial solvency to pay rent on time and in full.
Below are the most requested items to sign a lease:
Personal identification
It’s very important to verify your legal identity. Landlords or real estate agents may ask for one or more of the following documents:
- Valid passport.
- Visa or resident card.
- Driver’s license.
- Social Security Number (SSN) or ITIN.
Financial solvency
To demonstrate you have sufficient solvency to cover the monthly rent, you can provide several documents, such as:
- Proof of income, such as pay stubs, tax returns, or bank statements.
- Employer letter or employment contract.
- It is also common to be asked for a security deposit equal to one month’s rent, which serves as a guarantee in case of damage to the property.
Credit history
Reviewing credit history is a crucial step for landlords and agents because it provides reliable evidence of the applicant’s financial behavior.
If you’ve been in the United States for a short time, you may not have a credit history. This article explains simple ways to start building one.
In that case, you may be asked for a credit report from an official agency or a signed authorization to check your credit score.
Local guarantors
If you lack sufficient evidence of solvency, you may be asked for a guarantor, who serves as a backstop if you cannot meet the lease terms.
Such a guarantor must reside in the United States and provide the following documents:
- Government-issued ID.
- Proof of income.
- Good credit history.
Renting in the United States: Process and leasing options for immigrants
Housing options in the U.S. are broad and adapt to all lifestyles, budgets, and immigration statuses.
Rental options you can find in the United States include:
- Furnished houses or apartments.
- Unfurnished houses or apartments.
- Individual rental.
- Shared rental.
Regardless of the type of property you’re looking for, we recommend following these steps to rent a house or apartment.
1. Explore and select the property
Take the time to review all property details and alternatives in different neighborhoods and cities. We recommend searching trusted sites such as Zillow, Realtor, or Apartments.com. Also ask friends or acquaintances who have gone through the process for referrals.
2. Evaluate the offer conditions
Carefully analyze the lease terms, such as price, property description, requirements, and restrictions.
3. Submit your rental application
When you find a home that meets your expectations, submit a rental application with your personal information, references, and authorization to check your credit history.
4. Visit the property
Before signing any contract or paying a deposit, it is essential to visit the property to ensure it matches the listing and is free from maintenance-related deterioration.
5. Submit the required documentation
If after the visit you are still interested in renting the property, the next step is to provide the previously mentioned documents, such as proof of income and government ID.
6. Review and sign the lease
The landlord will review your application and verify your documents. If approved, the final step is agreeing to and signing the lease terms, which set the rental conditions such as duration, cost, rules, and conditions for refunding the security deposit, among others.
Three key tips for a safe, hassle-free first rental
Finding your first rental in the U.S. can be a major challenge due to the number of requirements involved.
Below are some useful tips to help your search pay off as soon as possible.
Research the housing market
Use rental websites to research which areas are more affordable or best fit your lifestyle, ensuring you can cover not only rent but also day-to-day expenses.
Use multiple search methods
Don’t limit yourself to a single method. Alternate among websites, mobile applications, classifieds, and even the help of a real estate agent.
Avoid scams
It’s essential to stay alert to potential scams. Apply these tips and stay safe:
- Make sure the agent or brokerage is registered and has reliable references.
- Do not make any payment before personally visiting the property and having a contract formalized before a notary.
- Use only recognized platforms and portals.
- Be wary of last-minute offers or listings that seem “too good to be true.”
- Avoid using cash when finalizing the rental.
- Review each clause of the contract in detail before signing.
Considerations before choosing a home
Before choosing a house or apartment to rent, it’s important to consider several factors, for example:
- Location:
Location is one of the most relevant aspects when choosing a home. Beyond the city, consider the distance to your workplace and other frequent destinations.
- Neighborhood:
Research the type of neighborhood, safety, infrastructure, recreational areas, community profile, and any other information you consider significant for making a decision.
- Rental cost:
Make sure the rent fits within your means. Create a budget that includes your monthly income and expenses.
Below are tenants’ rights and obligations in the United States.
Payments and deposits
The tenant must pay the monthly rent and the agreed deposit on time. Both payments can be made by bank transfer, bank deposit, or check.
Maintenance and repairs
The landlord must ensure the property is in optimal condition and has all utilities. In turn, the tenant agrees to take care of the premises, keep them clean, and report any defects requiring maintenance.
Tenant legal protections
Tenants are protected by U.S. law against unfair practices, such as:
Refund of the security deposit if conditions are met.
Protection against unjustified or no-notice eviction.
Make your rent payments online safely and conveniently with Común
Renting your first home in the United States doesn’t have to be overwhelming. Take time to learn the most common requirements and consider alternative solutions like those in this article. This way, you’ll see it is possible to open the door to decent housing.
With the right preparation and tools, the rental process becomes much simpler and more accessible.
Rely on Común, a financial platform that addresses day-to-day needs in the United States, with an intuitive mobile app, so opening an account is quick and easy using qualifying official identification from your country of origin. It also makes it simple to send remittances up to the applicable limits to LATAM countries, so your family receives more, with competitive fees.
Discover Común, an excellent option dedicated to serving immigrant communities in the United States, with support available in Spanish.
Open your checking account today with a partner that understands your needs as an immigrant!
Frequently Asked Questions
If you still have questions, check our FAQs.
How much does rent cost in the United States?
The national average for rental housing is around $2,100 USD.
Where is it cheaper to live in the United States?
Cities such as Laredo, Texas, and Toledo, Ohio report the most affordable living costs.
International Money Transfers
What banks does Zelle have in Mexico? A Complete Guide to Sending and Receiving Money from the U.S.
8 min de lectura
Have you heard of Zelle? It is a highly popular digital payments platform in the United States. It allows users with accounts at affiliated banks—whether traditional banks, digital banks, or credit unions to easily send and receive money.
In 2024 alone, Zelle reported 151 million enrolled accounts, including individuals and small businesses, reflecting its widespread adoption among U.S. users.
If you need to send money outside the United States easily, for example Mexico, you may be wondering which banks in Mexico support Zelle.
However, this platform does not have agreements with any banks in Mexico, and it is mandatory to have a U.S. banking account to access its services.
Nevertheless, there are other options as efficient as Zelle for sending money to Mexico, such as banking accounts with integrated remittance services and international money transfer applications.
Below, we explain how to receive money through Zelle, the benefits it offers for users in the United States, and the alternatives available for sending money to other countries.
What is Zelle and Is It Possible to Use It in Mexico?
Zelle is a digital payments service that facilitates P2P (peer-to-peer) transfers at certain partner banks within the United States.
It is known for being a fast service, with money transfers reflected within minutes, in addition to being free and having broad coverage throughout the U.S.
It operates through the mobile apps of participating banks, as it is directly integrated with them and only allows money transfers to other Zelle users.
But which bank in Mexico is compatible with Zelle? Unfortunately, it is not possible to send or receive money through this platform in Mexico, as it is not designed for international money transfers and only complies with the technological and regulatory standards of the U.S. financial system.
Which Banks in Mexico Use Zelle? Everything You Need to Know
No bank in Mexico is compatible with Zelle services, meaning that international money transfers cannot be made through this platform.
To use Zelle, you must have a U.S. banking account at one of the affiliated banks.
Here is a list of some of the major banks that support Zelle in the United States:
- Ally Bank
- Bank of America
- BMO Harris Bank
- Capital One
- Chase (JPMorgan Chase)
- Citibank
- Citizens Bank
- Discover Bank
- Fifth Third Bank
- FirstBank
- Frost Bank
- Huntington Bank
- PNC Bank
- Regions Bank
- TD Bank
- Truist Bank
- US Bank
- Wells Fargo
Although Comun is not integrated with Zelle, this does not limit its functionality, as it is a comprehensive personal finance solution that goes beyond just money transfers.
How to Send Money to Mexico with Zelle? Answers and Efficient Alternatives
If you need to send money to Mexico quickly, you will have to choose a different service than Zelle, as it only allows bank transfers between U.S. accounts.
The main reasons Zelle is not available in Mexico are:
- To register with Zelle, you must access the online banking platform of one of the affiliated U.S. banks.
- You also need a U.S. phone number or email address.
- Zelle is not a remittance or international payment platform, so it does not have the capacity to convert currencies or deposit funds in international banks.
- Zelle does not comply with the regulations of financial institutions in Mexico, such as Banxico and the CNBV.
If you have used Zelle to send money within the United States, you are likely looking for a similarly reliable system to make international money transfers.
U.S. Banking Accounts with Integrated Remittance Services
In addition to traditional banks, there are alternatives that offer integrated remittance services to facilitate money transfers to Mexico.
Comun is a platform that meets the needs of many people in the United States, especially the immigrant community, by allowing remittances to be sent to loved ones easily, at very low cost, and through a single mobile application.
International Money Transfer Platforms
Another alternative for making international money transfers is to use platforms specialized in this type of transaction.
Examples include:
- Wise: sends money between accounts using the real time exchange rate.
- Remitly: offers international money transfers with standard or instant delivery.
The advantage of these platforms is that a bank account is not required, and their operation is accessible. However, the money transfer fees vary depending on factors such as the amount to be sent and the exchange rate.
Traditional International Bank Transfers to Mexico
You can also opt to make money transfers through traditional banks, for which you will need the SWIFT code of the receiving institution in Mexico and the recipient’s banking details.
Although it is a secure option, it is also one of the most expensive, due to high fees and intermediaries that increase the cost.
For example, a U.S. bank like Bank of America charges a $45 USD fee plus an average of 1% to 3% exchange rate margin. Therefore, in a money transfer of $1000 USD, the recipient receives approximately 900 pesos MXN less than with specialized international money transfer platforms.
Cash Deposit/Withdrawal Services at Retail Networks
If the recipient does not have access to a banking account, you can choose a service for cash deposit and withdrawal at physical locations.
Some examples include:
- Western Union: global network for bank transfers and cash delivery
- MoneyGram: allows money transfers to banking accounts and in cash
- Comun: also allows quick cash transfers
Beyond Zelle: Comun Simplifies Your Financial Life in the U.S. and Your Money Transfers to Mexico
Although Zelle is a very effective service for sending and receiving money within the United States, it has limitations that prevent international money transfers, making it more suitable for citizens who need to make frequent payments within U.S. territory.
For the immigrant community in the United States, it is important to choose a solution that not only facilitates money transfers but also offers a complete, accessible, and easy-to-use finance platform.
Comun is the platform that will simplify your financial life in the United States, offering the following benefits:
- Open an account easily using your official ID from your country.
- Forget about traditional fees: no opening fee, no monthly maintenance fee, and no minimum balance required.
- No hidden charges for remittances: your first international money transfer is free, and afterward you pay a fee starting at $2.99 USD per transfer, up to the applicable limits.
- Customer support also available in Spanish.
- Integrate your finances and remittance service in a single mobile application, making Comun the most suitable option.
- Obtain a Visa debit card to make purchases in physical stores.
- Access an extensive cash management network and make deposits at thousands of locations near you.
Open your Comun account and access a financial service without complications.
Frequently Asked Questions
Do I need a U.S. account to use Zelle?
Yes, Zelle is only available through the online banking platforms of affiliated U.S. banks.
Can I send money to Mexico via Zelle if I have a U.S. account?
No, no bank in Mexico is compatible with Zelle.
What are the best alternatives to Zelle for sending money to Mexico?
Comun: a fintech platform that provides access to an account and remittance capabilities.
Does Comun offer Zelle for sending money to Mexico?
Comun is not connected to Zelle, but you can send money to Mexico for a fee starting at $2.99 USD per transfer up to the applicable limits.
How do I set Zelle to Spanish?
Since it is a service available through the affiliated bank apps, you must access their settings and select Spanish as the preferred language.
How do I download Zelle?
Go to the Play Store or App Store and search for Zelle. Remember, it is only available in the United States.
International Money Transfers
Sending money to Latin America? What you need to know about the new 1% tax
8 min de lectura
Sending Money to Latin America? What You Need to Know About the New 1% Tax
If you send money home to Mexico, Guatemala, Colombia, El Salvador, Honduras, or anywhere else in Latin America, a new federal law may affect the fees you pay per money transfer, depending on how you send it.
On July 4, 2025, the United States enacted the One Big Beautiful Bill Act (OBBBA), Public Law 119-21, which introduced a new federal excise tax on certain international money transfers. The tax, set at 1% of the transfer amount, applies to remittances made on or after January 1, 2026. However, not all transfers are taxable.
If you send money from a US bank account or using a US-issued debit or credit card, your transfer is exempt from the tax by statute. The tax applies only when you pay with cash, a money order, a cashier's check, or a similar physical instrument.
Understanding whether this tax applies to you and how it may affect your transfers can help you send money home with fewer surprises.
What Is the New 1% Remittance Tax?
It imposes a 1% federal excise tax on certain outbound remittance transfers, meaning money sent from a sender in the United States to a recipient in a foreign country, through a remittance service provider.
The tax is codified under IRC Section 4475, added to the Internal Revenue Code by Section 70604 of the OBBBA. It applies to all senders, regardless of citizenship or immigration status.
The tax was effective for transfers made after December 31, 2025, with collection beginning January 1, 2026.
Who Pays the Tax? Who Doesn't?
The key factor is how you fund the transfer, not how much you send, not where it goes, and not your immigration or citizenship status.
| Subject to the 1% Tax | Exempt from the 1% Tax |
|---|---|
| Transfers funded with cash (e.g., paying cash at a remittance service provider) | Transfers funded from a US bank account at a BSA-compliant institution |
| Transfers funded with money orders | Transfers funded with a US-issued debit card |
| Transfers funded with cashier's checks | Transfers funded with a US-issued credit card |
| Transfers funded with similar physical instruments | Transfers of $15 or less (under EFTA threshold) |
Source: IRS.gov, RSM US. This information is for informational purposes only and does not constitute legal or tax advice.
This means that if you often send money back home with a remittance service provider with physical locations (for example Western Union or MoneyGram) and pay with cash, a 1% tax will be added to your total transfer amount.
However, if you send money through a digital app or bank account linked to your US checking or savings account, or pay with a US-issued debit or credit card, the transfer is exempt from the tax under Section 4475.
How Is the Tax Collected?
The tax is collected at the point of transfer. When a taxable transaction occurs, the remittance transfer provider is responsible for collecting the 1% from the sender at the time the transfer is made.
Providers must then deposit the collected taxes with the IRS on a semimonthly schedule and file quarterly returns.
The Remittance Landscape in 2026
For millions of families across Latin America, the money that arrives from a relative in the United States can pay the rent, cover school fees, or put food on the table. In 2024, Latin America and the Caribbean received an estimated $161 billion in remittances, the vast majority sent from the US. Mexico alone received over $63.3 billion. In countries like El Salvador, Guatemala, Nicaragua, and Honduras, remittances represent between 19% and 26% of GDP.
For people already stretching every dollar between their own expenses in the US and the needs of family back home, an additional cost on each transfer can have an impact. How much it affects you depends largely on the tools available to you.
Cash agent networks (Western Union, MoneyGram, Intermex):
These are the traditional in-person options, often used by senders who mostly manage cash. Transfers funded with cash at these locations are subject to the 1% tax.
Digital apps (Remitly, Wise, Xoom, Común, and others):
These platforms typically process transfers from a linked US bank account or US-issued debit or credit card. These payment methods are exempt from the tax under Section 4475. However, fees and exchange rate margins may vary by provider.
Bank wire transfers:
Transfers sent directly from a US bank account at a Bank Secrecy Act–compliant institution are exempt from the tax by statute. Bank wire fees can be higher than digital app fees.
What This Means for You
If you send money home regularly, you already know that there are costs involved: transfer fees, exchange rate margins, sometimes a fee on the receiving end. Now, depending on how you send money, there may also be a new 1% federal tax. That may not sound like much in isolation, but if you're someone already careful about managing what to keep and what to send, it can add up.
There is no single right answer for everyone. Some people that have a US bank account can shift to a digital transfer method. Others who don't have that option yet, or may have reasons for continuing to send through an agent location. Whatever your situation is, a few things may help:
Know what you're being charged:
Before confirming any transfer, you should be able to see the fee, the exchange rate, any applicable taxes, and the exact amount your family will receive. Review everything before you hit send. Some service providers, like Común, offer in-app tools to help you calculate the costs before sending anything.
Compare the total cost:
A provider that charges no transfer fee but offers a weaker exchange rate can potentially cost more than one with a modest flat fee and a fair rate. The number that matters is what arrives on the other end.
If you have a US bank account or debit card, ask your provider about your options:
Transfers funded from a US bank account or US-issued debit or credit card are exempt from the tax under the current statute.
Ask your provider directly how they handle the tax:
Some providers may have updated their apps, websites, or agent instructions. If you're sending via a digital channel linked to your US bank account or debit or credit card, ask whether that payment method qualifies for the statutory exemption.
Manage your remittances confidently with Común
Having an account to receive electronic payments, track your spending, and send money directly may help make managing your financial life in the U.S. more convenient. Común accepts more than 100 valid Latin American IDs to open a debit account. With Común you get:
- A $2.99 flat fee per remittance transfer, with no hidden charges
- A checking account held at Community Federal Savings Bank, Member FDIC. Deposits are FDIC insured up to the applicable limits
- Transparent, in-app pricing where you can see exactly what each transfer will cost, including fees and the exchange rate, before you confirm
- 24/7 customer support in Spanish
- Cash pickup options for your recipient
- The ability to send transfers from the comfort of your phone
To learn more about Común's remittance services, visit comun.app/remittances.
FAQ
What is the new 1% Remittance Tax?
It is a federal excise tax introduced by the One Big Beautiful Bill Act (OBBBA), Public Law 119-21, codified as IRC Section 4475. It imposes a 1% tax on certain outbound money transfers from the United States to recipients in foreign countries. It applies only to transfers funded with cash, money orders, cashier's checks, or similar physical instruments.
When does the new remittance tax take effect?
The tax applies to remittance transfers made on or after January 1, 2026. It was signed into law on July 4, 2025, as part of the OBBBA. The IRS granted penalty relief to providers for the first three quarters of 2026, with full enforcement expected beginning Q4 2026.
Who has to pay the 1% tax?
The tax is owed by the sender, but it is collected and remitted to the IRS by the remittance transfer provider at the time of the transfer. It applies to all senders, regardless of citizenship or immigration status.
Are all money transfers from the US subject to the new tax?
No. The tax applies only to transfers funded with cash or physical instruments. Transfers funded from a US bank account at a Bank Secrecy Act–compliant institution, or paid with a US-issued debit or credit card, are exempt from the tax by statute.
How is the tax collected?
The remittance transfer provider collects the 1% tax from the sender at the time of transfer. Providers must deposit collected taxes with the IRS on a semimonthly schedule and file quarterly returns using Form 720.
How can I tell if my transfer is taxable?
It depends on how you're funding the transfer. If you are paying with cash, a money order, or a cashier's check at a remittance agent, the 1% tax likely applies. If you are sending money through a digital app or bank account using your US checking account or a US-issued debit or credit card, the transfer may be exempt under the current statute. Ask your provider directly to confirm how your specific payment method is classified.







Thousands of immigrants are already achieving more with their money. You can too.
Comun is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank; Member FDIC. The Comun Visa® Debit Card is issued by Community Federal Savings Bank, pursuant to a license from Visa U.S.A Inc. and may be used everywhere Visa Cards are accepted.
Comun is a fintech company and not a bank or licensed money transmitter.
* Results may vary. For a complete list of eligible IDs and application requirements, follow this link.
^ No minimums, no maintenance fees. ATM or transfer fees may apply. See app for fee details.
‡ Direct deposit funds are typically available when we receive the payment file, up to two days before the scheduled payment date. This early availability is not guaranteed.
** A service provided by Service UniTeller, Inc. Service UniTeller, Inc. is licensed in all states that require a license. Remittance fees start at $2.99 but may vary. Please check the app for more details. Comun Inc. may earn revenue from the conversion of foreign currencies.
† Funds in your account are FDIC insured up to $250,000 by ownership category through Community Federal Savings Bank (CFSB), Member FDIC, in the event CFSB fails.


