
Living in the United States
5 Apps to Earn Money Fast in the United States
5 easy apps to earn extra money from your phone in the U.S. — no SSN required with Común.
8 min read

17 Apr 2023
Are you looking for ways to make extra money from the comfort of your home or during your free time? Thanks to technology, it is now possible with just a mobile phone and an internet connection. In this article, we present five apps that will let you earn money quickly and easily.
You can earn money from your phone in the U.S. with paid surveys (Eureka Surveys, Google Opinion Rewards), freelance work (Fiverr), selling used items (Mercari), or driving for Uber or Lyft. With Común, you can receive all of those payments in an account without SSN, without monthly fees, and in Spanish.
Eureka Surveys or Survey Pop:
1. Eureka Surveys is a platform that lets you earn money by answering surveys in minutes on your own schedule. You will accumulate points that you can redeem for gift cards or cash through PayPal.
Google Opinion Rewards:
2. Google Opinion Rewards is an app created by Google that lets you earn money by answering short surveys. For each completed survey, you will receive a reward redeemable in Google Play.
Fiverr:
3. Fiverr is a freelance services platform where you can offer your skills and knowledge in exchange for money. You can find jobs in design, writing, digital marketing, programming, and more. Remember to connect your Común account to Fiverr.
Mercari:
4. Mercari is a buying and selling app where you can sell new or used items. The app keeps a small commission for each sale made.
Uber or Lyft:
5. If you have a car and free time, you can take advantage of transportation apps like Uber or Lyft to earn extra money as a driver.
Making money quickly is easier than it seems thanks to these apps. Remember that with Común you get a free checking account and a VISA debit card with access to more than 57,000 ATMs.
About Común
Común aims to support the Latino community in the United States. It offers a debit account that can be opened with more than 100 valid Latin American IDs and an app available in Spanish.
Visit Común's website or download the app for free to learn more about the full offer and applicable terms.
Olivia Rhye
Community Partner


Instant payments
Safe and fast ways to send money without a bank account
8 min de lectura
Did you know it is possible to send money without having a bank account? The lack of access to financial services is a problem that negatively affects the quality of life of thousands of immigrant workers in the United States.
For example, according to a recent survey, the rate of the Latino community in the United States without a bank account dropped from 15% to 10% over the last two years. However, it remains high compared to the national average of 4.5%.
While having a bank account facilitates financial transactions such as transfers, in-store payments, and online purchases, there are now alternatives that allow you to access banking services without needing an account.
Below, you will discover how to transfer money from one card to another without an app or bank account, as well as the safest and simplest methods available to you.
Sending Money Online
Not having a U.S. bank account is not an obstacle to sending money domestically or internationally, as there are methods widely used among immigrant workers who regularly send remittances and conduct other transactions using prepaid cards and cash payments.
International Money Transfer Providers
This is one of the most popular ways to send money without a bank account due to the accessibility, variety of payment methods, and broad coverage typically offered.
International money transfer providers are companies that specialize in facilitating money transfers from one country to another. The key features of these services include:
- Specialization in international money transfers, unlike traditional banks, which have certain limitations, such as high commissions, unfavorable exchange rates, extensive delivery time, and participation of intermediaries that increase costs.
- More affordable fees.
- Various sending methods.
- Multiple Money Transfers Locations
How to Send Money Without a Bank Account Through an International Transfer Platform
Comun allows you to send money to your loved ones for a modest transfer fee starting at USD 2.99 up to the applicable limits. It is very simple; just follow these steps:
1. Open your account with Comun; it will only take a few minutes!
2. Choose the most convenient delivery method for your recipient, such as cash pick up at a physical store like Oxxo, Grupo Elektra, 7 Eleven, and more.
3. You may also send money directly to a bank and have it picked up at one of its branches.
4. Track the delivery directly in your Comun mobile application.
Comun is an excellent option for our community, as it provides Spanish-language service, which is highly appreciated by the immigrant community. Open your account today and start sending money without complications.
What Information Do You Need to Send Money Without a Bank Account?
To send money without a bank account, you only need the following information about your recipient:
- Full name of the recipient, exactly as it appears on their official ID.
- Recipient’s phone number.
- If the transfer is made to a bank account, you will also need:
- Recipient’s address.
- Bank account number, depending on the receiving country.
P2P Services
P2P (peer-to-peer or person-to-person) services allow immediate money transfers between individuals without intermediaries. These options are useful for everyday needs such as paying rent, shared services, splitting transportation costs, and sending money to your relatives in the US or internationally.
How to Send Money Without a Card Using P2P Services
- Choose a reliable provider, such as Cash App or Venmo.
- Enter the recipient’s phone number in the mobile app.
- Confirm the transaction and track it.
Sending Money by Mail
Other alternatives involve sending a cashier’s check, a certified check, or a money order through the postal service.
Cashier’s Check
This type of check is issued with the bank’s funds. The customer must pay in cash or directly from their account, and the check is made payable to the recipient.
Certified Check
This check is issued using the customer’s funds. The issuer must have a bank account so that the bank can verify the availability of funds. The recipient may cash the check directly at a bank branch.
Money Order
Another way to send money without a bank account is by using a money order, which is a type of prepaid payment order. To do so, you will need to:
1. Go to a post office or authorized retailer, such as USPS or Walmart, to purchase a money order.
2. Write the beneficiary’s name in the “pay to the order of” section.
3. Write your name in the “purchaser” section.
4. Sign in the space designated for the purchaser, generally on the front of the document.
5. Keep the receipt with the serial number.
6. Pay the amount to be sent plus applicable service fee.
7. Send the money order via regular or certified mail.
8. Write the recipient’s address in the center of the envelope and the sender’s address in the upper left corner.
9. Purchase a postage stamp at the post office and attach it to the envelope.
10. Drop off the envelope at the post office.
The recipient may cash the money order at an authorized branch upon presenting valid personal identification.
The downside of this alternative is that it takes longer to arrive, as it relies on a traditional mailing method.
Sending Money With Prepaid Load
There are other options available to send money without a bank account, such as prepaid cards and mobile applications.
Reloadable Prepaid Cards
Reloadable prepaid cards function similarly to debit cards, with the main difference being that they are not linked to a bank account. They also allow you to pay for services and make online purchases.
To send money using a prepaid card, you only need to:
1. Identify an international money transfer service that supports prepaid cards, such as Western Union or MoneyGram.
2. Select your preferred provider and choose the prepaid card option on their website.
3. Enter the recipient’s information, making sure it is compatible with the selected platform.
4. Confirm the transfer and pay the amount plus the applicable service fee.
Done! The recipient will receive the money on the prepaid card as if it were a bank transfer.
Mobile Wallets/Applications
Lastly, you may opt for mobile wallets or applications that offer money transfer capabilities. Some examples include Cash App, Venmo, and Remitly, which provide access to an mobile app you can use to send and receive money.
These applications do not require a bank account and are user-friendly. Some also offer physical cards that function similarly to debit cards.
7 Essential Tips for Sending Money Without a Bank Account
1. Verify the Identity and Information of the Recipient
Ensure that the recipient’s information, such as name, account number, or phone number, is entered correctly. Any discrepancies could prevent the recipient from collecting the funds.
2. Compare Fees and Exchange Rates
Each provider has its own rates depending on the receiving country, amount, and exchange rate. Remember, with Comun you do not pay excessive fees, and you ensure your family receives more for less.
3. Know the Sending Limits
Some platforms have sending limits that should be considered before selecting a service. For instance, Western Union has a daily limit of USD 7,499, while Cash App allows up to USD 7,500 per week for verified accounts.
4. Keep All Receipts and Reference Numbers
Even though these methods are secure, it is important to keep receipts and reference numbers in case a clarification or issue arises.
5. Use Reputable and Secure Services
It is essential to ensure that you use a trusted service. Check online reviews and verify that the provider has an official website and/or physical offices.
6. Be Cautious of Scams
Unfortunately, scams are common around financial services. No legitimate institution will request passwords or verification data. Always access official websites. If in doubt, visit an authorized branch.
7. Consider Delivery Time
Most options allow you to complete transfers in minutes, but some may take several days. Consider this before choosing your preferred service.
Frequently Asked Questions
Is it safe to send money without a bank account?
Absolutely. Comun is backed by leading financial institutions to protect your funds up to the applicable limits. Additionally, you can track your transfer directly through the Comun mobile app.
How much does it cost to send money without a bank account?
Comun offers a transfer fee starting at USD 2.99, regardless of the amount you send up to the applicable limits. Your first transfer is commission-free!
How long does it take for the money to arrive?
Cash is typically available within approximately 1 hour at the selected store or bank branch.
What documents do I need to send/receive money without an account?
You need the full name of your recipient, and they must present official identification.
International Money Transfers
How much does it cost to send money to Mexico from the United States? A 2026 guide
8 min de lectura
Sending money to Mexico with Común costs as little as $2.99 per transfer, and your first transfer is at no cost. The exchange rate is shown in full before you confirm, with no hidden charges, and most transfers arrive within minutes.
How much does it cost to send money to Mexico from the United States? A 2026 guide
In most cases, the total cost depends on three factors: the transfer fee, the exchange rate, and any charges applied to the recipient of the money. The truth is that the final cost can range from a few dollars to something more significant as it is impacted by the service fee, delivery method, and speed.
Remittances have become so important to the Mexican economy that Mexico remains the world's second-largest recipient of remittances, behind only India. According to BBVA Research, Mexico received $61.8 billion USD in remittances in 2025, representing 3.4% of the country's GDP. Today, there are dozens of apps and money transfer services available for sending money from the United States to Mexico. Some focus on speed, others on cash pickup access, and some prioritize lower overall costs.
In this guide, we'll break down what actually affects the cost of a transfer, compare popular services, and explain how to find the option that works best for you and your family.
How much money can I send to Mexico?
One very important aspect to consider is the amount allowed by money transfer apps, as well as any restrictions included in their terms and conditions.
In general, there is no legal limit imposed by the United States government, but each platform has its own standards and regulations that determine transfer limits and guidelines for international money transfers.
For example, these are some of well known providers that offer money transfers to Mexico and their respective limits:
- Western Union: up to 5,000 USD per transaction.
- MoneyGram: up to 10,000 USD per transaction.
- Xoom: Level 1 is limited to $2,999 per day while the third level allows up to $50,000 per day.
If you are looking for a straightforward way to send money to Mexico, Común can be an excellent alternative. New users can enjoy the first money transfer free and then pay a fee starting at 2.99 USD per transfer, up to applicable limits.
What is the best way to send money from the United States to Mexico?
There are several ways to send money from the United States to Mexico, whether through traditional banks or specialized international money transfer services. These are the main options to do it:
Bank-to-Bank transfers
One of the most common ways to send money is through wire transfers from one traditional bank to another. The advantage of this method is that it can be secure because it is backed by official financial institutions. However, transfers can take longer and involve higher fees.
To send funds this way, you must have a U.S. bank account and use the recipient's SWIFT code.
The transfer cost depends on the receiving bank in Mexico. For example:
- BBVA charges approximately $30 USD + VAT to receive an incoming international transfer.
- Citibanamex estimates suggest around $15–20 USD + VAT for incoming transfers, but confirming directly with the bank is recommended.
These fees apply regardless of the amount sent, therefore it is important to confirm the fees with each bank.
Cash transfers
Another option, which may be more accessible for people without a bank account, is sending cash that can be picked up at different locations across Mexico.
To send cash, it is common to visit a physical location of the provider that offers this service, such as a Western Union office. Once there, you pay the amount you want to send plus the assigned fee. To collect the funds, your family members must present a valid government ID at one of the participating locations, such as Oxxo, Banco Azteca, Walmart, or others. However, many service providers such as Western Union also have digital offers.
Although this can be a convenient alternative for people who mainly manage cash, it may also come with potential drawbacks, such as fees that vary depending on the amount sent and exchange rates that might be less competitive compared to some digital transfer services.
Apps and digital platforms
Another option for sending money to Mexico is through apps and digital platforms that specialize in international money transfers, such as Wise, Félix Pago, Ria Money Transfer, and Común. Many of these services are available on both iOS and Android and may offer lower costs compared to some cash transfers or traditional bank wires, depending on the provider and delivery method. Some platforms focus mainly on money transfers, while others may also include additional financial features, such as a debit card or access to a U.S. bank account.
To access these services, you must create an account on the provider's website or app. In addition, some apps require identity verification using personal information such as your SSN (Social Security Number) or ITIN.
You can send money directly through the provider's app or, in some cases, even through WhatsApp, and choose the preferred delivery method. Some services also offer cash pickup options for recipients. For example, Común accepts more than 100 Latin American IDs for account verification, it allows you to send money through the app or via WhatsApp, and offers cash pickup options across Mexico.
Before choosing an app to send money to Mexico, we recommend comparing the most popular options and evaluating which one best fits your needs and those of your family.
Five popular mobile apps for sending money to Mexico from the United States
There are many apps available for sending money from the United States to Mexico, but costs, delivery speeds, and exchange rates can vary depending on the provider and transfer method. Comparing multiple options can help you find the service that best fits your needs.
| Service | Payment Options | Fee | Delivery Options | Exchange Rate | MXN per 1,000 USD | Speed |
|---|---|---|---|---|---|---|
| Común | Bank account, debit card, cash | Starting at 2.99 USD | Bank account or cash pickup | Competitive | ~17,000 MXN | Minutes to hours |
| Western Union | Bank, cash, card | Varies depending on amount | Bank, cash, wallet | Exchange rate with spread applied | ~16,920 MXN | Minutes to days |
| Félix Pago | WhatsApp, cash, card | $2.99 USD for bank account and $4.98 USD for cash pickup transfers | Bank account and cash | Competitive | ~17,000 MXN | Instant |
| Ria Money Transfer | Bank account (ACH), debit card, credit card, cash | Starting at $0.99; free for bank transfers up to $15,000 | Bank account, cash pickup, mobile wallet | Exchange rate with spread applied | ~16,900–17,000 MXN | Minutes to days |
| MoneyGram | Bank account, debit card, credit card, cash (at agent) | Free for bank transfers up to $10,000; $49.99 for $10,001–$15,000; $5+ for cash sends | Bank account, debit card, mobile wallet, cash pickup | Exchange rate with spread applied | ~16,800–16,950 MXN | Minutes to hours |
The amount received in MXN for every 1,000 USD can change throughout the day due to fluctuations in exchange rates, provider fees, and delivery methods. The rates shown here are for illustrative purposes only and may not reflect the exact amount available at the time of your transfer. Before sending money, it may be helpful to compare the current exchange rate and total transfer cost across providers. Común's comparison tool can help you check and compare available rates in real time.
What determines the real cost of sending money to Mexico?
When comparing money transfer services, many people focus only on the advertised transfer fee. But the real cost of sending money to Mexico usually depends on three different factors:
- The transfer fee.
- The exchange rate spread.
- Charges applied to the recipient.
Understanding these costs can help you compare services more accurately and avoid situations where your family receives less money than expected.
Transfer Fee
The transfer fee is the most visible cost. This is the amount the provider charges to process the transaction.
Some services charge a flat fee per transfer, while others adjust the fee depending on the amount sent, the payment method, or how quickly you want the money delivered. In some cases, companies may offer promotional pricing or even a free first transfer for eligible users.
Although low fees can help reduce costs, they may not always result in the lowest overall transfer cost once exchange rates and other charges are taken into account.
Exchange rate spread
The exchange rate spread is one of the most important and often least visible parts of the total cost.
Some service providers do not use the exact market exchange rate you find on Google or financial websites. Instead, they add a margin, also known as a "spread," when converting USD to MXN.
This means that even a small difference in the exchange rate can significantly reduce the amount your recipient receives in pesos, especially on larger transfers.
A service with a slightly higher transfer fee but a more competitive exchange rate may actually deliver more money to your family in Mexico.
Recipient charges or withdrawal costs
In some cases, additional costs may appear after the transfer is sent. Depending on the provider and delivery method, the recipient could face charges for cash pickup, ATM withdrawals, bank processing, or currency conversion. Some banks and pickup locations may also apply their own service fees.
These extra costs are important because they directly affect the final amount your recipient can actually use.
Compare the full cost
The best way to compare money transfer services is to look at the total outcome: how much you pay, how much your recipient receives, and how long the transfer takes.
If possible, it is recommended that before sending money, you review the transfer fee, compare the exchange rate, and check whether there are any recipient-side charges. Small differences across these three factors can add up quickly over time.
To compare real-time transfer costs, exchange rates, and delivery options, you can use tools like Común's compara before making your transfer.
How can I send money to Mexico with Común?
With Común you can send money to your family and friends in Mexico directly from Común's mobile app without leaving your home.
You can follow these steps:
- Open your Común mobile app.
- On the main page, select "Send a Remittance."
- Select the recipient you want to send the international transfer to.
- You can register a recipient using their banking details, including full name, bank name, and phone number.
- After registering the recipient, enter the amount you want to send and review the transaction costs.
- Confirm the details and select "Confirm International Transfer."
- The recipient should receive the money within minutes. If you select a store pickup, the person can collect the money about 30 minutes after confirming the transaction.
- You can check the transfer status in your Común mobile app by clicking on the transaction.
Transfer fees start at 2.99 USD per transaction, up to applicable limits.
Send money to Mexico easily and securely
Today, there are more options than ever for sending money from the United States to Mexico. Whether you prefer the familiarity of a traditional bank, the convenience of cash pickup, or the flexibility of a digital platform, the right choice will depend on your own situation.
Comparing fees, exchange rates, delivery methods, and transfer times may help you find an option that better fits your needs and the way your family prefers to receive money.
With Común you can open an account using more than 100 Latin American IDs, send money from the comfort of your phone and access multiple delivery methods across Mexico.
How much does it cost to send money to Mexico with Común?
Fees start at $2.99 per transfer. Your first transfer is at no cost. Común shows the exchange rate and the exact amount your family will receive before you confirm — nothing changes afterward.
How long does it take for the money to arrive?
Most transfers arrive within minutes. The exact time depends on the delivery method your family chooses (bank deposit or cash pickup).
Where can my family pick up the money in Mexico?
Común offers cash pickup at locations like Elektra and Oxxo, plus direct deposit to a Mexican bank account.
Frequently asked questions
What's the minimum fee to send money to Mexico with Común?
Starting at $2.99 per transfer. Your first transfer is at no cost. The final amount your family receives is shown in full before you confirm, with no hidden charges.
Is Común's exchange rate competitive?
Yes, Común offers a competitive exchange rate and shows you the exact amount in pesos before sending, so you know exactly how much your family will receive.
Can I send money to Mexico even if my family doesn't have a bank account?
Yes, your family can pick up the cash at locations like Elektra or Oxxo without needing a bank account.
How long does a transfer to Mexico take?
Most transfers arrive within minutes, depending on the delivery method chosen.
Do I need a Común account to send money to Mexico?
Yes, remittances are sent from your Común account inside the app by selecting "Send a remittance."
Is there a limit on how much I can send to Mexico?
Transfer limits vary by account; you can check them directly in the app before confirming your transfer.
Immigration
EB-3 visa: Requirements and how to apply in 2025
8 min de lectura
If you’re looking for a feasible way to live and work in the United States, you should know the details of the EB-3 visa, a permit that offers skilled workers, professionals, and other unskilled workers the possibility of accessing various job opportunities in the country.
This visa is the most common route to live and work legally in the U.S. because, unlike the EB-2, it covers a broader range of profiles. It also facilitates obtaining permanent residence.
The application process is often somewhat confusing and slow. Therefore, here we explain what the EB-3 visa is, its requirements, the employer’s role, benefits, processing time, costs, and the step-by-step process to apply.
What is the EB-3 visa and who qualifies?
The EB-3 is a visa category for obtaining a Green Card through authorization granted to foreign workers who have a job offer issued by a U.S. employer.
In turn, this visa is divided into three main categories:
- Skilled workers: individuals with at least 2 years of job experience in a given field.
- Professionals: individuals with a university degree equivalent to a U.S. bachelor’s degree, whose positions require academic training.
- Other (unskilled) workers: roles requiring less than 2 years of experience—generally positions requiring steady labor.
For any of these subcategories, the employer plays a central role by filing the labor certification (PERM) with the Department of Labor to show that no U.S. workers are available to fill the job.
Main EB-3 visa requirements
The EB-3 visa has specific requirements depending on the subcategory. Below is a comparative table.
| Requirements | Employer’s role |
|---|---|
| Skilled workers At least 2 years of work experience or specialized training. |
Prove that the position requires at least 2 years of experience or training. |
| Professionals University degree equivalent to a U.S. bachelor’s. |
Show that the position requires a bachelor’s and that the candidate meets it. |
| Other (unskilled) workers Less than 2 years of work experience. Ability to perform labor-intensive tasks. |
Indicate via PERM that the position requires under 2 years of experience and is not temporary or seasonal. |
Regardless of subcategory, a permanent job offer in the United States is always required. The employer must also complete DOL-approved labor certification showing the need to hire a foreign worker for the position.
Next, Form I-140 (Immigrant Petition for Alien Worker) is filed, in which the employer asks USCIS to classify the worker under an EB-3 category.
For example, if a medical practice needs a physician, it files Form I-140 to substantiate the candidate’s experience.
Benefits of meeting EB-3 visa requirements
Obtaining an EB-3 work visa brings several advantages not only for the applicant but also for their family, for example:
- Job stability in the U.S.
An EB-3 visa allows you to secure lawful employment with a U.S. company, helping you achieve financial stability and a better quality of life for your family.
- Pathway to lawful permanent residence.
The EB-3 is also a route for your immediate family to obtain a family-based Green Card, allowing you and your family to live legally in the United States.
- Opportunities for professional and personal growth.
Building a life in the United States brings benefits such as access to higher wages, a broader job market, education for your children, Social Security, and more. This enables long-term financial planning to acquire property and services needed for your family’s well-being.
How to apply for the EB-3 visa step by step
Step 1. Determine eligibility
First determine which of the three categories fits your profile and verify that you meet the requirements based on your education level, work experience, and the type of job you’re applying for.
Step 2. Labor certification (PERM)
The employer must then file the labor certification (PERM) with the Department of Labor (DOL) to show no U.S. workers are available for the position and that the offered wage meets legal standards. This step is essential; without approval the process cannot proceed.
Step 3. File Form I-140
Once PERM is approved, the employer must file the I-140 petition with USCIS to confirm the job relationship and the company’s financial ability to pay the worker’s wage.
Step 4. Adjustment of status or consular processing
After I-140 approval, wait for visa availability in the Visa Bulletin, then proceed accordingly:
- Adjustment of status: if you’re already in the U.S., file Form I-485
- Consular processing: if you’re outside the U.S., file Form DS-260 through the National Visa Center and attend an interview.
Común supports your daily financial life in the U.S.
Here we’ve shown what the EB-3 visa is, the requirements for each subcategory, the benefits, and the application process.
As you start your new life in the U.S., make sure you have an ally who understands you.
Común is a financial platform that helps you manage your everyday needs in the United States. Through the Común mobile app and an intuitive platform, you can create your checking account with a qualifying official identification from your home country. It also makes sending remittances to Latin America, simple and transparent, with clear and competitive fees, up to the applicable limits.
Open your Común account today and start managing your money in the U.S.
Frequently Asked Questions (FAQ)
If you still have questions, see this section.
How long does the EB-3 process take?
The timeline varies with workload, but the full process is estimated at roughly 1 to 3 years.
How much does the EB-3 visa cost in the United States?
- Form I-140: $715
- Form I-485 (adjustment of status): $1,440
- Form DS-260 (consular processing): $325 per applicant
Can I include my family with the EB-3 visa?
You can include your spouse and unmarried children under 21 to apply for residence as derivative beneficiaries and obtain the Green Card at the same time.
Do I need a job offer to apply?
Yes, the EB-3 always requires a job offer, unlike the EB-2 NIW subcategory.
Financial Education
How to fill out a check in the United States in 5 simple steps (+ Example)
8 min de lectura
Have you ever filled out a check? Although most transactions today are digital, knowing how to fill out a check is essential—especially if you are just beginning your financial life.
According to recent data, one-third of Americans paid by check in 2024, demonstrating that checks still play an important role in the U.S. economy.
You might consider checks an outdated payment method; the reality is that they are useful in specific situations. For that reason, we will explain what a check is, the different types of checks, and how to complete them properly.
What Is a Check and What Is It Used For?
Despite the digital era, checks remain a relevant traditional payment method due to their formality and traceability. They are used for rent payments, purchases, and service payments.
Additionally, checks are a common payment method among the immigrant community, who often use them while adapting to the U.S. banking system.
But what exactly is a check and what are its characteristics? It is a physical document issued by an individual or business (the drawer) to order a bank to pay a specified amount to a third party. For the payment to be processed, the drawer must have sufficient funds in their checking account.
In general, a check contains the following information:
- Name of the drawer, whether an individual or a business
- Name of the payee
- Financial institution where the money will be drawn
- Amount to be paid, both in numbers and in words
- Signatures of the drawer
What Are the Different Types of Checks?
There are different types of checks in the United States. In this case, we will focus on the personal check, although you may choose the option that best suits your needs.
Personal Check
A personal check is a payment order issued by an individual to another individual using the funds in a checking account.
What Is a Personal Check Used For?
The most common uses for personal checks include:
- Rent and utility payments
- Purchase of everyday goods
- Legal agreements requiring documentary support
Certified Check
A certified check serves the same purpose as a personal check but is reviewed and guaranteed by the issuing bank, which verifies that the drawer has sufficient funds and holds them until the check is cashed.
A certified check provides certainty of available funds, making it a more secure method for making and receiving payments.
Cashier’s Check
Unlike a personal check, a cashier’s check is issued directly by the bank, offering greater security for the payee, as the bank is responsible for issuing and safeguarding the funds.
To obtain a cashier’s check, the drawer must visit a bank branch and pay the amount to be transferred. The bank then issues the check in the name of the payee, guaranteeing that it can be cashed using the institution’s own funds and not a personal account.
It is commonly used for high-value purchases such as homes and vehicles.
Money Order
While not strictly a check, it is a traditional payment method with similar functionality.
A money order is a financial instrument that allows funds to be sent via traditional mail using a certified check, which must be purchased and paid for by the drawer at an authorized location.
It allows secure money transfers without requiring a bank account.
How to Fill Out a Check in the U.S.
Before issuing this type of payment order, you must know how to do it properly. Below is an example of how to fill out a check easily, starting from step one:
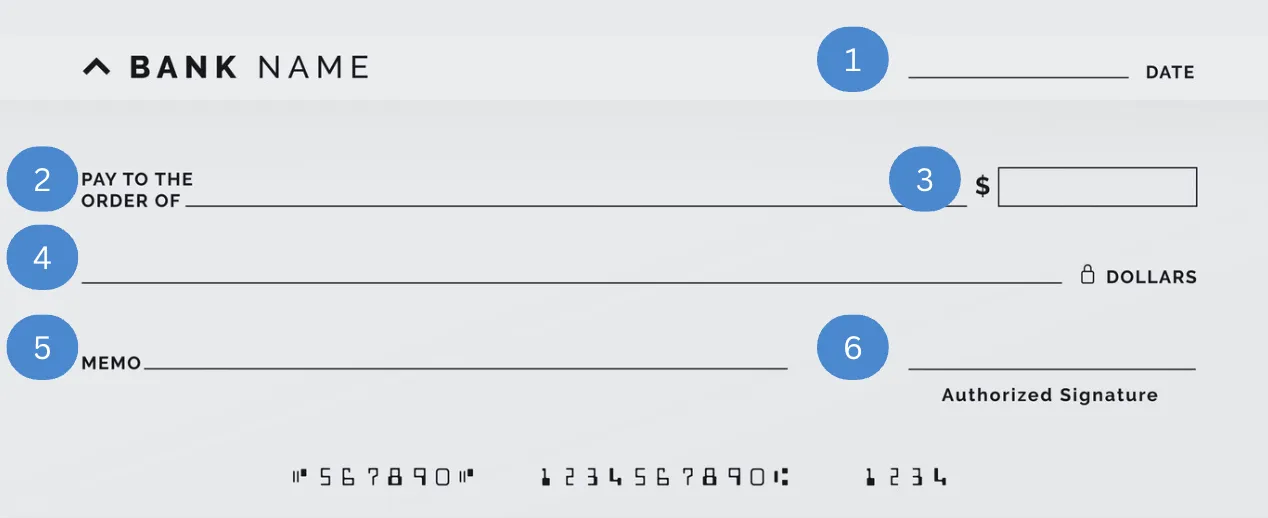
1. Write the Date
Remember that in the United States, the date format is mm/dd/yyyy.
2. Payee’s Name
Write the full name of the person to whom you are issuing the check, exactly as it appears on their official identification.
3. Amount in Numbers
Write the numerical amount clearly.
4. Amount in Words
Write the amount in words, including cents.
5. Add a Memo
You may include a note specifying the reason for the payment.
6. Sign the Check
Sign the check legibly in the space designated for the drawer.
7. Review the Information
Ensure that all information is accurate to avoid issues for the payee when cashing the check.
It is essential to complete checks legibly, without strike-throughs or corrections, as these may invalidate the document.
How to Correctly Write Numbers in Words on a Check
Writing amounts in words may be confusing when dealing with U.S. dollars. The following points should be kept in mind:
- Dollar amounts must be written in full words
- Cents must be written as fractions
- Avoid using dollar symbols or similar notations
- If there is leftover space at the end of the line, draw a line to prevent fraud
- For example, $1,000.75 is written as: One thousand and 75/100 dollars
Cash Checks and Manage Your Money Easily with Comun
As you can see, knowing how to fill out a check is useful for sending and receiving money in the United States. It is a reliable and accessible alternative if you do not have a banking account.
However, issuing and cashing a check can also require significant time and effort. That’s why you can skip the trip to the bank, avoid wasting time or money on gas, and cash your check directly from your phone using Comun—no lines, no questions, no complications.
Discover Comun, the only platform designed to serve the needs of immigrant communities in the United States, with support available in Spanish.
Why Choose Comun?
- Open your account with an official ID from your country
- Access a mobile app specifically designed for immigrants in the U.S.
- Make payments, receive your salary, and manage your finances
- Send money to your loved ones in LATAM for just a $2.99 transfer fee
Frequently Asked Questions
Still have questions about how to fill out a personal check? See our FAQ section.
What if I Make a Mistake Filling Out a Check?
If there are strike-throughs or inconsistencies in the amounts, the check must be voided and a new one used.
How Do I Void a Check?
Write the word VOID in large letters on the front of the check.
What Information Appears on the Back of a Check?
The back of the check contains the endorsement, meaning the payee’s signature for cashing the check.
Financial Education
Apps like Chime: Best alternatives for 2026
8 min de lectura
Apps like Chime: Best alternatives for 2026
Digital banking apps have changed how many people in the United States manage their money. Instead of visiting physical branches, people can now open accounts, receive direct deposits, send payments, and manage spending directly from their phones.
Among these apps, Chime has become one of the most recognized names in digital banking. However, for many immigrants in the United States, traditional fintech apps may not fully meet everyday financial needs. Some people may need an app that supports ITIN-based onboarding, offers easier ways to send money to Latin America, or provides customer support in both English and Spanish.
What is Chime and why look for alternatives?
Chime is a financial technology company that offers mobile-first banking services through partner banks. Its features include early direct deposit, debit cards, fee-friendly banking options, and automatic savings tools. Some users may look for alternatives because they want: international remittance options, ITIN or passport-based onboarding, bilingual customer support, or cash transfer flexibility.
Comparison of apps like Chime (2026)
| App | Sin comisión mensual | Acepta ITIN/Sin SSN | Soporte en español | Remesas internacionales | Transferencias P2P | Depósito directo anticipado |
|---|---|---|---|---|---|---|
| Chime | Sí | No | No | No | No | Sí* |
| Común | Sí* | Sí | Sí | Sí | Sí | Sí* |
| Current | Sí | No | No | No | Sí | Sí |
| Varo | Sí | Sí (ITIN) | No | No | No | Sí |
*Terms and conditions apply. Verify current requirements with each provider.
Común — The alternative designed for Latino immigrants
Común is a digital financial platform built specifically for the Latino community in the U.S. Unlike Chime and other digital banking apps, Común accepts more than 100 valid Latin American IDs to open an account, offers 24/7 customer support in Spanish, allows sending remittances to Latin America starting at $2.99, and has an app available fully in Spanish. Visit comun.app to learn more.
Varo
Varo accepts ITINs for account opening, making it more accessible for some immigrants. It offers basic banking features without monthly fees. However, it does not offer international remittances or Spanish-language support.
Current
Current offers digital banking with early direct deposit and P2P transfers. However, it does not accept ITINs for account opening and has no Spanish support or international remittances.
Which is the best Chime alternative for immigrants?
It depends on your specific needs. If you need remittances to Latin America, Spanish-language support, and the ability to open an account without an SSN, Común may be the most complete option.
FAQ
Can I open a Chime account without an SSN?
Chime generally requires an SSN to open an account. For immigrants who do not yet have an SSN, there may be better alternatives like Común.
What is the best banking app for Latino immigrants?
Común is designed specifically for Latino immigrants in the U.S. with Spanish support, account opening with Latin American IDs, and international remittances.
Común is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank, Member FDIC.
International Money Transfers
How to make an international money transfer? Costs, times and requirements
8 min de lectura
International money transfers can be sent via bank wire, money transfer apps, or remittance services — each with different fees, speed, and delivery options. With Común, transfers to Latin America start at $2.99, with most arriving within minutes.
For immigrants in the United States, sending money to their home countries regularly is essential. Therefore, it is important to have access to affordable and accessible financial services.
If you want to know how to make an international money transfer, it is crucial to first compare the different providers of this service and choose the one that offers the most advantages for you and your family.
Comun stands out as a popular option among immigrants because it allows them to send money abroad from the United States, offering advantages in terms of cost, speed, and other key factors.
Below, we provide a comparison table that includes Comun and traditional financial institutions in the United States, such as Bank of America and Wells Fargo:
| Comun | Traditional Financial Institutions | |
|---|---|---|
| Fee | Transfer fee starting at 2.99 USD up to applicable limits | From 10 to 45 USD, depending on the bank |
| Intermediary fees | $0 USD | May generate extra fees from intermediary banks |
| Exchange rate | Competitive | Higher margin than official |
| Speed | Instant to a few minutes (average 8) | From 1 to 5 business days |
| Estimated total fee | 2.99 USD transfer fee + exchange rate, with no extra charges (The first transfer has no fee. Subsequent transfers have a fee starting at $2.99 USD, up to the applicable limit. ATM or intermediary charges may apply; check the app for more details). | From 20 to 60 USD, due to fees and less favorable exchange rates |
How Does an International Money Transfer Work?
The first point to understand is the types of bank transfers available, as this determines the final cost of sending an international money transfer.
In the United States, there are two types of international money transfers: through traditional banks or through specialized services for sending money abroad.
International Money Transfers via Traditional Banks
- Supported by official U.S. financial institutions and security measures, including:
- Identity verification (KYC/CIP) and ongoing AML monitoring (BSA).
- OFAC sanctions screening for senders and recipients.
- Consumer protections for remittances under Regulation E (pre-transfer disclosures, cancellation rights, and error resolution).
- Network and messaging security standards (e.g., SWIFT Customer Security Program).
- Multi-factor authentication and encryption for online banking access.
- A U.S. bank account is mandatory
- Operates through the SWIFT code
- Generates higher fees due to intermediaries
- Transfer time may take up to 5 business days
International Transfers via Specialized Applications
- Operates through digital networks connected with banks or physical branches in each recipient country
- Lower fees, as they do not use intermediaries and offer more competitive exchange rates
- Money transfers are completed within minutes or hours
- A U.S. bank account is not mandatory to use these services
Before paying unnecessary fees, make sure to choose the best international money transfer provider and make the most of your money.
Steps and Requirements for Making an International Money Transfer
Below, we outline what is needed to easily make an international bank transfer from the United States, whether you choose a traditional bank or a specialized application for this type of service:
1. Choose a Provider
Some of the traditional banks you can use are Chase, Bank of America, Capital Bank, Citibank, and Wells Fargo. If you don't have a US bank account, you'll need to make sure you have the necessary requirements to open an account, such as a Social Security Number (SSN). For the aforementioned banks, you can present an ITIN instead, along with a government-issued ID.
Another factor to consider is how long an international money transfer takes, as traditional banks usually take longer due to intermediaries involved in the process.
If you prefer a specialized application for international money transfers due to the flexibility they offer compared to banks, an excellent alternative is Comun, which allows you to transfer money from your phone without complications or intermediaries.
2. Create an Account
General Requirements for Opening an Account at a U.S. Bank
- Valid passport or immigration document
- Social Security Number (SSN)
- Individual Taxpayer Identification Number (ITIN)
- Proof of address in the United States
- Some banks require an initial deposit of approximately $25 USD
Depending on the bank, you may open the account online or by visiting a branch for data verification.
Requirements for Opening an Account with Comun
- Mobile phone compatible with Android or iOS
- Email address
- Official foreign identification
- Have a US residential address
In both cases, you will have access to a debit card and a mobile application that will allow you to make international money transfers and other transactions from the palm of your hand.
3. Enter Transaction Details
Once you activate your account, enter the information required for an international money transfer:
- Full name of your recipient, as it appears on their official ID
- Recipient’s phone number
- Recipient’s address (only if sending money to a bank account)
- Recipient’s account number (only if sending money to a bank account)
- SWIFT code (if transferring through a traditional bank)
Then, enter the amount you wish to send.
Comun and other specialized applications also allow cash pickup at physical locations, so your recipient does not need a bank account.
4. Review Costs and Rates
Next, review the international money transfer fees as well as the exchange rate, as these will impact the final amount your recipient receives.
The cost of an international money transfer depends on several factors, which we detail below.
5. Send the Money
Once you confirm that the information entered is correct, authorize the transfer, including any additional fees.
Comun allows you to track your transfers through its application, whether you choose to send money to a bank account or opt for cash pickup at a physical location.
Remember that transfer speed depends on the platform, and traditional banks can take up to 5 business days to complete these transactions.
6. Confirm Receipt
Finally, confirm with your recipient that the transfer was received within the stipulated timeframe. You can generate a transaction receipt directly in the mobile application.
Everything About the Cost of Sending Money Abroad from the U.S.
International money transfers are a common practice among immigrants in the United States.
That is why it is essential to detail the factors that influence the cost of transfers, as well as the best options for sending remittances to your family quickly and without complications.
These are the main factors to consider when calculating the cost of your international money transfers:
- Transfer Fees
International transfers incur a fee, which varies depending on the platform, whether it's a traditional bank or a specialized app.
Another factor that affects the fee level is the method used to send the money. The price can vary depending on whether the transaction is made through a website, an app, or at a physical branch.
International money transfer fees at traditional banks vary depending on the financial institution. Here are some examples:
- Bank of America: $45 USD
- Wells Fargo: from $25 to $40 USD
- Citibank: from $25 to $35 USD
- Truist Bank: $65 USD
On the other hand, some mobile applications offer international money transfer options for less than $3 USD, which is much more beneficial for the economy of foreign workers.
- Exchange Rate
The exchange rate also significantly impacts the final amount your recipient receives. It refers to the value applied by the platform when converting the dollar amount to the local currency.
Traditional banks generally use a lower rate than the official rate. For example, if the Mexican peso is officially 18.00, banks might apply approximately 17.20 MXN.
This means that if you send $300 USD, your recipient could receive about $13 less (240 MXN less), not counting the bank fees, which make the cost even higher.
- Hidden Fees
In addition to international money transfer fees, traditional banks may charge additional fees if intermediary banks are involved in processing the transfer.
We recommend checking all costs involved and choosing a competitive option that does not reduce the total amount your family will receive.
Comun is an excellent alternative for making international money transfers, as your first transfer fee is waived, and subsequent transfers have a fee starting at $2.99 USD per transfer, up to applicable limits, with no hidden fees or intermediaries.
Review our comparison table between traditional banks and Comun at the beginning of this article, and choose the best option for your money.
Want to Make Secure International Money Transfers? Do It Easily with Comun
In this article, we presented how to make an international money transfer from the United States through traditional banks or specialized applications such as Comun, an excellent choice for immigrants.
Comun is the solution for bringing immigrant families closer together through affordable and low-cost remittances.
Why Choose Comun for International Money Transfers?
- Easily open your account with official documentation from your country
- Send money to your family with a transfer fee starting at $2.99 USD, up to the applicable limits.
- Your money will arrive within minutes
- Access a mobile application and Visa debit card for better control of your finances
Discover an easy and fast way to access the financial services you deserve. Open your account with Comun and forget about complications.
What are the main ways to send money internationally?
Bank-to-bank wire transfers, dedicated money transfer apps, and remittance services are the three main options, each with different costs and delivery times.
What should I compare between international transfer options?
The fee, exchange rate, delivery speed, and whether the recipient needs a bank account or can pick up cash.
How does Común handle international transfers to Latin America?
Transfers start at $2.99, with your first transfer at no cost. Delivery options include bank deposit or cash pickup at locations like Elektra and Oxxo in Mexico, with most transfers arriving within minutes.
Frequently asked questions
What's the cheapest way to send money internationally?
It depends on the corridor and amount; always compare the fee AND the exchange rate, since a low fee can hide a worse exchange rate.
Do I need a bank account in the destination country to receive money?
Not always — some services, including Común, offer cash pickup options that don't require a bank account.
How long do international transfers usually take?
It varies by method — bank wires can take days, while modern remittance apps like Común often deliver within minutes.
Are international money transfers safe?
Yes, when using a licensed provider that's transparent about fees and exchange rates before you confirm.
What information do I need to send an international transfer?
Typically the recipient's name, destination country, and either their bank account details or pickup preference, depending on the method.
Does Común charge for international transfers?
Fees start at $2.99 per transfer, with your first transfer at no cost.
Financial Education
How to Call Colombia from the United States in 2025
8 min de lectura
How to call Colombia from the U.S. in 2025 easily and affordably
The Colombian community has a strong presence in the U.S., with many immigrants arriving each year to visit, live, study, and work.
Staying in touch with family across borders matters. That’s why it’s useful to know the different ways to make international calls from the U.S. While it can seem tricky, it’s easy if you have the right codes.
If you want to call loved ones back home in Colombia, below you’ll find step-by-step dialing instructions from the U.S., examples, and a full area-code table.
Basic steps to call Colombia from the USA
Before calling anyone in Colombia, know the sequence: international prefix + country code + local number.
1. Enter the U.S. exit code – 011
This is the international prefix from a landline. If you’re using a mobile phone, use the “+” sign instead.
2. Dial Colombia’s country code – 57
This identifies Colombia in the international telephone system.
3. Dial the local number in Colombia
For landlines include the city area code. For mobile phones, dial the full 10-digit mobile number.
Examples:
- Call Bogotá (landline): 011 + 57 + 1 #######
- Call Medellín (landline): 011 + 57 + 4 #######
Area codes and dialing examples for Colombian cities
There’s a difference between calling a landline and a mobile in Colombia from the U.S.: landlines need the regional area code; mobiles are dialed using the “+” format on cell phones.
Below you’ll find the area codes for Colombia’s main cities to ensure you dial correctly when contacting your family.
City
Area code
U.S. dialing example
Bogotá
1
011 57 1 #######
Medellín
4
011 57 4 #######
Cali
2
011 57 2 #######
Barranquilla
5
011 57 5 #######
Cartagena
5
011 57 5 #######
Bucaramanga
7
011 57 7 #######
Pereira
6
011 57 6 #######
Cúcuta
7
011 57 7 #######
Santa Marta
5
011 57 5 #######
Manizales
6
011 57 6 #######
Digital alternatives and budget-friendly plans to call Colombia
The phone is a favorite way to bridge distances and stay in touch with loved ones across borders.
Years ago, international rates were expensive, making frequent calls home difficult.
Today, digital options have lowered costs and made cross-border communication much easier.
Below we show some affordable options to help you stay in touch with the people who matter most.
- Internet-voice apps (VoIP):
Mobile apps are hugely popular worldwide. They enable texting, voice notes, and voice/video calls over Wi-Fi or data—significantly cutting costs.
WhatsApp is the most popular, and other solid options include FaceTime, Google Voice, and Skype.
- International calling plans from your U.S. carrier:
If you prefer traditional calling, look for an international plan from your U.S. provider with minutes to Colombia—great for frequent calls.
You can pick plans with minutes to landlines and mobiles or Colombia-specific bundles.
Examples of U.S. carriers include AT&T Prepaid, T-Mobile, Verizon, and Ultra Mobile. Options range from unlimited international add-ons and prepaid plans with international calling to limited-minutes bundles and mixed data/calling packages.
- Prepaid calling cards as a flexible option:
If you’re in the U.S. for only days or weeks, a mobile plan may be overkill. A prepaid calling card can be ideal—no PINs in many cases and you only pay for the minutes you use.
Stay connected with family in Colombia with Común
As you’ve seen, calling Colombia from the U.S. is straightforward—just use the correct codes. You can also choose affordable alternatives like mobile apps or prepaid cards.
Staying in touch shows care and support. It also helps to have accessible services to send money and support their well-being.
Meet Común your direct link to the ones you love!
- International money transfers: the simplest way to send remittances to family with fair, transparent pricing.
- Común’s mobile app in Spanish and English: open an account with 100+ eligible official IDs and get support in your language.
Ready to revolutionize how you connect with your finances?
Open your Común account today and complement your calls with a fintech platform that supports your financial life in the U.S.
Frequently Asked Questions (FAQ)
Still have questions? Check our FAQ section below.
What if I don’t dial 011 or “+”?
If you don’t dial 011 from a landline or “+” on mobile, your call won’t be recognized as international and will fail as a local call.
What’s the cheapest way to call Colombia from the USA?
There are several affordable options—apps like WhatsApp, Skype, or Google Voice; prepaid calling cards; or an unlimited international plan. The best choice depends on your habits and how often you call.
How much does it cost to call Colombia from the USA?
Costs vary by method. For example, AT&T offers unlimited add-ons around $15/month and Verizon offers 300 minutes for about $10/month.
Community
Común: Digital Banking for Immigrants in the U.S.
8 min de lectura
Común is a digital financial platform designed specifically for the immigrant community in the United States, letting you open an account with Latin American IDs, no Social Security Number required.
Común does not have branches, but it has a team that supports its customers 24 hours a day, 7 days a week, from the comfort of their homes, in three different languages.
Building a better future for immigrants in the U.S. is a core principle of Común’s mission. Accessible and easy-to-understand banking options are a key part of the immigrant journey. However, the options are scarce.
Complex, cumbersome, and expensive options are the norm. Activities that may seem trivial and intuitive to those born in the U.S. are overwhelming and confusing for a newly arrived immigrant. Everything from setting up direct deposit with an employer to sending money home, making payments for goods and services, or understanding how to build a credit score seems too complex for anyone who has never had to do this in the U.S., let alone at all.
Hidden fees and costly charges add another layer of stress when starting a financial life in the U.S. Between minimum account balances, monthly fees, overdraft charges, large check deposit fees, extortionate international transfer fees, and everything else, maintaining and using a bank account in the U.S. can be expensive. For manual laborers, this can represent a significant percentage of their wages.
The physical locations of traditional banks can also be scarce in some areas. Since opening a bank account or depositing a check or cash into the account must be done at a branch, this is a significant burden for someone living in a remote area. Many immigrants, sometimes working on remote farms or factories, live miles away from the nearest bank branch. Transportation costs to those branches add to the already high fees of using and maintaining an account.
Even if the banking services provided were more intuitive, digital, and lower cost, another major barrier remains. Obtaining the necessary documentation to open a bank account can also make access to fair and simple financial services difficult. Immigrants fortunate enough to have work authorization still need to gather important documentation that is not always available to them. For those who have come to the U.S. seeking asylum or better work opportunities through a more unconventional path, the documents required to open an account are often prohibitive.
Building a 100% digital banking platform to solve the issues mentioned above is part of what Común seeks to achieve because we believe in helping unlock social mobility. But a digital, low-cost, and intuitive platform is not enough. To navigate this process, immigrants need help, and help is best found in a Community that understands them when they need it most.
That is why not only our customers are part of our Community, but also the people who help them 24 hours a day, 7 days a week through our app, social media, WhatsApp, or by phone. Beyond solving an immediate problem, the support provided goes further. It teaches and educates, empathizes, and strives to foster a sense of Community among people who understand them, in terms they comprehend and in the language they speak. This is the core of true digital community banking. Our team helps them set up direct deposit, get refunds for charges they disagree with, and everything else.
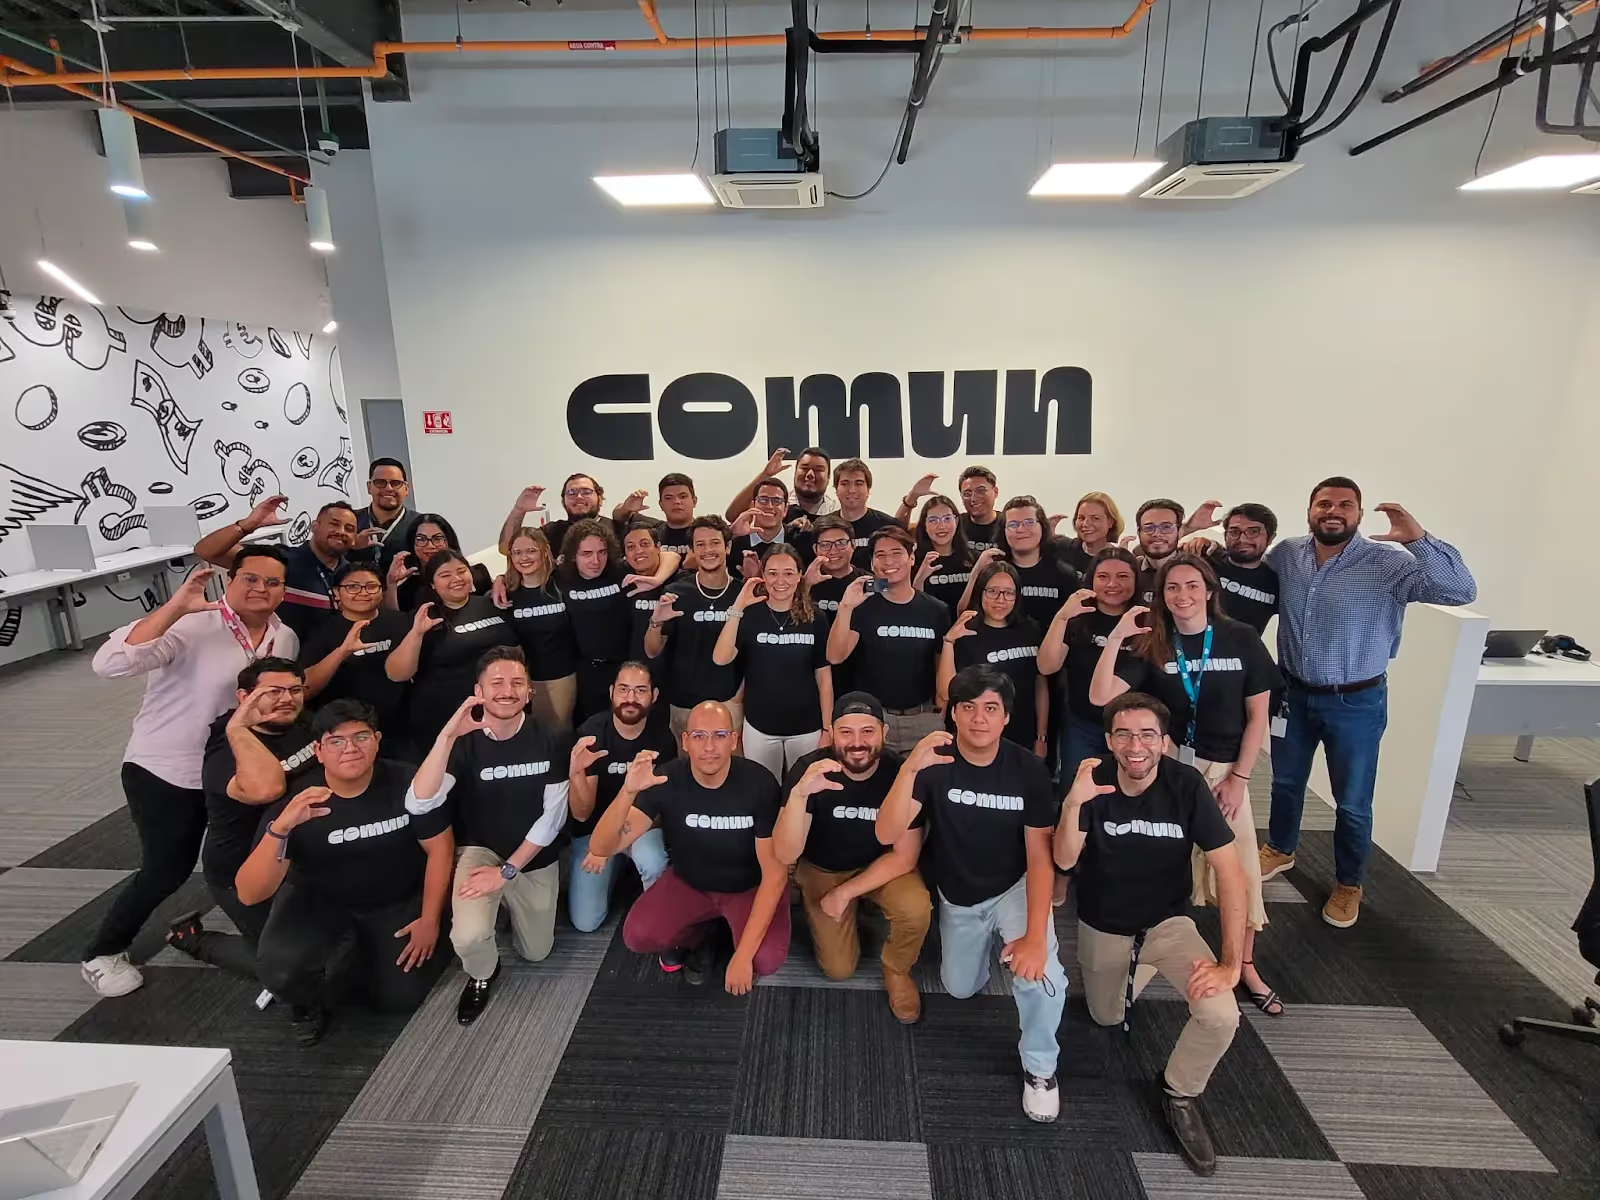
At Común, the first step in this journey has already begun. Our team in Mérida, Mexico, is part of our Community and the one we seek to serve. They are an extension of our mission and our digital platform, and a necessary ingredient in unlocking social mobility for millions of immigrants in the U.S.
What makes Común different from a traditional bank?
Común accepts over 100 Latin American IDs (passport, consular ID, among others), doesn't require an SSN or ITIN, and doesn't charge a monthly fee or require a minimum balance.
How does Común specifically support the immigrant community?
With 100% Spanish-language support, an account opening process that takes minutes, and features built for common community needs, like low-cost remittances and cash deposit without needing a prior bank account.
What services does Común offer?
A checking account with a Visa debit card, international remittances starting at $2.99, cash deposit at over 88,000 locations, and direct deposit.
Frequently asked questions
Who is Común designed for?
For the Latin American immigrant community in the U.S. looking for accessible financial services without traditional documentation barriers.
What IDs does Común accept?
Over 100 Latin American IDs, including passports and consular IDs — no SSN or ITIN required.
Does Común charge an opening or maintenance fee?
No, there's no opening fee, monthly fee, or minimum balance required.
Is Común's support available in Spanish?
Yes, the app and customer support are available in Spanish.
How fast can I open my account?
The process takes about 3 minutes, with instant approval in most cases.
Does Común offer remittances to Latin America?
Yes, starting at $2.99 per transfer, with your first transfer at no cost.
Financial Education
How to save money in the USA? Real strategies for immigrants starting from scratch
8 min de lectura
Living in the U.S., without a doubt, represents a major advantage for improving quality of life, due to the job opportunities this country offers both citizens and foreigners. However, adjusting to the pace of life in the United States also means facing various expenses that can affect personal finances, especially for newly arrived immigrants.
Savings strategies are an indispensable ally for reducing financial uncertainty, being prepared for any unforeseen event, and building a full future in a new country.
If you identify with this situation and are navigating difficulties covering monthly expenses, below we show different ways to save money in the USA tailored specifically to the reality of immigrants, as well as alternatives for savings accounts, so you can have full control of your capital.
10 ways to save money in the USA
Saving in the United States means developing a set of habits aimed at optimizing resources and choosing financial services with competitive interest rates.
Setting savings goals is the first step toward starting a healthy, worry-free financial life.
Below, we share some strategies to get the most out of your daily spending.
1. Plan and budget your expenses
Before making any move, it’s essential that you’re clear on the amount of your monthly income and outgoings, so you should start by keeping clear financial records.
To do this, you can use a personal finance and budgeting application or a spreadsheet, in order to record categories such as:
- Fixed expenses: all expenses you repeat every month such as rent, utilities, transportation, remittances, etc.
- Variable expenses: expenses whose amount varies, such as food, entertainment, loans, etc. Based on your income, assign a budget to each.
- Savings: it’s very important to make sure you keep a sufficient amount of money after covering your monthly expenses. It will help you build an emergency fund you can use for the unexpected. Set short-term financial goals so you can monitor your progress.
2. Take advantage of deals and coupons
An effective way to take advantage of deals at different department stores is to use an application that helps you compare prices; that way, you can choose an alternative without leaving home.
You can also take advantage of the loyalty programs several stores offer through their mobile applications, such as Safeway and Target.
3. Reduce housing costs
Depending on the city, rent can be one of the highest expenses in your budget. If you find that after covering this item your wallet is too tight, you can consider applying some strategies.
- Consider sharing an apartment with roommates.
- Look for an area with accessible rental prices, such as Texas.
- By contrast, New York is among the most expensive places to live, so it’s advisable to look for more accessible options.
- Check your eligibility to access the public housing program with the Housing Authority.
4. Cook at home instead of eating out
Eating at restaurants is always tempting, but it can generate up to 5 times more expenses than preparing food at home. Plan weekly menus and avoid wasting food.
5. Use low-fee remittance services to send money to your country of origin
For immigrants in the United States, sending money home is a basic need, since it is one of the main means of support for their loved ones.
Before sending money to Latin America, make sure to compare different services in terms of transfer fees, exchange rate, delivery methods, and time.
Comun lets you send your first remittance at no cost (Promotion subject to change. Check availability in the mobile app) and offers accessible fees for the following ones. It is a popular option among immigrants for its accessibility and bilingual Spanish-language support, because it shares language, interests, and common goals: bringing families closer through safe and accessible financial solutions.
6. Use public transportation or share rides
Public transportation is a great way to get around a city at low cost. You can choose the bus service, ride-sharing applications, or, for short distances, a bicycle.
7. Look for assistance programs or local benefits available to immigrants
Check the availability of assistance programs in your city, such as medical care at community health clinics and food banks.
For example, the Supplemental Nutrition Assistance Program (SNAP) provides financial assistance for the purchase of nutritious food. Eligibility for this benefit depends on immigration status, as it requires citizenship or legal residency in the country.
8. Learn about credit and finances as an immigrant
Understanding the U.S. financial system is key to accessing basic services such as a bank account, debit card, credit card, etc. For this, you generally must have an SNN or ITIN. Therefore, it’s advisable to look for accessible options so you can integrate as soon as possible.
In addition, the U.S. government offers a retirement savings plan through the Individual Retirement Account (IRA), which allows you to accumulate money tax-free until it is withdrawn.
9. Buy second-hand to save from the start
Another way to save money is to buy household items at second-hand stores such as Craigslist, OfferUp, and Goodwill. In this way, you can save up to 50% of the budget allocated to these purchases.
10. Take advantage of government benefits
Another support program is Housing Vouchers, which help low-income families with rent payments. On the other hand, the Earned Income Tax Credit (EITC) is available to workers with low to moderate incomes.
What earns the most money in the United States?
If you’re wondering how to make more money in the USA, you should consider working in some of the country’s sectors if your profile fits any of them.
These are some of the highest-paying jobs in the United States, which will not only allow you to meet your savings goals but also significantly improve your quality of life.
Medicine
Professions related to the health sector in the United States are among the highest salary. Average earnings can reach up to $450,000 USD per year, depending on the specialty.
Public Services
This sector also reaches very good earnings, which average can reach up to $133,800 USD per year. This sector includes jobs related to electricity and the generation of renewable energy.
Information Technology (IT)
This is one of the highest-paying industries worldwide. In the United States, average annual salaries reach approximately $99,500 USD. It encompasses skills related to software development, artificial intelligence, and cybersecurity.
Finance
The average earnings of jobs related to the financial sector exceed $90,000 USD. In this case, you can specialize in professions such as portfolio management and investment banking or financial advisor.
Law
Finally, the legal sector is also very well paid, with average earnings of approximately $176,000 USD per year.
Open your account at Comun easily, quickly, and safely
Saving in the United States doesn’t mean giving up your quality of life, but rather adopting smarter money-management habits and developing a solid financial education.
You can start with simple savings strategies, such as taking advantage of digital discounts, reducing housing expenses, avoiding impulse purchases, and choosing more economical remittance platforms.
The key to strengthening your finances lies in organizing resources with a long-term vision and applying these strategies consistently to move toward your goals.
Meet Comun! The financial platform that addresses day-to-day needs in the United States, through an easy-to-use mobile app, where you can open an account in a matter of minutes with a qualified official ID from your country of origin. Send money to your loved ones without complications, so your family gets more for less. See terms and conditions. Exchange rates and fees may vary by country, amount, and delivery method.
Comun is a digital platform designed to help the immigrant community in the U.S., available in Spanish and English.
Frequently Asked Questions
If you still have questions, check our Frequently Asked Questions section.
Which account fits your needs in the United States?
Comun is a popular alternative among immigrants who seek accessible, quality services. Open your account today and discover all the benefits.
What is the 50-30-20 rule?
It’s a savings method that helps you divide your income to reach your financial goals: 50% for necessities, 30% for discretionary expenses, and 20% for your savings fund.
How can you make money quickly in the United States?
Look for flexible jobs on applications or sell things you no longer use on second-hand sites.
Community
How Common Makes Money: A Transparent Look at Our Business
8 min de lectura
Like most financial apps that don't charge a monthly fee, Común generates revenue mainly through interchange fees (a small fee paid by the merchant, not you, every time you use your debit card) and international remittance fees.
Founded by Mexican co-founders who themselves navigated the banking system as immigrants in the United States, Común brings a unique perspective to the challenges faced by its target audience.
Let’s look at how Común remains profitable through innovative revenue streams, cost-saving strategies, and a deep commitment to its customers, emphasizing how these factors contribute to the ease and benefits of virtual banking for newcomers to the financial world.
Revenue Streams: Banking Services
Común not only offers essential banking services¹, but also features such as international remittances⁴, which provide significant benefits for Común customers. Común monitors cash flows and payment channels to ensure efficient and secure transactions. Consumers often pay high remittance fees with other services, but Común offers a cost-effective alternative.
This service is crucial for immigrants who regularly send money home, increasing Común’s appeal as a banking solution that understands and responds to the specific financial dynamics of its users.
Cost-Saving Strategies: Financial Inclusion
The strategic absence of physical branches allows Común to minimize operating costs and maximize profits. Común allocates resources to expand its reach and improve financial services for Latina immigrant families. These savings are passed on to customers through lower fees and better rates, making financial services more accessible. Común’s digital platform makes banking easier to access, offering 24/7 services that make money management secure and efficient from any browser or app.
Company Values and Customer Relationship
Común champions financial inclusion, particularly within the Latino community, positioning itself among companies dedicated to serving Latino communities and enabling account setup with a variety of international IDs. This inclusivity strengthens trust and understanding between Común and its customers, fostering a supportive banking environment.
Competitive Advantage
By creating a customer-focused digital bank that offers services in Spanish and accepts nontraditional IDs, Común specifically addresses the barriers faced by Latino immigrants. This personalized service not only sets Común apart from its competitors, but also deepens customer loyalty and trust.
Target Audience
Común focuses on Latino immigrants, a group often overlooked by traditional banks. In its latest funding round, Común raised $5 million in June 2022 to further develop its services. By offering accessible and empathetic financial services, Común not only meets a significant market need, but also empowers its customers toward greater financial stability and integration into the U.S. economy. South Park Commons, along with Costanoa Ventures, has played a key role in supporting financial inclusion banking solutions for Latina immigrant families in the United States.
Conclusion
Virtual banks like Común present an easy-to-use, cost-effective, and inclusive alternative to traditional banking, particularly beneficial for those who are new to banking or marginalized by conventional financial institutions. By focusing on accessibility, cost efficiency, and customer-oriented services, Común not only maintains profitability, but also significantly improves the banking experience for its users.
If Común doesn't charge a monthly fee, how does it make money?
Mainly through interchange fees — a small fee the merchant pays (not the user) every time the debit card is used — and international remittance fees, which start at $2.99 per transfer.
Does this mean using Común is "free"?
Using your checking account (no monthly fee, no minimum balance) is at no cost to you. International remittances do have a fee, shown transparently before you confirm each transfer.
Why does it matter to understand how your financial provider makes money?
Understanding the business model helps confirm incentives are aligned — a provider that earns from interchange fees benefits from you using your card, not from charging you hidden fees.
Frequently asked questions
Does Común charge any hidden fees if there's no monthly fee?
No, using the checking account is at no cost; the only visible fee is for international remittances, shown before you confirm.
What's an interchange fee?
It's a small fee the merchant pays to the payment network (Visa) every time a customer uses their debit card — the user doesn't pay it.
Does Común make money from my remittances?
Yes, remittance fees (starting at $2.99) are one revenue source, shown transparently before each transfer.
Why do some banks charge a monthly fee and Común doesn't?
It depends on each institution's business model; Común relies more on interchange and remittance fees than account fees.
Does this affect the safety of my money?
No, your money is FDIC-protected up to $250,000 through Community Federal Savings Bank, regardless of Común's revenue model.
Where can I see exact fees before using them?
The app shows applicable fees (like remittance fees) before you confirm any transaction.
Living in the United States
Direct deposit vs wire transfer: comparison guide for U.S. immigrants
8 min de lectura
Direct deposit vs wire transfer: comparison guide for U.S. immigrants
These payment methods are both available in the U.S. but they are often used for different purposes. Direct deposit is commonly used for paychecks, tax refunds, and government benefits, while wire transfers are more often used for urgent or high-value transfers between financial institutions.
Understanding the difference between direct deposit and wire transfers can help you avoid unnecessary fees, choose the right payment method for your situation, and manage your money more confidently.
What's the difference between direct deposit and wire transfer?
The biggest difference is the purpose they serve. Direct deposit is commonly used for recurring payments such as salaries, benefits, and tax refunds. Wire transfers are commonly used to move money quickly between financial institutions, particularly for large or time-sensitive transactions.
| Feature | Direct deposit | Wire transfer |
|---|---|---|
| Common use | Paychecks, benefits, tax refunds | Large or urgent transfers |
| Network used | ACH network | Wire transfer network |
| Speed | Typically 1–3 business days | Often same day or next business day |
| Typical cost | Often no fee to receive | Fees may apply |
| International transfers | Limited | Commonly used |
| Recurring payments | Yes | Less common |
| Setup required | Routing + account number | Bank details + recipient information |
How direct deposit works
Direct deposit is one of the most common payment methods in the United States, particularly for employees receiving wages from an employer. Instead of issuing a paper check, an employer sends the payment electronically to the employee's bank account through the ACH network.
To set up direct deposit you need to provide your employer: your bank's routing number and your personal account number.
How wire transfer works
A wire transfer is an electronic transfer of funds between financial institutions through secure financial networks like Fedwire or SWIFT. Unlike direct deposit, wire transfers are better suited for large one-time payments, urgent payments, real estate transactions, or international transfers.
When to use each one
Use direct deposit for:
- Receiving your paycheck
- IRS tax refunds
- Social security or unemployment benefits
- Recurring business payments
Use wire transfer for:
- Real estate payments (down payment, closing)
- Urgent international transfers
- High-value business payments
- When the recipient specifically requires a wire transfer
How to set up direct deposit with Común
With your Común account, you can set up direct deposit by providing your Común routing number and account number to your employer. Your Común account has unique routing and account numbers available in the app. Visit comun.app to learn more.
FAQ
Is direct deposit faster than wire transfer?
Not necessarily. Domestic wire transfers can be faster (same day), while direct deposits usually take 1-3 business days. However, many accounts offer early access to direct deposits up to 2 days early.
How much does it cost to set up direct deposit?
Setting up direct deposit is generally no fee. Employers use the ACH network to send payroll electronically at no charge to the employee.
Común is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank, Member FDIC.
Financial Education
What is the CVV and what is it used for on your card?
8 min de lectura
What is the CVV on a card?
Nowadays, making purchases with a credit or debit card in physical stores and online is an essential activity for acquiring everyday goods.
Security in these operations is essential. For this, these payment methods use the CVV or CVC code, which means Card Verification Value or Card Verification Code respectively, and its purpose is to verify that the cardholder has the physical card and to protect online and phone purchases.
Below, we will explain in detail what the CVV is, where to find it, the types of security codes, and tips to keep your cards secure.
Where to find the CVV on your card?
If you are going to make purchases online or by phone, you will need to provide the security code of your debit or credit card to verify it belongs to you.
In most cases, the CVV is located on the back of the card and consists of 3 or 4 numbers.
Here is a quick guide to locating the verification code depending on the card type.
Card type
Where to find the CVV?
How many digits does it have?
Visa
Usually on the back, next to the magnetic stripe.
3
Mastercard
Usually on the back, next to the signature.
3
Discover
Usually on the back, to the right of the signature.
3
American Express
Usually on the front, next to the card number.
4
One way to strengthen security during electronic transactions is the use of a dynamic CVV, which is found in digital applications or cards and is valid only for a limited time to make a single purchase. This reduces the risk of misuse of your personal data if it is exposed.
What is the CVV for and why is it important?
The CVV number is a security lock that allows you to use your physical and digital cards with confidence that a third party cannot access your money.
These are the most important functions of this security code.
- Holder verification:
It is especially useful for protecting electronic operations by verifying that the cardholder is the one making the purchase.
- Security in online purchases
When making an online purchase, you must enter the card’s CVV to validate the transaction. This process is more secure when using a dynamic CVV because it reduces the risk in case of fraud.
- Fraud prevention
Unlike other data usually included on physical cards, such as the number and expiration date, the CVV is not stored in online store systems, so your data remains safe in case of potential identity theft.
The purpose of the CVV is to provide you with security and peace of mind when making online purchases.
CVV, CVC, and CVV2: how are they different?
You may notice different types of CVV since the name can vary depending on the card issuer.
These are the security codes most commonly used by financial institutions to protect users’ cards.
CVV
The CVV (Card Verification Value) is the security code created for Visa cards. It consists of 3 or 4 digits and is used to confirm that the person making the purchase actually has the card.
CVC
The CVC (Card Verification Code) is the version of the CVV used by Mastercard cards. It has the same function and a similar composition.
CVV2
The CVV2 (Card Verification Value 2) is a digital version of the CVV used to provide greater protection in online purchases. While the traditional CVV is used during payments at card terminals, the CVV2 is requested to confirm remote transactions.
4 tips to use your card safely
Some people avoid or minimize the use of physical or digital cards due to fear of having their personal data stolen and generating unauthorized charges. However, financial institutions and digital platforms currently offer the necessary security measures to protect your assets.
Thanks to the implementation of codes such as the CVV, the risk of experiencing a security incident is minimal and decreases even more when you have the right information to apply practical strategies like the following.
- Do not share your CVV or write it in visible places: avoid having this code leaked to third parties. Remember that it is the number used to verify online purchases and that no financial institution requests sensitive data over the phone, so make sure to use the CVV responsibly.
- Use only secure payment sites (https://): if you need to make an online purchase, make sure the site has the required security measures to process electronic payments.
- Activate notifications or dynamic CVV if your bank offers it: enable notifications in your banking application and try using the dynamic CVV when shopping online. This allows you to generate a new CVV for each purchase.
- Review your transactions regularly: check your statement and transaction history frequently. If you detect any irregular activity, report it to your bank immediately.
Bank cards are useful tools that require responsible and cautious use. Learning to use your card safely and confidently is also part of building financial stability.
Manage your money and make payments securely with Comun
This time we explained what the CVV or CVC is, why it is important, and gave you some tips to keep your checking accounts secure.
The security provided by the CVV is the same you need in all your financial operations, such as digital payments, cash deposits, and international money transfers. For this, you have Comun, the digital platform specially designed for immigrants living in the United States who want to manage their money safely and without complications, with clear and competitive fees.
Comun is the financial platform that truly understands your needs and offers fair, tailored solutions.
Open your Comun account and start managing your money in the United States with confidence. Send, receive, and monitor your expenses from the mobile app.
Frequently Asked Questions (FAQ)
If you still have questions, check the following section.
What happens if I give my CVV to someone else?
It is not advisable to give your CVV to someone else, as they could make purchases not authorized by you. Make sure to protect your banking information so only you have access to it.
Is the CVV the same as the card number?
No, the card number consists of 16 digits and identifies the checking account. The CVV consists of 3 or 4 digits and verifies that the holder is the card owner.
Can I make purchases without a CVV?
In physical stores, it is not strictly necessary, as the purchase is validated with the chip and PIN. For online purchases, it is essential to enter the CVV to authorize the transaction.







Thousands of immigrants are already achieving more with their money. You can too.
Comun is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank; Member FDIC. The Comun Visa® Debit Card is issued by Community Federal Savings Bank, pursuant to a license from Visa U.S.A Inc. and may be used everywhere Visa Cards are accepted.
Comun is a fintech company and not a bank or licensed money transmitter.
* Results may vary. For a complete list of eligible IDs and application requirements, follow this link.
^ No minimums, no maintenance fees. ATM or transfer fees may apply. See app for fee details.
‡ Direct deposit funds are typically available when we receive the payment file, up to two days before the scheduled payment date. This early availability is not guaranteed.
** A service provided by Service UniTeller, Inc. Service UniTeller, Inc. is licensed in all states that require a license. Remittance fees start at $2.99 but may vary. Please check the app for more details. Comun Inc. may earn revenue from the conversion of foreign currencies.
† Funds in your account are FDIC insured up to $250,000 by ownership category through Community Federal Savings Bank (CFSB), Member FDIC, in the event CFSB fails.


