
Living in the United States
Cashier’s Checks in the U.S.: Costs, Impact on Latinos, and Free Alternatives
In the United States, a common way to receive payments is through checks. However, cashing a check can be costly.
8 min read

25 Apr 2023
Why is it so expensive to cash checks in the United States?
Without a bank account, people must turn to check-cashing stores that charge between 1% and 3% of the check amount. For a $1,000 check, that means $10-30 lost on each cash-out. Banks may also charge fees for depositing checks from other banks.
Why do Latinos disproportionately bear these costs?
Latino communities have less access to banking services because of barriers such as SSN requirements, language, and unfamiliarity with the system. Without a bank account, they are more likely to use check-cashing stores located in low-income areas that charge high fees.
Solutions for cashing checks at no cost
The best solution is to open a bank account. Común is a Spanish-language digital bank that allows you to open an account without an SSN using a passport or consular ID card. Once opened, you can deposit checks for free from the app using mobile deposit. There are also nonprofit organizations such as UnidosUS that offer free financial services to Latino communities.
Frequently asked questions about cashing checks in the U.S.
How much does it cost to cash a check in the U.S. without a bank account?
Check cashing stores typically charge between 1% and 3% of the check amount, with a minimum of $3-5. For a $1,000 payroll check, that means losing between $10 and $30 on each cash-out. Walmart Money Center charges lower fees ($4 for checks up to $1,000), but the cost is still higher than having a bank account.
Can I cash a check for free in the U.S.?
Yes, with a bank account. If you deposit the check at your own bank, there is no charge. With Común you can deposit checks by photographing them from the app, completely free. Some banks also allow you to deposit checks from other banks at no additional cost using mobile deposit.
Why do Latino immigrants pay more to cash checks?
The main reason is less access to bank accounts. Barriers include SSN requirements, language, unfamiliarity with the system, and fear of formal procedures. Without a bank account, they turn to check-cashing services that charge high fees. Platforms like Común remove these barriers by accepting Latin American IDs without an SSN.
What do I need to deposit a check in Común?
You only need the Común app and the physical check. Open the app, select “Deposit check,” take a photo of the front and back of the check (with your signature on the back), and the money is generally credited in 1-2 business days. There are no additional charges for the mobile deposit service.
What happens if someone pays me with a personal check from someone without a bank account?
Personal checks from people without sufficient funds or without an active account bounce (bounced check). If you deposit that check, the bank may temporarily hold the funds and then debit you the amount plus an NSF fee ($25-35). To receive payments more safely, prefer Zelle, Venmo, or direct transfers instead of personal checks from people you do not know well.
Is it better to receive payroll by check or by direct deposit?
Direct deposit is better in virtually all cases: the money arrives automatically on payday (or earlier with Común), there is no risk of the check being lost or stolen, there are no cashing fees, and you can access the funds immediately. With Común you can set up direct deposit from the app in minutes using your routing number and account number.
About Común
Común aims to support the Latino community in the United States. It offers a debit account that can be opened with more than 100 valid Latin American IDs and an app available in Spanish.
Visit Común's website or download the app for free to learn more about the full offer and applicable terms.
Olivia Rhye
Community Partner


Immigration
Benefits of Having an ITIN in the U.S. for Non-Citizens
8 min de lectura
How to get an ITIN
The ITIN is obtained through IRS Form W-7 along with identity and foreign status documentation. A passport is the only document that satisfies both requirements on its own. The process takes between 7 and 11 weeks.
1. It allows federal tax filing
The ITIN allows you to file tax returns with the IRS, including claiming credits such as the Child Tax Credit and the Earned Income Tax Credit.
2. Access to credit and financial services
Some banks and credit unions accept an ITIN as an alternative ID to an SSN for opening accounts. Platforms like Común do not require either an SSN or an ITIN.
3. It facilitates business operations
For entrepreneurs, the ITIN is vital for filing business taxes and applying for an Employer Identification Number (EIN).
4. It supports residence and immigration processes
Consistently filing taxes with an ITIN can demonstrate good moral character, a factor considered in some immigration cases.
5. It helps establish identity and secure income
In the absence of an SSN, the ITIN is recognized by financial institutions and government agencies as a valid identification number.
6. Access to state services and benefits
In some states, the ITIN allows access to a driver’s license, health insurance, or in-state college tuition rates.
7. It protects against tax identity theft
Using the ITIN consistently links your tax data to your identification number, reducing the risk that someone files a return in your name.
Frequently asked questions about ITIN benefits
What is the ITIN used for in daily life?
The ITIN allows you to file tax returns with the IRS, claim tax credits such as the Child Tax Credit, open bank accounts at institutions that accept it, and in some states access services such as driver’s licenses or in-state tuition. It is the tax identification number for those who do not qualify for an SSN.
Does the ITIN give me the same rights as an SSN?
No. The ITIN is exclusively for tax purposes. It does not authorize you to work legally in the U.S., does not generate Social Security credits, does not provide automatic access to federal benefits such as Medicare or unemployment, and is not equivalent to an SSN for most government procedures. It is a tool for tax inclusion, not immigration status.
Does filing taxes with an ITIN affect me in an immigration process?
In general, filing taxes with an ITIN can be beneficial in immigration processes because it demonstrates a history of tax compliance and “good moral character,” one of the criteria evaluated in some adjustment-of-status cases. However, the impact varies by case — consult an immigration attorney before using it as an immigration strategy.
Can I open a bank account with an ITIN?
Some banks do accept an ITIN. Bank of America and certain local banks have specific programs for ITIN holders. However, many large banks require an SSN. Alternatives like Común do not require either an SSN or an ITIN — they accept a passport, consular ID, or other Latin American IDs for immediate account opening.
Does the ITIN help me access credit in the U.S.?
Yes, partially. Some credit card issuers and lenders accept an ITIN. Certain mortgage programs (ITIN loans) allow you to buy a home without an SSN. Building credit history with an ITIN is possible, although more limited than with an SSN. Credit built with an ITIN generally does not automatically transfer if you later obtain an SSN.
How do I apply for an ITIN if I have never had one?
You submit IRS Form W-7 along with identity and foreign-status documentation — a passport is the only document that satisfies both requirements on its own. You can mail it with your tax return, go in person to an IRS Taxpayer Assistance Center, or apply through an authorized Certifying Acceptance Agent (CAA), which is the fastest and safest method.

International Money Transfers
Money Transfers: From Traditional Methods to Digital Innovations
8 min de lectura
Money transfers have evolved from traditional methods like checks and money orders to instant digital solutions. With Común, most international remittances arrive within minutes, with no need to visit a branch.
The financial evolution of money transfer methods from traditional practices to digital innovations marks a crucial shift, revolutionizing how we think about and manage our finances in our bank accounts and beyond. This transition isn't just about technological advancement — it reflects a fundamental shift in user expectations, security standards, and global connectivity, especially in international money transfers and seamless bank account integration.
Accelerating Transactions: The Digital Revolution in Money Transfers
The rise of digital platforms and money transfer apps has transformed the speed and accessibility of transactions. Where bank transfers between financial institutions once took days to complete, digital innovations now enable instant money transfers, letting users transfer money around the world in just a few business days or even instantly. This monumental shift in convenience lets users send money or transfer funds from one bank account to another 24/7, without the traditional visit to a bank or credit union.
These changes encapsulate the journey from traditional methods like bank transfers and bank-to-bank transfers to the digital innovations now dominating our financial ecosystem. As we continue exploring these developments, it's clear that ways of transferring money — from using a debit card for instant transfers to leveraging payment app capabilities like Google Pay and Apple Pay — aren't just evolving, they're being redefined for a new era of global connectivity and digital empowerment, making money transfer apps an indispensable tool in our daily lives.
Navigating International Money Transfers: Considerations
Additionally, the rise of mobile apps, from money transfer services like Cash App to full banking apps, has democratized access to financial services. These platforms offer user-friendly interfaces that simplify the money transfer process, whether sending money abroad through international transfers or managing domestic transfers between checking and savings accounts within the same bank. This broadens financial inclusion, letting even those with a basic savings account or checking account participate easily in bank transfers and person-to-person payments.
It's equally important to have a solid understanding of the regulatory framework surrounding international money transfers. This includes being aware of anti-money laundering (AML) laws and the various transfer limits imposed by different countries. These regulations are designed to prevent financial crimes and ensure the security of cross-border transactions. Following these laws not only helps avoid legal complications, but also ensures your transactions process without unnecessary delays.
In addition to choosing the right service and understanding regulations, it's also helpful to be aware of the exchange rates offered by different services. Exchange rates can significantly affect the final amount received on the other end, especially for large transactions. It's also crucial to consider delivery times, especially if the transfer is time-sensitive. While some services can transfer funds almost instantly, others may take several business days. This can be particularly important in emergency situations or when making payments with strict deadlines.
Exploring Different Money Transfer Options: Wire, ACH, and Beyond
Digital advances have also introduced a new level of security and transparency to money transfers. With modern encryption and authentication technologies, including features like fraud detection, financial transactions — whether internal transfers, external transfers, or even online payments for online purchases — are safer than ever.
Money transfer apps have become a safe haven for personal finances, offering real-time transaction tracking and ensuring that transferring money — from a linked bank account via Automated Clearing House (ACH) transfers or direct deposit — stays secure and straightforward. ACH transfers stand out for domestic efficiency and cost-effectiveness, ideal for regular payments like salaries and bills. Additionally, traditional methods like checks, cash deposits, and money orders retain their usefulness for specific scenarios, offering tangible options in a predominantly digital world.
The Rise of Person-to-Person (P2P) Money Transfer Apps
P2P transfer apps have fundamentally transformed how we exchange money, making transactions as simple as sending a message. These apps let users send funds directly to others, using just an email address or phone number, eliminating the need for intermediaries. Among the many options available, several apps have gained prominence, each standing out for its distinctive features.
For example, some apps are celebrated for their integration with social networks, enhancing the social aspect of money transfers. Others prioritize security, offering advanced encryption and authentication methods to protect transactions. There are also apps designed to facilitate cross-border payments by simplifying the process of sending money internationally, offering competitive exchange rates and low fees. This diversity ensures there's a P2P transfer app suited to practically every need and preference, reflecting the dynamic, user-centered evolution of financial technology.
Decoding the Costs: Fees in Money Transfers
The rise of mobile apps, from money transfer services like Cash App to full banking apps, has democratized access to financial services. These platforms offer user-friendly interfaces that simplify the money transfer process, whether sending money abroad through international transfers or managing domestic transfers between checking and savings accounts within the same bank. This broadens financial inclusion, letting even those with a basic savings account or checking account participate easily in bank transfers and person-to-person payments.
Understanding the fees associated with money transfers is pivotal for managing your finances effectively and avoiding unexpected costs. The fee landscape for transfers can vary significantly, spanning service charges, transaction fees, and currency conversion fees, among others. Transparency around these fees is crucial — so it's essential to choose services that offer clear, straightforward information about all the costs involved.
Service charges and transaction fees are often the most visible costs associated with transferring money. These can vary widely depending on the provider and transfer method chosen. For example, traditional bank transfers might carry higher fees compared to online platforms or mobile apps. Currency conversion fees also play a significant role, especially for international transfers, where money needs to be exchanged from one currency to another. Some services build their profit into the exchange rate offered, making it less favorable than the market rate. This practice underscores the importance of scrutinizing the exchange rates provided, not just the explicit fees.
This approach not only helps you make informed decisions, but also helps avoid hidden charges that can add up. To minimize these costs, adopting strategies like selecting the transfer method best suited to your needs — considering factors like speed, destination, and amount — and diligently comparing providers to find the best rates and lowest fees can lead to significant savings. By prioritizing transparency and using cost-minimizing strategies, users can navigate the complexities of money transfers more confidently and economically.
Send abroad with peace of mind with your Común account¹
Open your account in 3 minutes!
Conclusion
In conclusion, the shift from traditional methods to digital innovations in money transfers represents a significant advancement in financial management. Digital platforms and money transfer apps have revolutionized how we send money, providing unprecedented convenience, speed, and security. From seamless bank account transfers to the global reach of international money transfers, these digital solutions offer a full range of services that meet our diverse financial needs.
By emphasizing transparency, these platforms minimize hidden fees, making it easier than ever to manage our savings and checking accounts. Additionally, innovations like instant transfers and robust fraud detection technology have made money transfer apps a reliable option for consumers. As we continue embracing these digital advances, the essence of mastering money transfers lies in leveraging technology to enhance our personal finance capabilities, ensuring we can navigate the complexities of modern financial transactions with confidence and cost-effectively.
How have money transfers changed over time?
From checks, money orders, and bank transfers that took days, to mobile apps that process payments and remittances in minutes.
What advantages do digital transfers have over traditional methods?
Greater speed, real-time tracking, and the ability to send money without leaving home. With Común, you can send a remittance from the app anytime.
Are traditional methods still useful?
Yes, checks and cash are still relevant in certain cases, such as when the recipient doesn't have a digital bank account.
Frequently asked questions
Why are digital transfers faster than traditional ones?
Because they use real-time processing networks, instead of the multi-day cycles of traditional banking methods.
Do I need to visit a branch to send money with Común?
No, the entire process happens through the app, with no need to visit any physical location.
Are traditional methods like checks still valid?
Yes, they're still useful in certain cases, though digital apps tend to be faster and more convenient.
How fast does a remittance sent through Común arrive?
Most arrive within minutes, depending on the country and delivery method.
Can I track my transfer in real time?
Yes, the app shows you your transfer's status while it's being processed.
Is sending money digitally safer than by check?
Both methods have different protections; digital apps usually offer additional verification and encryption.
Financial Education
What is cashback and how does it work? A 2026 Guide
8 min de lectura
What is cashback and how does it work? A 2026 Guide
Cashback is a rewards system that gives you back a percentage of the money you spend on eligible purchases. In simple terms, when you buy something using certain credit cards, debit cards, apps, or rewards programs, you may get a percentage of your money back on purchases, though it is usually credited to your account rather than handed over as physical cash.
If you recently moved to the United States or are learning how the financial system works, you may have heard the term 'cashback' while shopping at places like Walmart, Target, gas stations, supermarkets, or online stores.
For many people, cashback can become a practical tool to manage everyday expenses such as groceries, transportation, gas, and household purchases. While the amounts may seem small at first, they can add up over time when used consistently and responsibly.
What is cashback?
Cashback is a type of financial reward that returns a percentage of your purchase after you spend money with a participating payment method or rewards platform.
For example:
- If you spend $100 at the supermarket using a card that offers 2% cashback, you may receive $2 back
- If a cashback app offers 5% cashback at a participating gas station and you spend $60 on fuel, you may receive $3 back
Unlike traditional discounts, cashback usually happens after the purchase is completed. The Consumer Financial Protection Bureau (CFPB) explains that cashback rewards are commonly offered through credit cards and loyalty programs as an incentive for spending.
How does cashback work?
Cashback programs generally follow a simple process:
- You make an eligible cashback purchase using the participating card, app, or rewards account
- The transaction is recorded by the provider
- A percentage of that purchase is returned to you as cashback
The reward may appear as:
- Statement credit
- Bank deposit
- Gift card
- Rewards balance
- Redeemable points
- Store credit
Some cashback rewards appear within a few days, while others may take an entire billing cycle or longer to process. There are often minimum redemption thresholds before you can claim your cashback. Certain programs may include expiration dates. It is also important to understand that not every purchase qualifies for cashback.
Cashback vs. traditional discounts
While cashback and traditional discounts can both help consumers save money, they work in different ways. A traditional discount lowers the price immediately at checkout, while cashback returns part of the money after the purchase has already been completed.
| Cashback | Traditional Discount |
|---|---|
| Money is returned after the purchase | Price is reduced before purchase |
| Usually linked to cards, apps, or loyalty programs | Usually available directly in-store |
| Rewards may take days or weeks to process | Savings are immediate |
| May help track expenses digitally | Does not usually include tracking tools |
| Often limited to eligible categories or stores | Depends on store promotions |
Types of cashback in 2026
Not all cashback programs work the same way. Before signing up for a cashback program, it is important to review details such as annual fees, interest rates, minimum redemption, expiration policies, and spending categories.
Fixed-rate cashback
This type gives the same cashback percentage on all purchases. Example: 1.5% cashback on everything you buy. This structure is simple because you do not need to track categories or rotating offers.
Category-based cashback
Some cards or apps offer higher cashback percentages in specific categories such as supermarkets, restaurants, gas stations, or streaming subscriptions. For example: 3% on groceries, 2% on gas, 1% on all other purchases.
Rotating cashback categories
Some providers change cashback categories every few months. One quarter may focus on gas stations and grocery stores; another may include online shopping and travel purchases. These programs sometimes require manual activation each quarter.
Welcome bonuses
Certain credit cards offer introductory cashback bonuses if you spend a minimum amount during the first months after opening the account. For example: spend $500 in the first 3 months and receive $150 cashback bonus. The Federal Trade Commission recommends reviewing terms carefully before applying for financial products with promotional offers.
Where can you get cashback in the United States?
Credit cards:
Many credit cards in the U.S. include cashback rewards. Some examples include products from Discover, Chase, Capital One, and American Express. Some cards focus on categories like dining or travel, while others offer flat-rate cashback.
Debit cards:
Some financial institutions offer cashback debit cards, although rewards are usually smaller than those offered by credit cards. This may appeal to people who prefer avoiding debt or credit card interest.
Cashback apps:
Several mobile apps partner with retailers and offer cashback rewards for purchases. Examples include Rakuten, Ibotta, Upside, and Honey. These apps may provide cashback for grocery shopping, online purchases, gas stations, and restaurants.
Store loyalty programs:
Retailers sometimes offer cashback or store rewards through membership programs. For example, supermarkets, pharmacies, and warehouse stores may return store credit or savings points after purchases.
Cashback vs. points vs. miles: Which is better?
Although they are often grouped together under the category of 'rewards,' each one works differently and can be useful depending on a person's spending habits, financial goals, and lifestyle.
Cashback programs generally return a percentage of the money spent on eligible purchases. Points systems usually assign a numerical value to purchases that can later be redeemed for products, gift cards, discounts, or services. Travel miles are typically associated with airlines, hotels, or travel-focused credit cards.
| Cashback | Points | Miles |
|---|---|---|
| Returns money | Rewards system value | Travel-focused rewards |
| Flexible spending | Often redeemed in specific ecosystems | Usually tied to airlines or hotels |
| Reward after spending | Redemption values vary | Best for frequent travelers |
| Common for everyday purchases | May include gift cards or products | Often used for traveling |
For many people, especially those focused on getting some value on their everyday expenses such as groceries, transportation, gas, or household purchases, cashback can feel more useful as the reward is directly connected to money rather than conversion systems or travel programs.
3 practical tips for using cashback responsibly
1. Use cashback for purchases you already planned
Focus on recurring expenses such as groceries, gas, transportation, and utility bills. This helps you avoid overspending simply to earn rewards.
2. Don't buy things you don't need
A cashback offer does not automatically make a purchase worthwhile. For example, spending $200 to earn $4 cashback may not help your finances if the purchase was unnecessary.
3. Track your cashback earnings
Many apps and financial platforms allow you to monitor spending categories, cashback totals, and monthly rewards. Tracking your rewards can help you understand your spending patterns and maintain financial goals.
Does Común offer cashback?
No. Común does not currently offer cashback programs.
However, Común provides tools and resources that offer guidance for Latin American immigrants navigating the U.S. financial system.
While cashback might be useful for some people, it is important to pay attention to commissions, as savings when commissions are included might not be as strong as initially perceived. When comparing financial tools in the United States, cashback is only one factor to consider. Fees, commissions, account accessibility, and transparency can also affect your financial experience over time.
Común's cost for opening a debit account is $0, same as the $0 minimum balance and $0 monthly commission for the debit account.
FAQ
What is cashback and how does it work?
Cashback is a rewards system that returns a percentage of your purchases after you spend money using eligible cards, apps, or loyalty programs.
How is cashback calculated?
Cashback is usually calculated as a percentage of the purchase amount. For example, if you spend $100 and your cashback rate is 2%, you receive $2 back.
Where can I get cashback in the United States?
Cashback is commonly available through credit cards, debit cards, shopping apps, and retailer loyalty programs.
What is the difference between cashback and points?
Cashback returns money directly, while points are part of rewards systems that may only be redeemed for specific products, gift cards, or services.
Does Común offer cashback?
No. Común currently does not offer cashback.
Is cashback taxable?
In many cases, cashback earned through purchases is generally treated as a rebate rather than taxable income. However, tax treatment may vary depending on how rewards are earned. The IRS recommends consulting a tax professional for specific situations.
Living in the United States
Direct deposit vs wire transfer: comparison guide for U.S. immigrants
8 min de lectura
Direct deposit vs wire transfer: comparison guide for U.S. immigrants
These payment methods are both available in the U.S. but they are often used for different purposes. Direct deposit is commonly used for paychecks, tax refunds, and government benefits, while wire transfers are more often used for urgent or high-value transfers between financial institutions.
Understanding the difference between direct deposit and wire transfers can help you avoid unnecessary fees, choose the right payment method for your situation, and manage your money more confidently.
What's the difference between direct deposit and wire transfer?
The biggest difference is the purpose they serve. Direct deposit is commonly used for recurring payments such as salaries, benefits, and tax refunds. Wire transfers are commonly used to move money quickly between financial institutions, particularly for large or time-sensitive transactions.
| Feature | Direct deposit | Wire transfer |
|---|---|---|
| Common use | Paychecks, benefits, tax refunds | Large or urgent transfers |
| Network used | ACH network | Wire transfer network |
| Speed | Typically 1–3 business days | Often same day or next business day |
| Typical cost | Often no fee to receive | Fees may apply |
| International transfers | Limited | Commonly used |
| Recurring payments | Yes | Less common |
| Setup required | Routing + account number | Bank details + recipient information |
How direct deposit works
Direct deposit is one of the most common payment methods in the United States, particularly for employees receiving wages from an employer. Instead of issuing a paper check, an employer sends the payment electronically to the employee's bank account through the ACH network.
To set up direct deposit you need to provide your employer: your bank's routing number and your personal account number.
How wire transfer works
A wire transfer is an electronic transfer of funds between financial institutions through secure financial networks like Fedwire or SWIFT. Unlike direct deposit, wire transfers are better suited for large one-time payments, urgent payments, real estate transactions, or international transfers.
When to use each one
Use direct deposit for:
- Receiving your paycheck
- IRS tax refunds
- Social security or unemployment benefits
- Recurring business payments
Use wire transfer for:
- Real estate payments (down payment, closing)
- Urgent international transfers
- High-value business payments
- When the recipient specifically requires a wire transfer
How to set up direct deposit with Común
With your Común account, you can set up direct deposit by providing your Común routing number and account number to your employer. Your Común account has unique routing and account numbers available in the app. Visit comun.app to learn more.
FAQ
Is direct deposit faster than wire transfer?
Not necessarily. Domestic wire transfers can be faster (same day), while direct deposits usually take 1-3 business days. However, many accounts offer early access to direct deposits up to 2 days early.
How much does it cost to set up direct deposit?
Setting up direct deposit is generally no fee. Employers use the ACH network to send payroll electronically at no charge to the employee.
Común is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank, Member FDIC.
Financial Education
How to fill out a check in the United States in 5 simple steps (+ Example)
8 min de lectura
Have you ever filled out a check? Although most transactions today are digital, knowing how to fill out a check is essential—especially if you are just beginning your financial life.
According to recent data, one-third of Americans paid by check in 2024, demonstrating that checks still play an important role in the U.S. economy.
You might consider checks an outdated payment method; the reality is that they are useful in specific situations. For that reason, we will explain what a check is, the different types of checks, and how to complete them properly.
What Is a Check and What Is It Used For?
Despite the digital era, checks remain a relevant traditional payment method due to their formality and traceability. They are used for rent payments, purchases, and service payments.
Additionally, checks are a common payment method among the immigrant community, who often use them while adapting to the U.S. banking system.
But what exactly is a check and what are its characteristics? It is a physical document issued by an individual or business (the drawer) to order a bank to pay a specified amount to a third party. For the payment to be processed, the drawer must have sufficient funds in their checking account.
In general, a check contains the following information:
- Name of the drawer, whether an individual or a business
- Name of the payee
- Financial institution where the money will be drawn
- Amount to be paid, both in numbers and in words
- Signatures of the drawer
What Are the Different Types of Checks?
There are different types of checks in the United States. In this case, we will focus on the personal check, although you may choose the option that best suits your needs.
Personal Check
A personal check is a payment order issued by an individual to another individual using the funds in a checking account.
What Is a Personal Check Used For?
The most common uses for personal checks include:
- Rent and utility payments
- Purchase of everyday goods
- Legal agreements requiring documentary support
Certified Check
A certified check serves the same purpose as a personal check but is reviewed and guaranteed by the issuing bank, which verifies that the drawer has sufficient funds and holds them until the check is cashed.
A certified check provides certainty of available funds, making it a more secure method for making and receiving payments.
Cashier’s Check
Unlike a personal check, a cashier’s check is issued directly by the bank, offering greater security for the payee, as the bank is responsible for issuing and safeguarding the funds.
To obtain a cashier’s check, the drawer must visit a bank branch and pay the amount to be transferred. The bank then issues the check in the name of the payee, guaranteeing that it can be cashed using the institution’s own funds and not a personal account.
It is commonly used for high-value purchases such as homes and vehicles.
Money Order
While not strictly a check, it is a traditional payment method with similar functionality.
A money order is a financial instrument that allows funds to be sent via traditional mail using a certified check, which must be purchased and paid for by the drawer at an authorized location.
It allows secure money transfers without requiring a bank account.
How to Fill Out a Check in the U.S.
Before issuing this type of payment order, you must know how to do it properly. Below is an example of how to fill out a check easily, starting from step one:
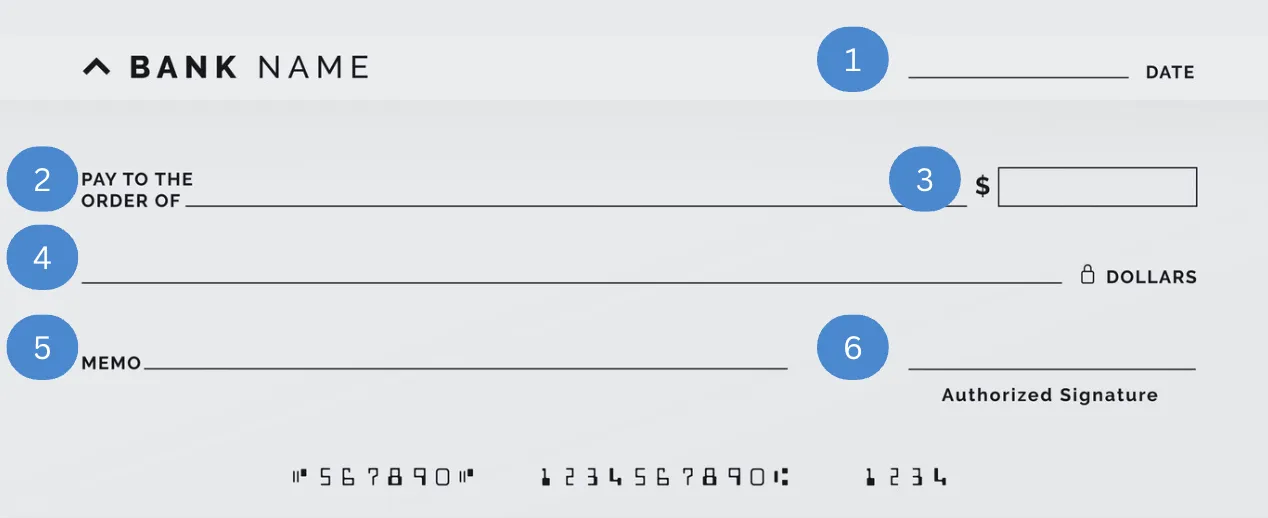
1. Write the Date
Remember that in the United States, the date format is mm/dd/yyyy.
2. Payee’s Name
Write the full name of the person to whom you are issuing the check, exactly as it appears on their official identification.
3. Amount in Numbers
Write the numerical amount clearly.
4. Amount in Words
Write the amount in words, including cents.
5. Add a Memo
You may include a note specifying the reason for the payment.
6. Sign the Check
Sign the check legibly in the space designated for the drawer.
7. Review the Information
Ensure that all information is accurate to avoid issues for the payee when cashing the check.
It is essential to complete checks legibly, without strike-throughs or corrections, as these may invalidate the document.
How to Correctly Write Numbers in Words on a Check
Writing amounts in words may be confusing when dealing with U.S. dollars. The following points should be kept in mind:
- Dollar amounts must be written in full words
- Cents must be written as fractions
- Avoid using dollar symbols or similar notations
- If there is leftover space at the end of the line, draw a line to prevent fraud
- For example, $1,000.75 is written as: One thousand and 75/100 dollars
Cash Checks and Manage Your Money Easily with Comun
As you can see, knowing how to fill out a check is useful for sending and receiving money in the United States. It is a reliable and accessible alternative if you do not have a banking account.
However, issuing and cashing a check can also require significant time and effort. That’s why you can skip the trip to the bank, avoid wasting time or money on gas, and cash your check directly from your phone using Comun—no lines, no questions, no complications.
Discover Comun, the only platform designed to serve the needs of immigrant communities in the United States, with support available in Spanish.
Why Choose Comun?
- Open your account with an official ID from your country
- Access a mobile app specifically designed for immigrants in the U.S.
- Make payments, receive your salary, and manage your finances
- Send money to your loved ones in LATAM for just a $2.99 transfer fee
Frequently Asked Questions
Still have questions about how to fill out a personal check? See our FAQ section.
What if I Make a Mistake Filling Out a Check?
If there are strike-throughs or inconsistencies in the amounts, the check must be voided and a new one used.
How Do I Void a Check?
Write the word VOID in large letters on the front of the check.
What Information Appears on the Back of a Check?
The back of the check contains the endorsement, meaning the payee’s signature for cashing the check.
Checking account
What do I need to open a traditional bank account as an immigrant?
8 min de lectura
For immigrants in the United States, having a banking account has become a basic necessity to carry out all types of daily tasks, such as shopping in physical and online stores, receiving wages, sending transfers and remittances, opening a savings account, among other things.
Despite the importance that a banking account has for immigrants and U.S. citizens, there are still factors that hinder the immigrant community’s access to banking, such as high fees and required documentation.
According to FDIC data, among vulnerable groups without banking accounts (unbanked), Hispanics make up 9.5%. This shows a gap that disadvantages a significant portion of the population.
Access to financial services is an increasingly attainable right for immigrants in the U.S. In this article, we will explain step by step what is required to open an account at a bank and on digital platforms, as well as the advantages of these solutions.
4 Requirements to Open a Banking Account in the United States
It is true that financial services make users’ lives easier and, in some way, improve their quality of life. But, what is needed to open a banking account in the United States?
Opening a bank account, whether a checking account or another type, requires meeting a series of requirements and presenting documentation, which may vary depending on the financial institution.
Some of the difficulties immigrants face when opening a banking account are not having an SSN (Social Security Number) or tax documentation, as well as the lack of information in Spanish.
Fortunately, beyond traditional banks, there are currently alternative solutions such as Común, a financial platform dedicated to meeting the needs of people who seek accessible and efficient services.
In general, these are the most common required documents to access a banking account in the United States.
Social Security Number (SSN)
This is the most common requirement for opening an account. It is an identifier for people who reside and work legally in the United States, and it is required for banks to carry out the identity verification process.
Individual Taxpayer Identification Number (ITIN)
The ITIN is an alternative for people who do not qualify for the SSN, since some financial institutions accept it instead.
Identity Document
For this requirement, it is possible to present a passport, a driver’s license, a government-issued ID, or a consular ID card. Any of these documents must be valid and show both name and photograph.
Proof of Address
To prove your residence in the United States, you can present utility bills, such as electricity, or even a digital account statement.
Step by Step: How to Open a Banking Account in the U.S. with Foreign Identification
The number of requirements requested by traditional institutions tends to make access to banking difficult, especially for immigrants without the previously listed documentation.
If you are looking for a practical and simpler solution than traditional banking services, you can turn to options like Común, the platform that streamlines processes and offers fair financial services for everyone.
Access to these services is possible with official, qualified foreign documentation, which helps reduce the gap in access to banking for immigrants.
Choose a Secure Platform that Accepts Foreign Identifications
In general, traditional banks request the SSN or ITIN, so a convenient option is to choose a digital platform with more flexible requirements but with the same quality and seriousness in their processes.
Común is a platform that makes immigrants’ lives easier in the United States, as it allows you to open an account with official, qualified documentation from your country of origin and simplifies the sign-up process without complicated paperwork.
Download the Mobile App and Set Up Your Account available in Spanish
You only need a mobile device compatible with Android or iOS to download the application, where you will create your profile and enter your information.
Verify your identity with an official ID from your country
Then, carry out the identity verification with your official ID from your country of origin. To do this, you will need to take a picture of it and possibly take a selfie.
Activate Your Card and Start Using Your Account
Once you provide the necessary documentation, you will have access to a debit card to make purchases at various establishments and will be able to make transfers and receive payments.
Use Additional Features Such as Sending Remittances or Deposits at Stores
For immigrants, it is essential to have services that allow them to send remittances to their countries of origin, so you can also use this benefit, in addition to making direct deposits in physical stores near you.
Which Bank in the U.S. Allows Opening an Account with a Passport? More Accessible Alternatives
There are alternatives with more flexible account opening options, such as Bank of America, which accepts the ITIN in case you do not have an SSN. However, the processes tend to be longer and slower compared to other digital platforms, which facilitate the sign-up process by offering greater feasibility in their requirements.
Bank of America
Bank of America supports the opening of banking accounts in the United States for immigrants, because it allows opening an account with a valid passport or ITIN. However, it is necessary to go in person to a branch to complete the process.
Común
Común is a digital platform that allows opening an account with more than 100 foreign IDs or with a valid passport, which makes it easier to obtain an account for immigrants and send remittances to Latin America for an affordable fee; in addition to making cash deposits at more than 100 stores.
Wells Fargo
Wells Fargo also accepts a passport as the main ID, but may request an additional identification, such as a credit card or student ID.
Wise
Wise is a fintech that offers digital accounts in different currencies. It is possible to access its services with a passport, ITIN, or SSN.
Revolut
Revolut is another alternative for non-citizens in the United States, since it accepts a passport as identification; among other options, such as a driver’s license or national ID.
Why Común is Ideal for Opening Your Account in the U.S.?
Although the requirements to open an account may make it seem like an inaccessible process for many immigrants in the U.S., fortunately, there are also more accessible options.
If you are looking for a clear, reliable alternative available in Spanish, it is time to change your relationship with finances through Común: a service that truly understands your needs.
Why is Común Your Ally?
Forget about minimum deposits or monthly charges
Access a mobile app available in Spanish with a user-friendly interface
Send money to your home country for a fee starting at $2.99, up to the applicable limits
Deposit cash at a network of establishments near you
It has 24/7 customer support available in Spanish
Remember that Común offers you a service available in Spanish with simple processes. Open your account today and start using a service designed for you!
Financial Education
Banking Services for Small Businesses: A Complete Guide
8 min de lectura
Small Businesses
Running a small business involves making numerous financial decisions, and choosing the right banking services is crucial for success. Separating personal assets from business assets in an LLC structure is important for protecting personal property in case of business bankruptcy. Community banks and modern financial platforms offer a variety of services tailored to meet small businesses' unique needs. This complete guide explores the essential banking services for small businesses, highlighting their benefits and how they can support growth and stability.
Understanding Different Types of Small Businesses and Their Banking Needs
Before exploring specific banking services, it's essential to understand the range of small businesses and their unique financial needs. Different types of small businesses — like sole proprietorships, partnerships, LLCs, corporations, nonprofits, home-based businesses, and startups — require tailored banking solutions to support their growth and stability. Keeping business and personal bank accounts separate offers benefits like accurate record-keeping, simplified tax preparation, better financial organization, and enhanced professionalism. By recognizing these differences, you can better appreciate how community banks and financial platforms like Común meet small business owners' diverse needs. This understanding lays the groundwork for selecting the most appropriate banking services to ensure financial health and success.
Business Checking and Savings Accounts
Having a dedicated business checking account is fundamental to managing your finances effectively. It lets you separate personal and business transactions, simplifying bookkeeping and ensuring clear financial records. Many banks offer business checking accounts with features like free transactions, low fees, and online banking capabilities.
When opening a business bank account, gather the required documentation, like your Employer Identification Number (EIN), and decide whether you want to apply online or visit a branch. Understanding the fees and essential steps to open the account is crucial.
A business savings account is also vital. It helps you set aside funds for future investments, emergencies, or growth opportunities. Look for accounts with competitive interest rates and flexible access to your funds.
Business Loans and Lines of Credit
Access to credit is often essential for small business growth. Community banks and other financial institutions provide various loan products, including term loans, lines of credit, and SBA loans. These financial products can help you finance new equipment, expand operations, or cover unexpected expenses.
- Term Loans: Term loans issue lump sums of capital that are repaid over fixed periods of time with predetermined interest rates. They're suited for large, one-time investments, like purchasing equipment or renovating a workspace. The predictable repayment schedule helps with budgeting and long-term planning.
- Lines of Credit: Lines of credit offer flexible borrowing options, letting you draw funds as needed and pay interest only on the amount you use. This flexibility can be a lifesaver during cash flow shortages or when financing immediate needs, like inventory purchases or emergency repairs. Lines of credit are revolving, meaning funds become available again as you repay them, making them an ongoing financial resource.
- SBA Loans: Small Business Administration (SBA) loans are partially government-guaranteed, making them more accessible to small businesses that might not qualify for traditional loans. They offer competitive interest rates and longer repayment terms, which can be particularly beneficial for startups and businesses with less-established credit histories.
Working with a community bank for loans and lines of credit means you benefit from personalized service. Bank representatives can provide tailored advice, helping you choose the right loan product for your needs and guiding you through the application process. This relationship-based approach ensures you get the support needed to grow your business sustainably.

Payment Processing, Payroll, and Cash Flow Management Services
Effective financial operations are critical to any small business's success. This includes processing payments, managing payroll, and ensuring efficient cash flow. Here's how comprehensive banking services can support these needs:
- Merchant Services: Merchant services are crucial for businesses that need to process customer payments. These services include credit card processing, point-of-sale (POS) systems, and online payment gateways. A reliable merchant services provider ensures transactions are processed quickly and securely, improving customer satisfaction and cash flow. By offering seamless payment solutions, banks help businesses deliver a better customer experience and streamline their revenue collection process.
- Payroll Services: Managing payroll can be complex and time-consuming. Many banks offer payroll services to simplify this process. These services handle everything from calculating wages and taxes to direct deposits and payroll tax filing. By outsourcing payroll, businesses can ensure accuracy and compliance with tax regulations, freeing up time to focus on core operations. Efficient payroll management not only saves time, but also helps maintain employee satisfaction by ensuring timely, accurate payments.
- Cash Management: Effective cash management is essential to maintaining healthy cash flow. Banks offer various cash management services, including remote deposit capture, ACH payments, and wire transfers. These tools help businesses efficiently manage incoming and outgoing funds, reducing time spent on manual processes and improving overall financial control. Proper cash management ensures businesses can meet their financial obligations and invest in growth opportunities without experiencing cash shortages.
By integrating these services, banks provide a comprehensive solution that supports small businesses in maintaining smooth, efficient financial operations.
Online and Mobile Banking
In today's digital age, online and mobile banking are indispensable. These services provide convenient access to your accounts, letting you monitor transactions, transfer funds, and pay bills anytime, anywhere.
- Digital Transformation: Community banks are adopting new technologies to improve the customer experience through online and mobile banking platforms. These platforms offer 24/7 access to your accounts, letting you manage your finances from the comfort of home or on the go. You can easily check balances, view transaction history, and transfer funds between accounts.
- Advanced Features: Many online and mobile banking services include features like bill pay, mobile check deposit, and budgeting tools. Bill pay lets you schedule payments to vendors and service providers directly from your account, ensuring timely payments and simplifying your bookkeeping. Mobile check deposit lets you deposit checks by taking a photo with your smartphone, saving trips to the bank.
- Security Measures: Online and mobile banking platforms use advanced security measures to protect customer data and ensure secure transactions. This includes encryption to protect information, multi-factor authentication to verify user identity, and regular security audits to identify and address potential vulnerabilities. Real-time fraud alerts help you quickly detect and respond to suspicious activity, improving your overall financial security.
Open your bank account¹ in 3 minutes with your country's ID²
Common Problems Small Businesses Face With Banking Services and Financial Health
While banking services are crucial to small business operations and growth, many small business owners face various challenges when managing their financial needs. Understanding these issues can help businesses make more informed decisions and find solutions that better fit their requirements.
- High Fees and Hidden Costs: Many small business owners find that banking services come with high fees, including monthly maintenance charges, transaction fees, and penalties for not maintaining a minimum balance. Hidden costs, like wire transfer fees, overdrafts, and additional services, can also add up, putting pressure on the business's cash flow.
- Limited Access to Credit: Securing loans and lines of credit can be particularly challenging for small businesses, especially startups or those with less-established credit histories. Traditional banks often have strict lending criteria, making it difficult for small business owners to access the funds they need for growth and operations.
- Inadequate Customer Service: Small business owners frequently report dissatisfaction with the customer service provided by their banks. Long wait times, lack of personalized service, and insufficient support for small-business-specific issues can hinder a business's ability to effectively manage its finances and resolve issues quickly.
- Complexity and Inaccessibility: Banking services can often be complex and difficult to navigate. Small business owners, who may not have extensive financial knowledge, can find it challenging to understand and use the full range of services offered. Additionally, inaccessibility to bank branches or limited online services can be a significant obstacle for businesses that require frequent banking interactions.
- Security Concerns: With the growing prevalence of cyber threats, security is a major concern for small businesses. Ensuring banking services offer robust security measures to protect sensitive financial data is crucial. However, not all banks offer the same level of security, leaving some businesses vulnerable to fraud and data breaches.
- Integration With Business Tools: Small businesses often use various tools and software to manage their operations, like accounting software and payment processing systems. Issues can arise when banking services don't integrate smoothly with these tools, leading to inefficiencies and increased administrative burden.
- Lack of Financial Education and Support: Many small business owners struggle with financial literacy, which affects their ability to make informed banking and financial decisions. Banks that don't offer enough financial education resources or support can leave business owners feeling overwhelmed and ill-prepared to manage their finances effectively.
- Limited Product Offerings: Some banks may not offer a wide range of products tailored to small businesses' specific needs. This can include specialized loan products, cash management services, or flexible payment solutions. Limited product offerings can restrict a business's ability to find suitable financial tools that support its growth and operational needs.
Understanding these common issues can help small business owners better navigate the challenges they face with banking services. By seeking out community banks or financial platforms like Común that prioritize transparency, customer service, security, and integration with business tools, small businesses can find banking solutions better suited to their needs and supportive of their financial success.
Conclusion:
Choosing the right banking services is essential for your small business's success and growth. From checking and savings accounts to loans, merchant services, and digital banking, the right financial products and support can help you manage your finances effectively and reach your business goals. By partnering with a community bank and leveraging platforms like Común you can access the tools and expertise needed to thrive in today's competitive market.
Integration and Support
Many community banks pride themselves on offering personalized service and financial advice. Building a relationship with your bank can provide valuable insight into managing your finances, accessing credit, and planning for future growth. Take advantage of workshops, seminars, and one-on-one consultations offered by your bank to improve your financial literacy and business knowledge.
For small businesses looking to leverage modern financial technology, integration with platforms like Común can improve their banking experience. Común offers a range of features tailored to small businesses, including instant notifications, secure login, and personalized customer support available seven days a week. By combining the strengths of traditional community banking with the convenience of digital banking, Común provides a comprehensive solution for managing your business finances.
Open your bank account¹ in 3 minutes with your country's ID²

Financial Education
What is a wire transfer? A complete guide to sending money in the U.S.
8 min de lectura
Every day, millions of people in the United States rely on different methods to send money safely and quickly, whether within the country or, in the case of immigrants, to their countries of origin.
The wire transfer is one of the most popular methods for sending money through financial institutions that provide backing and traceability to ensure the recipient receives the funds.
According to Federal Reserve (Fedwire) data, in 2024 there were 209.9 million wire transfers, representing 8.6% growth compared to the prior year.
Today, the dynamism of the financial system has led to different solutions for making domestic and international money transfers. That is why it is important to understand what a wire transfer is, how it works, and its advantages and disadvantages.
How does a bank transfer or wire transfer work?
A bank transfer or wire transfer is an electronic method of sending money from one bank account to another in real time and without the need for cash. It is especially advisable for transmitting large amounts when extra security is required.
The mechanism for using this transfer service is as follows.
Initiation by the sender
To make an electronic transfer, the sender must initiate the process, either in person (at a bank) or digitally (through a mobile application).
At the beginning of the process, it is necessary to provide the recipient’s information in order to complete the transaction.
Sending of instructions
The bank or financial institution verifies and validates the funds, as well as their sufficiency or insufficiency in the sender’s bank account.
Receipt and crediting
Once the information has been validated, the funds are sent to the indicated account through secure networks according to the type of money transfer.
- Fedwire: a system operated by the National Reserve, for transfers of large amounts of money within the United States
- CHIPS: a system operated by The Clearing House, for international transfers
Advantages and disadvantages of bank transfers (Wire Transfers)
Making a wire transfer has several pros and cons, such as the following.
Advantages
Speed
In the case of domestic wire transfers, the money is deposited within minutes or in less than one business day, making it advisable for urgent payments.
For international bank transfers, the time can range from 1 to 3 business days, so you should consider this limitation if you need to send money outside the United States.
Security
Money moves through official U.S. networks, which provides certainty and facilitates tracking. It also reduces the risk of fraud and scams by dispensing with traditional payment methods such as cash or checks.
Ideal for large amounts
Compared with other transfer platforms (such as Zelle, Western Union, and ACH transfers), wire transfers do not have send limits that are as low, making them ideal for moving large amounts of funds safely and quickly.
Traceability
When a wire transfer is made, each movement is recorded through the networks used, making it easy to trace the money if any issue arises during the process.
Disadvantages
Cost
Banks charge transfer fees that are considerably higher compared with other alternatives.
The cost of domestic transfers ranges from $15 to $30 USD, while international transfers can exceed $50 USD if intermediary institutions must participate in the process.
Irreversibility
If an error is made or you are the victim of fraud, a transfer cannot be reversed. In addition, the bank is not responsible for erroneous electronic payments that were duly authorized.
Detailed information required
To complete the transfer, precise information is required, such as the SWIFT code and the recipient’s name. If a figure is incorrect, the operation will still be carried out.
There are more accessible alternatives for making electronic transfers, such as Común, which provides access to a mobile application and a debit card, with simple procedures. In addition, Común account funds are FDIC insured up to the applicable limits through an FDIC-insured bank.
Required information and how to make a Wire Transfer effectively
Before making an electronic transfer, it is crucial to gather the necessary information so that your money reaches its destination without issues.
Essential data to send a wire transfer
Recipient’s full name
Make sure to write it exactly as it appears on their account.
Name of the receiving bank
Write the bank’s full name, without acronyms or abbreviations.
Routing number (ABA) for domestic transfers in the U.S.
It is a 9-digit code that identifies each bank in the United States.
SWIFT/BIC code for international transfers
It is an international identifier for each bank.
Bank account number or IBAN for international transfers
The IBAN is an international code that includes the country identifier, the bank identifier, and the bank account number.
Exact amount to send
It is very important to verify the amount to be sent, because an erroneous operation cannot be canceled.
Tips for a successful and secure transfer
Before making this type of transfer, it is essential to keep some recommendations in mind to avoid issues or errors that could affect your finances.
Double-check all information
Take the time to ensure you have entered exact and correct information, since once a transfer is authorized, it cannot be reversed.
Understand all associated fees before sending
Transfer fees depend on various factors, such as the issuing bank, amount, and—if international transfers are involved—the participation of intermediaries and the exchange rate used.
It is very important to understand all costs involved in a wire transfer, as in some cases the figure can be quite high and not very competitive.
Use reliable and transparent platforms
Ensure that your bank is a reliable institution and has appropriate security measures to handle large amounts of money. Identify whether it has FDIC backing to insure bank deposits in the United States.
Stay alert to possible fraud
Avoid sharing personal information with strangers, as well as passwords or verification codes. If you have any doubts or receive a suspicious call, contact the financial institution directly.
Común: The solution for your transfers in the U.S.
Now that you know what a wire transfer is, you will see that it is very useful for moving money, especially when large amounts are involved and a secure, fast method is sought. However, there are modern alternatives that make sending money easier.
Común offers a more accessible alternative that simplifies money management, especially for immigrants in the United States.
In addition, it offers a simple platform for making domestic and international transfers for a fee starting at $2.99 USD, up to the applicable limits.
Discover an easier way to manage your finances from the palm of your hand. Download the Común mobile app and transfer money without complications.
Frequently Asked Questions
What is the difference between a bank transfer and a wire transfer?
A bank transfer is the general way to refer to any type of digital movement of money. A wire transfer refers to the network used to carry it out. There are also ACH (Automated Clearing House) transfers and mobile payments.
How long does it take to process a wire transfer?
For domestic transfers, they are usually completed the same day if initiated before the cut-off time. After that time, they take about one business day.
International transfers usually take 1 to 3 business days.
Can I cancel a wire transfer once it has been sent?
No, it is not possible to cancel a wire transfer once it has been fully processed.
Are there amount limits for wire transfers?
There is no set limit; it depends on each bank. However, the permitted amounts are higher than with other alternatives.
Financial Education
How to Cash a Check: A Step-by-Step Process
8 min de lectura
With Común you can cash a check without going to a bank: take a photo of it in the app and the money is deposited into your account at no cost. You can also use the network of over 88,000 cash-deposit locations if you prefer to cash it in person.
In the world of finance, the ability to cash a check efficiently and securely is a fundamental necessity. From payroll checks to tax refund checks, the mechanism of turning these paper promises into real purchasing power is a critical aspect of financial management. This article provides a guide on what a check is, how to cash it, and where to do so, ensuring you are well equipped to navigate this process.
What Is a Check?
A check is a written, dated, and signed instrument that orders a bank to pay a specific amount of money from the issuer’s account to the person or entity whose name is written on the check. The recipient (payee) then deposits or cashes the check to access the funds.
Checks are a traditional form of payment that allow individuals and businesses to make transactions without the need for immediate cash exchange. They can be used for a wide range of payments, from personal gifts to payroll and business transactions.
Checks offer a traceable payment method, providing a paper trail that can be useful for accounting and tax purposes. They remain a fundamental component of financial transactions, offering a combination of security, convenience, and versatility. Despite the rise of digital payments, the relevance of various types of checks persists, serving diverse needs from everyday payments to significant financial dealings. Here are the different types of checks:
- Personal Checks: These are the most common type, issued by individuals and generally drawn from a checking account. They are used to pay bills, rent, or transfer money to family and friends.
- Cashier’s Checks: These are issued by banks themselves, guaranteeing funds are available because the bank holds the amount until the check is cashed. They are often used in major transactions, such as down payments on a house.
- Certified Checks: These are personal checks verified by a bank. The bank certifies that the signature is genuine and that the issuer has sufficient funds in their account to cover the check amount at the time of issuance.
- Money Orders: These are a prepaid payment method, similar to checks but generally considered safer because they require upfront payment. Money orders are widely accepted and can be purchased at banks, post offices, and even some retail stores.
- Traveler’s Checks: These are preprinted fixed-amount checks designed to allow travelers to carry money without cash. They can be exchanged for local currency at banks, exchange offices, or some retailers and are protected against loss or theft.
- Government Checks: These include tax refunds, Social Security benefits, and other payments issued by the government. These are considered very secure, as they are backed by the government.
From personal to certified checks, each type plays a specific role, ensuring that individuals and businesses have the flexibility to manage their money securely and efficiently. Despite the growing prevalence of digital finance, checks continue to hold their place, offering an indispensable option for a wide variety of financial dealings. Understanding the functionality and usefulness of different types of checks remains key to optimizing financial transactions and strategies.
How to Cash Your Check
The journey from receiving a check to turning it into cash or depositing it into your bank account is simplified by understanding a few key steps. Using advances in banking technology and the expertise of bank tellers, let us dive into the methodical approach to accessing your funds.
Step 1: Endorse Your Check
Start by endorsing your check, a necessary step that indicates your intent to cash or deposit it. Turn the check over and sign your name in the specified area on the back.
Step 2: Prepare Your Identification
Having a valid form of identification is crucial. This could be a driver’s license, a government-issued ID, or any other official identification, ensuring that the check is cashed or deposited by its legitimate owner.
Step 3: Choose Where to Cash the Check
Your options include a local bank or credit union, where checking accounts often provide lower fees for account holders, or a check-cashing service for those without a bank account. In addition, certain retailers and grocery stores with a customer service desk may offer check-cashing services, usually for a small fee.
Step 4: Present Your Check and Identification
At your chosen location, present the endorsed check and your ID. The teller or service representative will verify your identity and the check’s authenticity.
Step 5: Decide Between Cash or Deposit
Choose whether you want to cash the check or deposit it into your account. This decision may affect whether you opt for a direct deposit into a linked bank account, use mobile deposit options, or even load funds onto a prepaid debit card.
Step 6: Complete the Transaction
The teller processes your check based on your decision. Deposits may require a short wait for funds to become available, while cashing it provides immediate access to your money.
Step 7: Obtain a Receipt
Always make sure to get a receipt after the transaction. This serves as a record of your action, important for personal financial tracking and potential inquiries.
Cashing your check is a straightforward process when you follow these essential steps, from endorsement to choosing your cashing location. Each stage is designed to ensure access to your funds is secure, convenient, and tailored to your financial needs, highlighting the importance of understanding your banking options.
Where to Cash Your Check and the Associated Fees
Identifying a reliable and efficient place to cash your check, whether it involves government checks, insurance settlement checks, or two-party personal checks, is paramount. The landscape offers several avenues, each with its own set of benefits and considerations.
Banks and Credit Unions
Traditional and secure, if the check is drawn against an account at the same institution, cashing it is typically free. These places are ideal for those with their own bank accounts, offering services such as cashing cashier’s checks and government and payroll checks. Associated Fees: If you have an account at the bank or credit union where the check was drawn, cashing a check is generally free. Some banks may still charge a fee if the check comes from a different bank, but this is increasingly uncommon.
Check-Cashing Services
A viable option for immediate needs or for individuals without bank accounts, though often accompanied by fees. Check-cashing stores and services such as Ingo Money provide versatility but may involve check-cashing limits or higher fees. Associated Fees: These services are convenient but often come with higher fees. They may charge a flat fee plus a percentage of the check amount, which can range from 1% to 4% or more. For example, cashing a $1,000 check at a service that charges 2% would cost $20.
Retail Stores
A very convenient option, many stores and gas stations now offer check cashing for a flat fee or a percentage of the check amount. This can be particularly helpful for cashing checks such as payroll or government checks on the go. Associated Fees: Some supermarkets and convenience stores cash checks for a fee, which may be lower than check-cashing services. Fees at retailers are often a flat fee (for example, $3 to $6 for checks up to a certain dollar amount) plus an additional fee for larger amounts.
Digital Options
Mobile deposits and services linked to PayPal accounts or prepaid cards allow you to deposit checks without visiting a bank. This method suits those comfortable with digital banking, offering a way to deposit checks directly into a linked account or prepaid card. Associated Fees: If there are fees, they are often structured similarly to Ingo Money or PayPal services for immediate access, but they are usually waived if you are willing to wait for the standard clearing time.
The decision spans traditional banking institutions, check-cashing services, retail points of sale, and innovative digital platforms, each catering to different needs and preferences. Whether you prioritize convenience, low fees, or immediate access to cash, there is a tailored option for your situation. As we move toward an increasingly digital world, the value of the physical check remains undeniable in its usefulness and necessity.
Conclusion
Cashing a check efficiently depends on understanding your options and the associated fees. Whether you prefer the traditional security of a bank or credit union, the convenience of a check-cashing service, or the modern approach of mobile deposits, the key is to weigh these options against your immediate financial needs and the costs involved. By integrating money-saving strategies, such as avoiding high fees and opting for direct deposit, you can ensure a smooth and stress-free process while making the most of your financial resources.
How do I cash a check with the Común app?
Open the app, go to the check deposit section, take a photo of the front and back (make sure it's signed in the endorsement area), and confirm the amount. Mobile check deposit is at no cost.
How long does it take for the check funds to show up?
Timing varies depending on the amount and your account history; the app shows you an estimate before you confirm the deposit.
What are my options if I don't want to use mobile deposit?
Común has a network of over 88,000 cash-deposit locations, and you can withdraw at AllPoint+ ATMs at no cost (3 free withdrawals a month, then $2.50 per withdrawal).
Frequently asked questions
Does cashing a check through the Común app cost anything?
No, mobile check deposit through the app is at no cost.
What do I need to deposit a check through the app?
Just your phone with the Común app, the physical check signed in the endorsement area, and good lighting for the photo.
Can I cash any type of check with Común?
The app guides you through the process; make sure the check is current, properly signed, and has complete information before photographing it.
What happens if my check deposit is rejected?
The app will notify you if there's an issue with the deposit; check that the check's details are legible and complete.
Can I withdraw the cash from a deposited check at an ATM?
Yes, once the deposit shows in your account, you can withdraw at any AllPoint+ ATM at no cost (up to 3 times a month).
Does Común charge for each check I deposit?
No, mobile check deposit has no fee.
Community
Community Banking: Supporting Local Economies
8 min de lectura
Community banking focuses on meeting the financial needs of specific communities, often underserved by large traditional banks. Digital platforms like Común extend that approach to the immigrant community, with documentation requirements adapted to their reality.
Community Banks: Local Investment, Knowledge, and Education
Community banks are known for their personalized approach to banking. With a deep understanding of the local economy, these banks can offer financial products and services tailored to the specific needs of their customers. This localized knowledge allows them to provide better advice and more flexible solutions for individuals and businesses within the community.
In addition, they invest significantly in their local areas. They reinvest deposits back into the community through loans to local residents, small businesses, and organizations. This cycle of local investment promotes economic development and helps create jobs, contributing to the overall prosperity of the community. The relationships built between community banks and their customers go beyond simple transactions. These banks often participate in local events, support community projects, and contribute to charitable causes.
Their active involvement in the community strengthens trust and creates a sense of shared purpose and commitment to local well-being. In addition, community banks play a crucial role in providing financial education. By offering workshops, seminars, and one-on-one consultations, they help community members improve their financial literacy. This education empowers individuals to make informed decisions, manage their finances effectively, and plan for their future.
Común - Banking designed for your life in the USA
Open your bank account¹ in 3 minutes with your country ID²
Stability and Trust: Aspects of Community Banking
Stability and trust are the pillars of community banking, forming the foundation of the relationship between banks and their customers. These attributes are particularly crucial for ensuring economic resilience and fostering customer confidence, which together create a stable financial environment for both individuals and businesses.
Community banks tend to take a conservative approach to lending and investing, focusing on sustainable growth and prudent risk management. This strategy often makes them more resilient during economic downturns, allowing them to continue supporting their customers even in difficult times. The emphasis on building long-term relationships means that community banks are more likely to provide ongoing support during periods of financial instability, further fostering a stable financial environment.
Customer trust is significantly enhanced through the personalized service offered by community banks. Customers appreciate the ability to speak directly with bank representatives who understand their unique circumstances and needs, fostering a sense of reliability and security. In addition, community banks often prioritize transparency in their operations, from clear communication about fees and services to straightforward loan terms. This transparency builds customer trust and confidence in the bank’s integrity.
Active involvement in local communities also reinforces the trust customers place in community banks. By supporting local initiatives, sponsoring events, and participating in community activities, these banks demonstrate their commitment to the well-being of their customers and the broader community. This involvement not only strengthens the relationship between the bank and its customers, but also contributes to the overall prosperity of the community.
Financial security is another critical aspect of stability and trust in community banking. Deposits at community banks are typically insured by the Federal Deposit Insurance Corporation (FDIC), providing an additional layer of security for customers’ funds and assuring them that their money is protected. In addition, community banks often have robust fraud protection measures in place. Their local presence allows them to monitor and quickly address suspicious activity, further enhancing customers’ sense of security.
In short, the stability and trust that define community banking are essential to economic resilience, customer confidence, and financial security. These qualities enable community banks to effectively support their customers, even in difficult times, and maintain strong, lasting relationships within their communities.
How Integrating Común.app Improves Stability and Trust:
Stability and trust are fundamental to the success of community banking, fostering long-term relationships and financial security for customers. By integrating Común.app into their banking experience, users can enjoy the benefits of personalized service, financial security, and community support in a modern and convenient format. Here’s how integrating Común.app improves stability and trust in the community:
- Instant Access to Information: Común.app gives users instant access to account information, transaction history, and real-time notifications. This transparency helps customers stay informed and confident about their financial status, increasing trust in the platform.
- FDIC Insurance and Fraud Protection: Just like traditional community banks, Común.app accounts are FDIC insured, and the app includes robust security measures to protect against unauthorized transactions. This combination of security features ensures that customers’ funds are safe, reinforcing their trust in the digital banking service.
- User-Friendly Experience: Común.app provides a user-friendly experience with intuitive navigation and easy access to essential banking services. This accessibility builds customer trust, as users can manage their finances conveniently and efficiently.
- Personalized Customer Support: Común.app offers top-quality customer service available seven days a week via chat, email, or phone. This commitment to customer support reflects the personalized service of traditional community banks, fostering a sense of reliability and trust.
- Financial Inclusion and Community Focus: Común.app emphasizes financial inclusion, serving Latin American immigrants and other underserved communities. By offering services without the need for a Social Security Number and focusing on customer protection regardless of immigration status, Comun.app builds trust among its users and aligns with the community-centered values of traditional banks.
- Educational Resources: Común.app also provides educational resources to help users improve their financial literacy. By offering guidance on how to manage finances, understand banking services, and make informed decisions, Común.app empowers its users, increasing their confidence in the platform.
Choosing Común means choosing a trusted partner dedicated to supporting the financial well-being of its customers, just like a traditional community bank.
Banking designed for your life in the USA
Open your bank account¹ in 3 minutes with your country ID²
Technology and Innovation in Community Banking
Community banks are increasingly embracing digital transformation to improve the customer experience and stay competitive. By adopting online and mobile banking platforms, they provide customers with convenient access to their accounts, the ability to transfer funds, pay bills, and monitor transactions from anywhere at any time. These digital services offer a level of convenience that meets the expectations of modern tech-savvy customers.
The importance of keeping up with technological advances cannot be overstated. As customer needs evolve, community banks must continuously update their digital offerings to provide seamless and user-friendly experiences. This includes integrating features such as instant notifications, secure login options, and personalized financial tools. By doing so, they ensure they remain relevant and appealing to both existing and potential customers.
Cybersecurity
Alongside digital transformation, community banks are prioritizing cybersecurity to protect customer data and ensure secure transactions. Advanced encryption techniques protect sensitive information from unauthorized access. Multi-factor authentication adds an additional layer of security, requiring customers to verify their identities through multiple methods before accessing their accounts.
Security audits are carried out regularly to identify and address potential vulnerabilities. These audits help ensure that cybersecurity measures are up to date and effective against emerging threats. By implementing these robust security measures, community banks not only protect their customers, but also build and maintain trust, reinforcing their reputation as secure and reliable financial institutions.
Overall, technology and innovation in community banking are essential for improving customer satisfaction, increasing operational efficiency, and maintaining security in an increasingly digital world.
Conclusion
Community banks are indispensable to the health and vitality of local economies. Through personalized service, support for small businesses, investment in the community, relationship-building, financial education, and stability, these institutions create a strong economic foundation. By choosing a community bank, individuals and businesses can contribute to the growth and success of their local area, fostering a prosperous and interconnected community.
Key Benefits of Community Banks:
- Personalized Service: Tailored financial products and services.
- Support for Small Businesses: Loans and credit for local businesses.
- Community Investment: Reinvests deposits in the local economy.
- Relationship Building: Active participation in community events and causes.
- Financial Education: Workshops and consultations to improve financial literacy.
- Stability and Trust: Resilience during economic downturns.
By supporting community banks, you are supporting the growth and prosperity of your local economy.
What is community banking?
It's a financial services model focused on serving specific communities — geographic, cultural, or need-based — that often have less access to traditional banking.
How does community banking benefit local economies?
By making bank accounts, remittances, and savings more accessible, it helps more people participate in the formal economy instead of relying on informal services with higher fees.
How does this approach apply to the immigrant community in the U.S.?
Platforms like Común accept Latin American IDs instead of requiring an SSN, specifically addressing the documentation barriers this community faces.
Frequently asked questions
What sets community banking apart from a large traditional bank?
It focuses on the specific needs of a particular community, with adapted requirements and products, instead of a generic model.
Does community banking only exist for geographic communities?
No, it can also focus on cultural or need-based communities, like the immigrant community.
How does this help the local economy?
More people with formal banking access means less reliance on costly informal services, like check-cashing stores.
Is Común an example of community banking?
Común is a digital financial platform designed for the immigrant community, with documentation requirements adapted to that community.
What documentation requirements does Común adapt?
It accepts over 100 Latin American IDs instead of requiring a Social Security Number.
Does community banking have the same costs as traditional banking?
It varies by provider; many digital community banking platforms, including Común, don't charge a monthly fee or require a minimum balance.
Living in the United States
Identity theft in the U.S.: protection guide for immigrants
8 min de lectura
Identity theft happens when a person uses someone else’s personal information, such as a Social Security number (SSN), Individual Taxpayer Identification Number (ITIN), or financial account information, to commit fraud. Scammers often target immigrants through fake government agencies, employment offers, and immigration-related schemes designed to collect personal information. If identity theft happens, it is important to report it quickly through IdentityTheft.gov and to follow the recommended steps that may help reduce the damage.
Identity theft can happen to anyone, regardless of their immigration status. Knowing how to recognize the warning signs, respond quickly, and protect sensitive information can make recovering from identity theft easier.
This article is for informational purposes only. If you are a victim of identity theft, visit IdentityTheft.gov for official guidance.
What is identity theft and why are immigrants frequent targets?
Identity theft occurs when another person uses someone else's personal information without permission to open financial accounts, apply for credit, file tax returns, obtain employment, or commit other forms of fraud. In many cases, victims may not discover the problem until they receive unexpected bills, notice unfamiliar activity on their financial accounts, or are denied credit they never requested.
Immigrants are frequently targeted by scams designed to collect personal information. People who have recently arrived in the United States may also be less familiar with credit reports, fraud alerts, credit freezes, or official government procedures. Fraudsters may pretend to represent government agencies, immigration services, employers, financial institutions, or utility companies. These scams often pressure people into sharing an SSN, ITIN, passport information, debit card numbers, or online account credentials.
Sharing personal information does not automatically lead to identity theft, but it can give criminals the information they need to misuse someone's identity. That is why it is important to verify who is requesting personal information before providing it and to avoid responding to unsolicited phone calls, emails, text messages, or social media messages asking for sensitive information.
Identity theft is different from a financial scam. A scam may involve convincing someone to send money voluntarily. Identity theft involves using personal information without permission to impersonate another person or commit fraud in their name. In some situations, both can happen at the same time.
What are the warning signs of identity theft?
Identity theft often develops gradually. Small warning signs may appear weeks or even months before a victim realizes someone has been using their information. Therefore, it is important to pay attention to unexpected financial or tax notices.
The following situations are some common warning signs of identity theft.
| Warning sign | What it could mean |
|---|---|
| Unexpected bills or collection calls | Someone may have opened an account in your name. |
| Denial of a loan or financial account you never applied for | Your credit history may contain fraudulent activity. |
| IRS notice about income you did not earn | Someone may be using your SSN or ITIN for tax-related fraud or employment. |
| Mail stops arriving or unfamiliar mail appears | Someone may have changed your mailing address without your knowledge. |
| Unfamiliar accounts on your credit report | Financial accounts may have been opened using your personal information. |
| Charges you do not recognize on your account statement | Someone may have gained access to your financial account or payment information. |
Not every unfamiliar transaction means identity theft has occurred. Sometimes a merchant name appears differently on an account statement, or a family member may have made a purchase. Even so, unexpected activity should be reviewed as soon as possible so any unauthorized transactions can be reported promptly.
Another important warning sign is receiving verification codes, password reset emails, or notifications about accounts that were never created. These messages can indicate that someone is attempting to access an online account or register an account using your personal information.
Checking credit reports periodically may also help identify unfamiliar accounts before they become a more serious problem. Reviewing financial statements regularly, monitoring account activity, and responding quickly to unexpected notices can reduce the amount of time fraudulent activity goes unnoticed.
Finally, you should trust your instincts when something feels unusual. Receiving repeated phone calls requesting personal information, being pressured to confirm an SSN or ITIN, or being told that immediate payment is required to avoid legal consequences are all situations that deserve additional verification before sharing any sensitive information. These tactics are commonly used by scammers to collect the personal details needed to commit identity theft.
What should you do immediately if your identity is stolen?
If identity theft is suspected, acting quickly can help limit financial losses and make the recovery process easier. The Federal Trade Commission (FTC) recommends creating a recovery plan through IdentityTheft.gov as soon as possible. The site generates personalized steps based on the type of identity theft reported.
If a financial account may have been compromised, contact the financial institution immediately to report the suspicious activity to help secure the account. Changing passwords and enabling two-factor authentication on important accounts can also help prevent additional unauthorized access.
If someone may have opened credit accounts using your personal information, consider placing a fraud alert or credit freeze with the major credit bureaus. These tools can make it more difficult for someone to open new accounts in your name.
How to report identity theft to the FTC
The Federal Trade Commission allows identity theft victims to report the incident through IdentityTheft.gov at no cost. After answering a few questions, the website creates an FTC Identity Theft Report and provides a personalized recovery plan based on the situation.
Depending on the type of fraud, the recovery plan may recommend contacting financial institutions, disputing fraudulent accounts, placing a fraud alert or credit freeze, or reporting tax-related identity theft to the IRS.
Keep copies of any letters, emails, account statements, or case numbers related to the incident. Having well-documented and organized records can make it easier to resolve disputes with creditors or financial institutions.
How to protect your SSN or ITIN from identity theft
Protecting personal information starts with sharing it only when necessary. Before providing an SSN or ITIN, verify who is requesting it, why it is needed, and whether another form of identification can be accepted.
Avoid carrying documents that display an SSN or ITIN unless they are needed for a specific appointment. Store tax documents, identification numbers, and financial records in a secure location, and shred documents containing sensitive information before discarding them.
If you save your SSN or ITIN information digitally, try to use strong, unique passwords for your online accounts and enable two-factor authentication whenever it is available. Keeping devices updated with the latest security software may also reduce the risk of unauthorized access.
How to monitor your accounts for suspicious activity
Regular account monitoring is one of the most effective ways to detect identity theft early. Reviewing account activity, checking credit reports, and paying attention to unexpected notifications can help identify suspicious activity before it becomes a larger problem.
Transaction alerts can also make monitoring easier. Común's checking account includes instant transaction notifications, helping account holders to quickly identify purchases or transfers they do not recognize. The account also supports two-factor authentication.
If an unfamiliar transaction appears, it is important for you to review it as soon as possible and contact the financial institution if the activity cannot be verified. Responding promptly may reduce the impact of unauthorized transactions and help secure the account more quickly.
With Común, eligible customers can enable instant transaction alerts and two-factor authentication directly in the app. Monitoring your account activity regularly can help you spot unfamiliar transactions and respond quickly if something doesn't look right.
Eligible customers may be able to open a Común account using a valid passport, matrícula consular or more than 100 valid Latin American IDs. The account has no minimum balance requirements or monthly maintenance fees.
FAQ
How do I know if someone stole my identity?
Identity theft often becomes noticeable through unfamiliar charges, debt collection calls, accounts you never opened, or unexpected IRS notices. Checking your financial accounts and credit reports regularly can help you identify suspicious activity sooner.
What should I do first if my identity is stolen?
Start by reporting the incident at IdentityTheft.gov. The website creates an FTC Identity Theft Report and provides a personalized recovery plan. If financial accounts are affected, contact the companies involved as soon as possible.
Can someone steal my identity using my ITIN?
Yes. Although an ITIN cannot be used for every purpose that an SSN can, it may still be misused for tax-related fraud or other identity theft schemes. Protect your ITIN just as carefully as your SSN and only share it when necessary.
Is it free to report identity theft to the FTC?
Yes. Identity theft can be reported at IdentityTheft.gov at no cost. After submitting a report, the FTC provides recovery guidance and documentation that may help resolve fraudulent accounts and credit report issues.
How long does it take to fix identity theft damage?
Recovery time depends on the type of fraud and how quickly it is reported. Some issues can be resolved within weeks, while others, such as correcting credit reports or tax-related identity theft, may take longer. Acting promptly can help reduce delays.
Should I freeze my credit if my identity is stolen?
A credit freeze is one option the FTC recommends because it makes it more difficult for someone to open new credit accounts in your name. It is free to place and remove, and it does not affect existing financial accounts.
Común is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank, Member FDIC. The Común Visa® Debit Card is issued by Community Federal Savings Bank, pursuant to a license from Visa U.S.A. Inc. and may be used everywhere Visa Cards are accepted.
No minimum balance requirements or monthly maintenance fees. ATM or transfer fees may apply. See app for fee details.
Direct deposit funds are typically available when we receive the payment file, up to two days before the scheduled payment date. This early availability is not guaranteed.
Funds in your account are FDIC insured up to applicable limits by ownership category through Community Federal Savings Bank (CFSB), Member FDIC, in the event CFSB fails.
Instant payments
Learn how to use Cash App for your finances in the U.S.
8 min de lectura
The popularity of digital personal finance applications continues to grow among users in the United States. According to recent data, 8 out of 10 Americans have embraced the digital economy by using financial applications for purchases, digital payments, online banking, and more.
Cash App is one effective alternative to facilitate personal finance management. In 2024, it recorded 57 million monthly active users and $16.2 billion in earnings.
If you're curious to know what Cash App is, how it works, all its benefits, and its associated fees, below we provide all the details so you can decide whether it is the best option to meet your needs.
What Is Cash App and What Is It Used For?
Cash App is an alternative to traditional banking that operates through a mobile financial services application. Its functionality is highly versatile, as it not only allows users to send and receive money but also to make purchases and receive direct deposits from payroll.
The application was developed by Block Inc. (formerly Square Inc.) and aims to offer a comprehensive and more accessible service through digital solutions.
To open an account on Cash App, you must meet certain requirements, such as having a Social Security Number (SSN) and a U.S. bank account.
Cash App: How It Works, What Features It Offers, and What Fees It Charges
Cash App is available through its official mobile application, in which you must complete the registration and verification process to access all available features. Once completed, you may link a bank account if needed.
You will also have a Cash Tag: a unique username that allows you to send and receive money easily.
The following are the main features offered by the Cash App application:
Sending and Receiving Money
Cash App allows instant transfers between users of the application free of charge (free instant transfers; standard network fees may still apply).
Cash Card
This is a free debit card linked to your balance. It allows you to make online and in-store purchases and withdraw cash from ATMs.
QR Code
Pay directly in physical stores using a QR code.
Cash App Pay
A payment method that allows users to complete transactions in online stores and directly through the application.
Cash Boosts
You can obtain discounts at selected physical and online establishments.
Fees for Using Cash App
Although many of Cash App’s features are free, such as account maintenance, use of the Cash Card, and transfers between Cash App accounts. Below is a table with some of the main fees and charges associated with the aforementioned features:
| Service | Cost |
|---|---|
| Instant transfer to bank card | 0.5 % to 1.75 % |
| Standard transfer (1 to 3 days) | Free |
| ATM withdrawals | 2.50 USD per withdrawal |
Cash App registration requirements
If you want to use Cash App to control your finances, make sure you meet the following requirements:
Have a U.S. phone number
You can also use an email to verify your identity.
Reside in the United States or England
Cash App is only available in the United States and the United Kingdom. The application and information are available in English only.
Have a bank account
It is recommended if you want to have access to all the functions of the application.
Do the identity verification
This will allow you to access features such as sending or receiving more than 1,000 USD over 30 calendar days and applying for the Cash Card.
But remember that to perform identity verification you need:
- Full name
- Birthdate
- Social Security Number (SSN)
How secure is Cash App? : 9 important considerations
The issue of security is one of the most relevant in relation to financial services applications. You should always verify that your provider has the necessary measures in place to keep your assets and personal data safe.
For its part, Cash App has the following security measures, among others:
Multifactor authentication
Cash App requests identity authentication via email or SMS. In addition, it allows you to activate a PIN or biometry to log in.
End-to-end encryption
Your personal data stored in Cash App is secure through TLS/E2E.
System for the detection and prevention of illegal activities
Cash App has implemented technologies trained to detect unusual behavior and prevent fraud, such as machine learning and algorithms.
Subsequent payment monitoring
The application has an additional monitoring system to do a double check and detect unusual activities.
Although the above features offer some certainty regarding the application's security measures, it's always important to take into account some considerations:
Turn off automatic login
To prevent an outsider from accessing your account without your authorization, avoid using automatic login. Instead, use strong, unique passwords and enable 2-step authentication.
Beware of fraud
Stay alert to scams, either by phone or email. Never give out personal information or passwords through these means. If you need to contact application support, do so through official means.
Keep active alerts
Cash App allows you to receive alerts for your transactions directly on your cell phone. Make sure to keep them active.
Verify data before making transfers
Send money only to people you know and verify their information before confirming the operation, since once the money has been sent, it is not possible to recover it.
Activate the PIN to carry out transactions
You have the option of activating the PIN or biometric data to confirm your transfers before doing them, and avoid the use of your application by third parties in case of theft or loss.
Are you looking for more than just a payment app? Comun is your financial ally in the U.S. UU.
There is no doubt that Cash App is a popular alternative among those looking for a fairly comprehensive and easy-to-use financial solution.
But if you are looking for a financial ally that offers a simple and secure experience, with customer service and a platform also available in Spanish, we present Comun.
Comun goes beyond traditional limitations, so that immigrant communities in the United States have access to quality financial services, without complications. With Comun you can:
- Receive and send money conveniently, without complications and without the need for a traditional bank account.
- Open your Comun account with the qualified Official Identification of your country of origin.
- Get a simple mobile application for hassle-free daily international money transfers.
Open your Comun account today and breaks down the barriers of traditional financial services, language and cultural ones.
FAQs
If you still have questions about what Cash App is for and its features, check out our frequently asked questions.
What are Cash Boosts in Cash App?
These are instant discounts available on the Cash Card. To activate them, enter the mobile application and select “Cash Card”, followed by “Add Boost” and “Save Boost”. Select the discount you are interested in and it will be applied when you pay with your debit card.
What happens if I receive a lot of money through Cash App?
Some necessary checks may be activated starting at $1000.
How much is the maximum that can be sent via Cash App?
1000 USD over 30 calendar days for unverified users; if you verify your user, you can increase this limit to 20,000 USD.
What is Cashtag in the Cash App?
This is a unique username that is used so that other users of the application can send you money. It starts with the $ symbol followed by an identifier.







Thousands of immigrants are already achieving more with their money. You can too.
Comun is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank; Member FDIC. The Comun Visa® Debit Card is issued by Community Federal Savings Bank, pursuant to a license from Visa U.S.A Inc. and may be used everywhere Visa Cards are accepted.
Comun is a fintech company and not a bank or licensed money transmitter.
* Results may vary. For a complete list of eligible IDs and application requirements, follow this link.
^ No minimums, no maintenance fees. ATM or transfer fees may apply. See app for fee details.
‡ Direct deposit funds are typically available when we receive the payment file, up to two days before the scheduled payment date. This early availability is not guaranteed.
** A service provided by Service UniTeller, Inc. Service UniTeller, Inc. is licensed in all states that require a license. Remittance fees start at $2.99 but may vary. Please check the app for more details. Comun Inc. may earn revenue from the conversion of foreign currencies.
† Funds in your account are FDIC insured up to $250,000 by ownership category through Community Federal Savings Bank (CFSB), Member FDIC, in the event CFSB fails.


