
Financial Education
Wire Transfers, ACH, and Other Money-Transfer Methods
Open your bank account¹ in 3 minutes with your country ID²
8 min read

05 May 2024

ACH transfers are electronic bank transfers within the U.S., commonly used for payroll deposits and payments between accounts. With Común, receiving an ACH transfer is at no cost, and it usually takes 3–5 business days.
The ability to transfer money efficiently and securely is a cornerstone of economic interactions. This article explores the range of electronic transfer methods available today, comparing and contrasting wire transfers, Automated Clearing House (ACH) transfers, and other prevalent money-transfer mechanisms. By understanding the nuances of each international transfer method, from international money transfers to peer-to-peer platforms, individuals and businesses can navigate the complexities of financial transactions with confidence.
Wire Transfers: Speed and International Reach
Wire transfers stand out as a testament to the enduring value of fast, secure international money movement. Valued for their reliability, wire transfers allow individuals and businesses to transfer funds directly between bank accounts across the globe. The defining feature of wire transfers is their rapid processing, crucial for time-sensitive transactions. They leverage the vast international network of a financial institution, making it possible to send money to almost any country.
However, the efficiency and security of wire transfers come at a cost. They are generally associated with higher fees compared with other transfer methods, both for the sender and, occasionally, the recipient. These transactions also require the provision of precise and complete recipient bank details, including the bank name, account number, and routing numbers, ensuring that funds reach the intended destination without delays.
Despite the cost, the unmatched speed and security of wire transfers make them the preferred choice for large international transactions, where the assurance of timely and safe delivery outweighs the expense. Whether for business dealings, purchasing property abroad, or sending emergency funds, wire transfers offer a reliable solution, backed by the reputation and regulatory framework of traditional financial institutions.
ACH Transfers: Domestic Efficiency and Low Cost
The Automated Clearing House (ACH) network offers an efficient and economical alternative for domestic money transfers. ACH transfers encompass both direct deposits and direct payments, including payroll, government benefits, and bill payments. Unlike wire transfers, ACH transfers are processed in batches, which can lead to slower delivery speed, typically a few business days. However, the lower fees associated with ACH transfers make them an attractive option for routine domestic transactions. ACH transfers and wire transfers, while often mentioned together, serve distinct needs based on the urgency and geographic scope of the transaction.
The versatility of the ACH network extends beyond simple cost savings, providing a framework for a wide range of transactions beyond conventional check deposits and bill payments. This includes, but is not limited to, person-to-person (P2P) payments, business-to-business transactions, and even government-to-citizen payments such as tax refunds.
In addition, the arrival of same-day ACH processing marks a significant improvement in transaction speed, addressing one of the few drawbacks traditionally associated with remittance transfers through this method. Despite this advancement, the inherent delay in batch processing still makes ACH transfers less suitable for urgent transactions, positioning them as a preferred method for planned recurring payments where cost efficiency outweighs immediate fund availability.
The Rise of Digital Convenience:
Two methods stand out for their distinct approaches and unique benefits: person-to-person (P2P) transfers and traditional transactions at both banks and credit unions, and banks. P2P platforms like PayPal, Venmo, Cash App, and Google Pay have revolutionized the way we think about money transfers, offering a level of convenience and accessibility that aligns with the demands of the digital age. These platforms cater to a generation that values speed, simplicity, and the ability to transact on the go using only a smartphone. On the other hand, credit unions and banks represent the backbone of traditional financial transactions, providing a full suite of services ranging from everyday banking needs to complex international wire transfers.
Person-to-Person Transfers
As mentioned, platforms like PayPal, Venmo, Cash App, and Google Pay have become indispensable in the digital era, democratizing the process of sending and receiving money. These apps excel in user convenience, enabling transactions with just a smartphone. Linked to one’s bank account or debit card, they facilitate both domestic and, increasingly, international transfers.
While often free for basic services, they may charge small fees for instant transfers or currency exchange-rate conversion. The appeal of P2P platforms lies in their simplicity and the ability to transfer funds without needing the recipient’s banking details, only their phone number or email address.
Credit Unions and Banks: Traditional but Reliable
Credit unions and banks remain the backbone of the money-transfer ecosystem. Offering a range of services from direct deposits to international wire transfers, these institutions provide a secure, if sometimes more expensive, way to move funds. The choice between a bank and a credit union often comes down to the nature of the transaction—credit unions may offer lower fees and better exchange rates for their members, while banks might provide more comprehensive services for international and business transfers. Regardless of the choice, ensuring the transaction is completed with a reputable institution is paramount.
Deciding Between Money-Transfer Apps: Key Considerations
When comparing money transfer apps, several key factors should be considered to ensure the decision aligns with your personal or business financial needs. Here are the essential aspects to evaluate:
- Fees: Compare the associated costs for sending or receiving money, including fees for instant transfers or foreign-currency conversion charges.
- Transfer Limits: Check the maximum and minimum amounts you can send, as platforms vary widely in their limits.
- Geographic Availability: Not all apps are available in every country or support international transfers. Make sure the app meets your geographic requirements.
- Security: Investigate the security measures in place, such as encryption and fraud protection, to safeguard your financial information.
- User Experience: Consider the app’s ease of use, customer support availability, and any additional features such as bill splitting or social functionality.
- Delivery Speed: While some apps offer instant transfers, others may take a few business days. Choose based on how quickly you need the funds to be available.
- Exchange Rates and Currency Options: For international transfers, evaluate the exchange rates offered and which currencies are supported.
Común- Banking designed for your life in the U.S.
Open your bank account¹ in 3 minutes with your country ID²
By carefully considering these factors, users can select a money transfer app that best suits their financial transactions, balancing convenience, cost, and security. Whether sending money to a friend domestically or managing international business transactions, the right money transfer app can make all the difference in achieving a smooth and efficient money-transfer experience.
Emerging Technologies and Financial Innovations
The financial sector continues to evolve, with emerging technologies and innovations offering new ways to transfer money. Blockchain technology, for example, has given rise to cryptocurrencies, which promise faster international transfers without the need for traditional banking infrastructure. However, these methods come with their own set of challenges, including volatility and regulatory uncertainty. As these technologies develop, they may offer viable alternatives to traditional and electronic fund-transfer methods. Some developments include:
- Decentralized Finance (DeFi) Platforms: These platforms are reshaping financial transactions by enabling peer-to-peer lending, borrowing, and investing without traditional intermediaries, using blockchain technology to ensure security and transparency.
- Smart Contracts: These self-executing contracts with the terms of the agreement directly written into code can automate and secure the execution of financial transactions, reducing the need for intermediaries and increasing efficiency and trust.
- Digital Wallet and Mobile Payment Integration: Integrating digital wallets with mobile payment systems is streamlining the process of making transactions, making them more seamless and accessible, and is poised to reduce reliance on physical bank cards and cash even further.
Conclusion
The world of money-transfer methods is diverse, each with its own set of advantages, disadvantages, and best-use scenarios. From the rapid international reach of wire transfers to the domestic efficiency of ACH transactions and the convenience of money transfer apps, the choice of method depends on the specific needs of the transaction, including speed, cost, and geographic reach. As financial technologies continue to evolve, staying informed about these methods will enable individuals and businesses to make the best decisions for their money-transfer needs, ensuring that funds are transferred securely, efficiently, and cost-effectively.
What is an ACH transfer?
It's a type of electronic transfer that moves money between U.S. bank accounts, commonly used for payroll, bill payments, and transfers between banks.
How do I receive an ACH transfer into my Común account?
Use your account and routing number, found inside the app, to receive ACH transfers directly into your account. It's at no cost.
How long does an ACH transfer take?
Generally 3–5 business days. If you need your paycheck faster, direct deposit has no limit and is usually available sooner.
Frequently asked questions
Does receiving an ACH transfer in Común cost anything?
No, receiving ACH transfers into your Común account is at no cost.
What's the ACH transfer limit with Común?
Up to $1,000 per day and $10,000 per month.
Where do I find my account and routing number to receive an ACH transfer?
Both are available inside the Común app.
Is direct deposit faster than an ACH transfer?
Yes, direct deposit has no limit and is usually available faster than a standard ACH transfer.
Can I send money via ACH from my Común account to another bank?
The app shows you the transfer options available based on your account type.
What's the difference between ACH and a wire transfer?
ACH is usually free but slower (3–5 days); a wire transfer is generally faster but may have a fee.
About Común
Común aims to support the Latino community in the United States. It offers a debit account that can be opened with more than 100 valid Latin American IDs and an app available in Spanish.
Visit Común's website or download the app for free to learn more about the full offer and applicable terms.
Olivia Rhye
Community Partner

Financial Education
Discovering Types of Bank Accounts: A Guide
8 min de lectura
A checking account is what you use for everyday spending: getting paid, paying bills, and using your debit card. With Común you can open one without a Social Security Number, with no opening fee and no monthly fee.
In the world of finance, choosing the right bank account can make a big difference in your financial life. In this article, we'll walk you through the different types of bank accounts available in the United States and help you choose the best option for your needs.
What Is a Bank Account and Why Does It Matter?
A bank account is a type of financial product that acts as a financial agreement between a bank and a customer, letting the customer deposit and withdraw money. It also offers additional services like issuing checks, bank transfers, debit card payments, receiving direct deposits, and more. Choosing the right bank account is essential for managing your finances efficiently and reaching your financial goals.
Different Types of Bank Accounts
There are several types of bank accounts, each with its own features, advantages, and disadvantages. Below, we'll explore two of the most common: savings accounts and checking accounts:
Checking Accounts
A checking account, also known as a checking or checkbook account, is a type of bank account used mainly for everyday transactions. Unlike savings accounts, checking accounts let you make an unlimited number of deposits and withdrawals, making them ideal for handling your money day to day.
Checking accounts are offered by nearly every bank and credit union in the United States, and each has its own features and benefits. One of the main advantages of checking accounts is their flexibility. You can deposit and withdraw money as many times as you want, and you can also complete basic transactions like paying bills, writing checks, and making purchases with a debit card. Plus, many checking accounts offer additional services like overdraft protection, account alerts, and access to online and mobile banking.
However, unlike savings accounts, checking accounts usually have lower — or even no — interest rates, meaning your money won't grow over time. Additionally, some checking accounts may carry monthly service fees, though you can often avoid these fees if you meet certain requirements, like maintaining a minimum balance or completing a set number of transactions each month.
For example, Chase Bank offers the Chase Total Checking account, and Citi Bank offers the Citi Basic Banking Package, which include access to thousands of ATMs and online and mobile banking service. However, like many other traditional banks, they charge a monthly service fee of $8 to $12 unless you meet certain average monthly balance requirements or a minimum amount deposited through monthly direct deposits.
By contrast, Común, online banking in the United States, offers a checking account with zero hidden costs. Unlike traditional banks, the bank account Común offers requires a $0 minimum deposit, requires $0 in monthly fees, unlimited transactions, and many more great benefits.
In summary, while checking accounts may not be the best option for saving money, they're an essential tool for managing your finances day to day. When choosing a checking account, it's important to consider your banking habits and look for an account that fits your needs.
Savings Accounts
A savings account is a type of bank account specifically designed to encourage the savings habit among users. Its main purpose is to help you keep money safe while earning interest on your balance.
Savings accounts are offered by most banks and credit unions in the United States, and each has its own features and benefits. For example, Bank of America offers the Advantage Savings account, which includes a competitive interest rate and the ability to avoid the monthly maintenance fee if you meet certain requirements. Wells Fargo, on the other hand, offers the Way2Save Savings account, which makes saving easier by automatically transferring $1 from your checking account to your savings account every time you make a transaction.
One of the main advantages of savings accounts is that your money isn't just safe — it also grows over time thanks to interest rates. These rates vary depending on the bank and the type of account, but generally let you earn a small percentage of your total balance each year. Additionally, savings accounts are insured by the Federal Deposit Insurance Corporation (FDIC) up to $250,000, meaning your money is protected even if the bank fails.
However, savings accounts also have some limitations. One of the most notable is a restriction on the number of certain types of transactions you can make each month. Under the Federal Reserve's Regulation D, you can only make up to six "convenient transactions" per month, which include transfers and electronic payments, automatic debits, checks, and debit card payments. If you exceed this limit, the bank may charge you a fee or convert your savings account into a checking account.
Also, while savings accounts are a great way to store money, they aren't the best option if you need frequent access to your funds. For everyday transactions and easy access to your money, a checking account might be more suitable.
Specialized Bank Accounts
Beyond savings and checking accounts, there are other types of bank accounts designed for specific needs.
Low-Fee Accounts and Second-Chance Accounts
Low-fee accounts are bank accounts that offer basic services at a minimal cost, ideal for people looking to avoid high banking fees. Second-chance accounts, on the other hand, are designed for people who've had trouble with bank accounts in the past and are looking for a new chance to manage their finances.
Payroll Accounts and Money Market Accounts
Payroll accounts are bank accounts where your employer deposits your salary directly, while money market accounts are savings accounts with investment features that offer competitive interest rates in exchange for maintaining a higher minimum balance.
How to Choose the Best Bank Account for Your Needs
Choosing the right bank account largely depends on your financial needs and goals. For example, if your goal is to save money, a savings account might be the best option. On the other hand, if you need to make a lot of daily transactions, a checking account might be more suitable.
Factors to Consider When Choosing a Bank Account
Some factors to consider when choosing a bank account include interest rates, bank fees, minimum balance requirements, additional services and features, and the bank's reputation.
How to Open an Account With Común:
To open an account in the United States, you'll generally need to provide personal information, like your name, address, date of birth, and Social Security number. You may also need to provide a government-issued photo ID and make an initial deposit.
At Común, the steps and requirements to open an account are as follows:
- Download the mobile app on your Apple device from the App Store or your Android device from the Play Store.
- Open the app and create your new account; follow the instructions and fill in your personal information.
- In under 5 minutes, you'll have finished creating your account and will get an account number and routing number, and you can start using your virtual debit card right away.
- Request your debit card, and it will arrive by mail in under 2 weeks.
We recommend making your first deposit when you open your Común account so you can start using your debit card. You can do this in a few different ways:
- Connect your PayPal, Cash App, and other accounts to your Común account and transfer money to yourself instantly.
- Deposit cash at one of the thousands of ATMs in the Allpoint network, which you can find at any Walgreens, CVS, Target, and many other locations near you.
- Transfer money from your other bank accounts using your Común account and routing numbers; keep in mind this type of transaction may incur costs from the bank you're transferring from.
The Importance of Choosing the Right Bank Account
Choosing the right bank account is a crucial step in managing your finances efficiently. We hope this guide has helped you better understand the different types of bank accounts available and make an informed decision. Remember, the best bank account for you is the one that fits your needs and financial goals.
If you're looking to open a checking account and get a debit card, what are you waiting for? Do it with Común.
What types of bank accounts are there?
Mainly checking accounts (for everyday use) and savings accounts (for storing money, sometimes with interest). Común offers a checking account designed for immigrants.
What do I need to open a bank account in the United States?
Generally a government-issued ID and proof of address. With Común, we accept a passport, consular ID, or other Latin American IDs, with no Social Security Number required.
How much does it cost to maintain a bank account?
It varies by institution. Común doesn't charge a monthly fee or require a minimum balance.
Frequently asked questions
What's the difference between a checking and a savings account?
A checking account is for everyday spending and frequent transactions; a savings account is meant for storing money, sometimes with interest.
Can I open a bank account without a Social Security Number?
Yes, with Común you can open an account using a passport, consular ID, or other valid Latin American ID.
Do digital banks charge less than traditional ones?
Many digital platforms, like Común, don't charge a monthly fee or require a minimum balance, unlike some traditional banks.
What documents does Común ask for to open an account?
A valid government-issued photo ID; proof of address may be requested in some cases.
How long does it take to open a bank account?
With Común, about 3 minutes, entirely from your phone.
Do I need to visit a branch to open my account?
No, the entire process happens online through the app, with no branch visit required.
Community
Común: Digital Banking for Immigrants in the U.S.
8 min de lectura
Común is a digital financial platform designed specifically for the immigrant community in the United States, letting you open an account with Latin American IDs, no Social Security Number required.
Común does not have branches, but it has a team that supports its customers 24 hours a day, 7 days a week, from the comfort of their homes, in three different languages.
Building a better future for immigrants in the U.S. is a core principle of Común’s mission. Accessible and easy-to-understand banking options are a key part of the immigrant journey. However, the options are scarce.
Complex, cumbersome, and expensive options are the norm. Activities that may seem trivial and intuitive to those born in the U.S. are overwhelming and confusing for a newly arrived immigrant. Everything from setting up direct deposit with an employer to sending money home, making payments for goods and services, or understanding how to build a credit score seems too complex for anyone who has never had to do this in the U.S., let alone at all.
Hidden fees and costly charges add another layer of stress when starting a financial life in the U.S. Between minimum account balances, monthly fees, overdraft charges, large check deposit fees, extortionate international transfer fees, and everything else, maintaining and using a bank account in the U.S. can be expensive. For manual laborers, this can represent a significant percentage of their wages.
The physical locations of traditional banks can also be scarce in some areas. Since opening a bank account or depositing a check or cash into the account must be done at a branch, this is a significant burden for someone living in a remote area. Many immigrants, sometimes working on remote farms or factories, live miles away from the nearest bank branch. Transportation costs to those branches add to the already high fees of using and maintaining an account.
Even if the banking services provided were more intuitive, digital, and lower cost, another major barrier remains. Obtaining the necessary documentation to open a bank account can also make access to fair and simple financial services difficult. Immigrants fortunate enough to have work authorization still need to gather important documentation that is not always available to them. For those who have come to the U.S. seeking asylum or better work opportunities through a more unconventional path, the documents required to open an account are often prohibitive.
Building a 100% digital banking platform to solve the issues mentioned above is part of what Común seeks to achieve because we believe in helping unlock social mobility. But a digital, low-cost, and intuitive platform is not enough. To navigate this process, immigrants need help, and help is best found in a Community that understands them when they need it most.
That is why not only our customers are part of our Community, but also the people who help them 24 hours a day, 7 days a week through our app, social media, WhatsApp, or by phone. Beyond solving an immediate problem, the support provided goes further. It teaches and educates, empathizes, and strives to foster a sense of Community among people who understand them, in terms they comprehend and in the language they speak. This is the core of true digital community banking. Our team helps them set up direct deposit, get refunds for charges they disagree with, and everything else.
At Común, the first step in this journey has already begun. Our team in Mérida, Mexico, is part of our Community and the one we seek to serve. They are an extension of our mission and our digital platform, and a necessary ingredient in unlocking social mobility for millions of immigrants in the U.S.
What makes Común different from a traditional bank?
Común accepts over 100 Latin American IDs (passport, consular ID, among others), doesn't require an SSN or ITIN, and doesn't charge a monthly fee or require a minimum balance.
How does Común specifically support the immigrant community?
With 100% Spanish-language support, an account opening process that takes minutes, and features built for common community needs, like low-cost remittances and cash deposit without needing a prior bank account.
What services does Común offer?
A checking account with a Visa debit card, international remittances starting at $2.99, cash deposit at over 88,000 locations, and direct deposit.
Frequently asked questions
Who is Común designed for?
For the Latin American immigrant community in the U.S. looking for accessible financial services without traditional documentation barriers.
What IDs does Común accept?
Over 100 Latin American IDs, including passports and consular IDs — no SSN or ITIN required.
Does Común charge an opening or maintenance fee?
No, there's no opening fee, monthly fee, or minimum balance required.
Is Común's support available in Spanish?
Yes, the app and customer support are available in Spanish.
How fast can I open my account?
The process takes about 3 minutes, with instant approval in most cases.
Does Común offer remittances to Latin America?
Yes, starting at $2.99 per transfer, with your first transfer at no cost.
Financial Education
How to fill out a check in the United States in 5 simple steps (+ Example)
8 min de lectura
Have you ever filled out a check? Although most transactions today are digital, knowing how to fill out a check is essential—especially if you are just beginning your financial life.
According to recent data, one-third of Americans paid by check in 2024, demonstrating that checks still play an important role in the U.S. economy.
You might consider checks an outdated payment method; the reality is that they are useful in specific situations. For that reason, we will explain what a check is, the different types of checks, and how to complete them properly.
What Is a Check and What Is It Used For?
Despite the digital era, checks remain a relevant traditional payment method due to their formality and traceability. They are used for rent payments, purchases, and service payments.
Additionally, checks are a common payment method among the immigrant community, who often use them while adapting to the U.S. banking system.
But what exactly is a check and what are its characteristics? It is a physical document issued by an individual or business (the drawer) to order a bank to pay a specified amount to a third party. For the payment to be processed, the drawer must have sufficient funds in their checking account.
In general, a check contains the following information:
- Name of the drawer, whether an individual or a business
- Name of the payee
- Financial institution where the money will be drawn
- Amount to be paid, both in numbers and in words
- Signatures of the drawer
What Are the Different Types of Checks?
There are different types of checks in the United States. In this case, we will focus on the personal check, although you may choose the option that best suits your needs.
Personal Check
A personal check is a payment order issued by an individual to another individual using the funds in a checking account.
What Is a Personal Check Used For?
The most common uses for personal checks include:
- Rent and utility payments
- Purchase of everyday goods
- Legal agreements requiring documentary support
Certified Check
A certified check serves the same purpose as a personal check but is reviewed and guaranteed by the issuing bank, which verifies that the drawer has sufficient funds and holds them until the check is cashed.
A certified check provides certainty of available funds, making it a more secure method for making and receiving payments.
Cashier’s Check
Unlike a personal check, a cashier’s check is issued directly by the bank, offering greater security for the payee, as the bank is responsible for issuing and safeguarding the funds.
To obtain a cashier’s check, the drawer must visit a bank branch and pay the amount to be transferred. The bank then issues the check in the name of the payee, guaranteeing that it can be cashed using the institution’s own funds and not a personal account.
It is commonly used for high-value purchases such as homes and vehicles.
Money Order
While not strictly a check, it is a traditional payment method with similar functionality.
A money order is a financial instrument that allows funds to be sent via traditional mail using a certified check, which must be purchased and paid for by the drawer at an authorized location.
It allows secure money transfers without requiring a bank account.
How to Fill Out a Check in the U.S.
Before issuing this type of payment order, you must know how to do it properly. Below is an example of how to fill out a check easily, starting from step one:
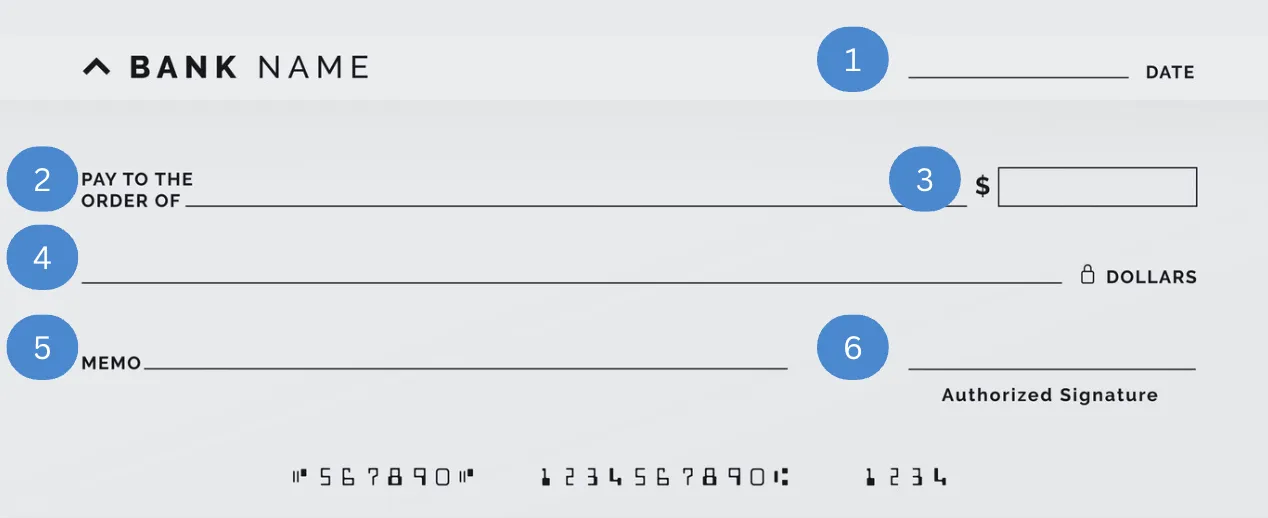
1. Write the Date
Remember that in the United States, the date format is mm/dd/yyyy.
2. Payee’s Name
Write the full name of the person to whom you are issuing the check, exactly as it appears on their official identification.
3. Amount in Numbers
Write the numerical amount clearly.
4. Amount in Words
Write the amount in words, including cents.
5. Add a Memo
You may include a note specifying the reason for the payment.
6. Sign the Check
Sign the check legibly in the space designated for the drawer.
7. Review the Information
Ensure that all information is accurate to avoid issues for the payee when cashing the check.
It is essential to complete checks legibly, without strike-throughs or corrections, as these may invalidate the document.
How to Correctly Write Numbers in Words on a Check
Writing amounts in words may be confusing when dealing with U.S. dollars. The following points should be kept in mind:
- Dollar amounts must be written in full words
- Cents must be written as fractions
- Avoid using dollar symbols or similar notations
- If there is leftover space at the end of the line, draw a line to prevent fraud
- For example, $1,000.75 is written as: One thousand and 75/100 dollars
Cash Checks and Manage Your Money Easily with Comun
As you can see, knowing how to fill out a check is useful for sending and receiving money in the United States. It is a reliable and accessible alternative if you do not have a banking account.
However, issuing and cashing a check can also require significant time and effort. That’s why you can skip the trip to the bank, avoid wasting time or money on gas, and cash your check directly from your phone using Comun—no lines, no questions, no complications.
Discover Comun, the only platform designed to serve the needs of immigrant communities in the United States, with support available in Spanish.
Why Choose Comun?
- Open your account with an official ID from your country
- Access a mobile app specifically designed for immigrants in the U.S.
- Make payments, receive your salary, and manage your finances
- Send money to your loved ones in LATAM for just a $2.99 transfer fee
Frequently Asked Questions
Still have questions about how to fill out a personal check? See our FAQ section.
What if I Make a Mistake Filling Out a Check?
If there are strike-throughs or inconsistencies in the amounts, the check must be voided and a new one used.
How Do I Void a Check?
Write the word VOID in large letters on the front of the check.
What Information Appears on the Back of a Check?
The back of the check contains the endorsement, meaning the payee’s signature for cashing the check.
Immigration
Bank Fees for Immigrants: Common vs. Competitors
8 min de lectura
For immigrants in the U.S., bank fees can amount to hundreds of dollars a year. Común stands out by offering a monthly-fee-free account, no minimum balance, and no SSN requirement. Compared with competitors like Seis and Majority, Común eliminates fixed fees while still providing full services in Spanish.
Choosing the right bank account can save you hundreds of dollars a year. For the immigrant community in the U.S., comparing fees is especially important because many traditional accounts charge fees that directly affect the monthly budget. We analyzed the main options available.
Fees at Traditional Banks
Major U.S. banks such as Bank of America, Chase, and Wells Fargo charge between $6 and $25 per month to maintain a checking account, with minimum balance requirements of $1,500 to $25,000 to avoid those fees. They also charge overdraft fees ($35 per transaction), out-of-network ATM withdrawal fees ($2.50-$5 per withdrawal), and international transfer fees ($25-$45 per wire transfer). For a newly arrived immigrant without credit history or a high balance, these costs add up quickly.
Común: No-Fee Account for Immigrants
Común offers a checking account with no monthly fee, no minimum balance required, and no overdraft penalty in many cases. It does not require an SSN — it accepts a passport, consular ID, and more than 100 Latin American IDs. Customer service is completely in Spanish. Account opening takes minutes from a mobile phone. It allows instant domestic transfers at no cost between Común users. It is the option designed specifically for the Latino community in the U.S.
Majority: Monthly Membership with International Benefits
Majority charges $5.99 per month as a base membership (down from $14.99). In return, it offers unlimited international calls to selected countries, roaming mobile data in more than 50 countries, and discounts at participating merchants. If you actively use international calling and travel benefits, the membership may be worth it. However, if you only need a basic bank account, you are paying for services you may not use.
Seis: Account for Visa Workers
Seis is designed for expats and visa workers in the U.S. It offers an account without an SSN using a visa and passport. Fees vary by plan: the basic account has limits on the number of free transactions. It is more geared toward professionals with work visas (H-1B, L-1) than the immigrant community at large. Its interface is available in multiple languages, including Spanish.
Direct Fee Comparison
In terms of monthly fee, Común charges $0, Majority charges $5.99/month, and traditional banks charge between $6 and $25. The minimum balance requirement is $0 at Común, $0 at Majority, and between $1,500 and $25,000 at traditional banks. Regarding SSN requirement, Común does not require it, Majority does not either, while traditional banks generally do. All three have FDIC or equivalent deposit protection.
Which Option Is Best for You?
If you are looking for the account with the lowest total fees and do not need unlimited international calls, Común is the most economical option. If you travel frequently or call abroad often, Majority’s membership may be worth it. Traditional banks only make sense if you already have the required minimum balance or if you need specific services such as mortgages or investment accounts.
Frequently Asked Questions About Bank Fees
What bank fees are most common in the U.S.?
The most common are: monthly maintenance fee ($6-$25), overdraft fee ($35 per transaction), out-of-network ATM fee ($2.50-$5), and international wire transfer fees ($25-$45). Digital banks like Común eliminate most of these fees.
Can I avoid bank fees at a traditional bank?
Yes, usually by maintaining a monthly minimum balance (which varies by bank and account type), receiving direct payroll deposit, or being a student. However, for immigrants without credit history or with variable income, meeting these requirements can be difficult at first.
Are ATM fees unavoidable?
No. Multiple digital banks offer free access to ATM networks (Allpoint, MoneyPass) with thousands of fee-free locations across the U.S. Común provides access to fee-free ATMs within its network. Outside the network, typical charges are $2.50-$5 from the ATM plus whatever your bank charges.
What is an overdraft fee and how can I avoid it?
An overdraft fee occurs when you spend more money than you have in your account and the bank covers the difference by charging you a penalty (typically $35). You can avoid it by activating low-balance alerts, linking a savings account as backup, or choosing a bank that does not charge overdraft fees — some digital accounts decline the transaction instead of charging a penalty.
Is it worth paying a monthly membership for a bank account?
It depends on the included benefits. A $5.99-$14.99 monthly membership may be worth it if it includes services you actively use (international calling, travel insurance, cashback). If you only need an account for deposits, payments, and transfers, a free account like Común is more cost-effective.
Financial Education
Emergency Fund: Guide to Build It and Save in the U.S.
8 min de lectura
How to create an emergency fund and save in the U.S., step by step
If you’re new to the United States or facing financial challenges, it’s very important to have strategies to prepare for any eventuality.
An emergency fund is an excellent way to do this, and it also builds your financial literacy. It’s a cash reserve meant to cover unexpected expenses such as illness, job loss, home repairs, etc.
Having this cushion gives you peace of mind and removes uncertainty about the future, since it provides the liquidity you need to handle the unexpected.
You might think you need to earn a lot to build an emergency fund. Below, we’ll show that even with limited resources, you can start securing a future without financial complications.
What is an emergency fund and why is it key to your financial peace of mind?
Surely at some point during your time in the U.S., you’ve faced financial emergencies that made it hard to cover daily expenses—traffic fines, immigration procedures, illnesses, unemployment, repairs, etc.
An emergency fund is meant to support your finances precisely when those events occur. It’s savings set aside to handle all kinds of unforeseen expenses.
Beyond a stash of money, think of the emergency fund as a way to maintain peace of mind and reduce stress; it helps you preserve financial stability and avoid going into debt.
How much should you save in your emergency fund?
Knowing how to size an emergency fund is the first dilemma for many who aren’t used to long-term saving. While the ideal target is 3–6 months of basic expenses, if your income is limited you can start with small savings goals.
Below is a comparison of how your emergency fund would grow assuming expenses equal to 50% of total monthly income.
Monthly income
Approx. monthly expenses
3-month savings target
6-month savings target
$1,500
$750
$2,250
$4,500
$2,500
$1,250
$3,750
$7,500
$3,500
$1,750
$5,250
$10,500
Where should you keep your emergency fund so it’s safe and accessible?
It’s very important to choose a safe, easy-access place for your emergency fund and keep it separate from the money you use for daily expenses.
Today there’s a wide variety of savings accounts, both from traditional financial institutions and online platforms.
Whatever you choose, the following options are not recommended for storing your emergency fund.
- Cash at home
Whether under the mattress or in a piggy bank, keeping your emergency fund in cash is not a good idea for several reasons. First, there’s the risk of theft or loss. Also, the cash earns no interest and loses value to inflation. Another drawback is low accessibility if you need to cover expenses digitally.
While it’s true that opening a checking account can be challenging for immigrants in the U.S., there are accessible options so you don’t have to keep the emergency fund in cash.
- In high-risk investments
Although investments have advantages, high-risk ones involve sharp fluctuations that could cause losses. They also often require locking funds for a long period.
Simple strategies to build your emergency fund
If you’re new to personal finance, the first thing to know is that an emergency fund isn’t just for high earners. The key is to examine your lifestyle and spend according to a savings plan.
Step 1. Calculate your basic monthly expenses
The first step is to list all your fixed monthly expenses and the amount for each.
Example:
- Rent: $1,300
- Transportation (public or private): $100
- Tuition: $200
- Subscriptions: $50
Then list your variable expenses and calculate a budget. To be more accurate, track all your spending by category.
Example:
- Food: $300
- Leisure: $200
Finally, total your monthly spending. In the example above, monthly expenses add up to $2,100.
Step 2. Set your first goal
At first, reaching 3–6 months of expenses can sound impossible. You don’t have to give up what you enjoy—start with a small amount each month and increase gradually.
Your first savings target depends on your income, your expenses, and the resulting capacity to save.
Step 3. Adjust your budget and allocate a fixed percentage to savings
After doing the math, add “savings” as a fixed expense so you set that money aside every month.
Step 4. Automate with scheduled transfers
Ideally, open a new account so your emergency fund doesn’t mix with daily-use money.
An easy way to fund it is with automatic transfers so you don’t have to remember to move money each time.
Step 5. Review and raise your goal until you reach 3–6 months of expenses.
After a few months of hitting a small goal, reassess your budget and consider increasing your savings as you’re able.
Organize and protect your money with Común
As you can see, an emergency fund provides financial security for unexpected events. It’s also easy to start with small goals and increase gradually until you reach financial peace of mind.
The next step is choosing a safe place to keep your emergency fund secure.
Meet Común, the financial platform dedicated to making life easier for immigrants in the United States!
- Open your checking account at Común with a qualifying official ID from your country of origin.
- Send money to your family with clear, competitive fees.
Común is a financial platform designed to support your first steps toward financial stability in the U.S.
Open your account with Común today and start your emergency fund with a financial ally that truly understands you.
Frequently Asked Questions (FAQ)
If you still have questions, check this section.
Is it better to save for the emergency fund or pay debts first?
Having debts doesn’t prevent you from starting an emergency fund. Just include debt payments among your fixed monthly expenses and set your savings goal accordingly.
What happens if I use the fund and end up with no savings?
If you use your emergency fund for unexpected expenses, that’s fine—that’s its purpose. If you run it down, don’t worry; just start again based on your budget.
When should I use my emergency fund?
Your emergency fund is intended to cover unexpected events like medical bills, appliance breakdowns, layoffs, etc. When that happens, use it—and keep saving afterward.
Immigration
How to Create a Resume in the United States: Step-by-Step + Template
8 min de lectura
Practical Guide + Template to Create Your Resume in the United States
Getting a stable and well-paid job is the main goal of thousands of immigrants who come to the United States in search of a better quality of life.
For this reason, it’s essential to have an optimized resume (“CV”) that summarizes personal information, work experience, academic background, and all relevant details for recruiters and hiring managers.
You’ve probably faced the challenge of writing and refining a CV to apply for a job in your home country.
However, knowing the standards in Latin America is not enough, as U.S. resumes have key differences, such as length and focus on measurable results.
Mastering a new resume format can be challenging, and the process can be frustrating if you don’t hear back after sending multiple applications.
This doesn’t necessarily mean you lack the required skills — your resume might simply need some adjustments to get noticed by U.S. recruiters.
In this article, we aim to make the process easier for immigrant job seekers through a complete guide and sample resumes that will help you create your own by the end of the reading.
Differences Between a U.S. Resume and a Latin American CV
Even if you know how to write a resume in Latin America, it’s essential to understand the key differences compared to the U.S. standard.
Here are the main differences between a professional CV in Latin America and a U.S. resume.
- Length
In Latin America, it’s common to see two-page CVs, while the American resume is usually limited to one page.
- Focus on Quantifiable Achievements
U.S. recruiters look for quantifiable data and measurable results, while in Latin America it’s more common to include task descriptions and responsibilities.
- No Photo, Age, or Marital Status
To prevent discrimination, U.S. resumes do not typically include a photo, age, or nationality.
- Use of Keywords to Pass ATS Filters
The use of ATS (Applicant Tracking Systems) to detect keywords is widespread among U.S. companies.
- Format
While Latin American CVs often use colorful or elaborate designs, U.S. recruiters prefer minimalist formats to make information easier to read.
Understanding these differences is crucial for immigrants, as it increases the chances of being considered by both recruiters and automated systems.
7 Steps to Create a Resume in the United States
Here’s a step-by-step guide to writing a strong U.S. resume that passes ATS filters and captures recruiters’ attention.
Step 1. Choose the Right Format
Avoid flashy designs, as they can make reading difficult and hurt your ATS score. Choose a clean, organized, and easy-to-scan format.
Step 2. Fill in Your Contact Information
Include your full name, U.S. phone number, professional email address, and LinkedIn profile link.
Remember that you do not need to include a photo, date of birth, or marital status.
Step 3. Write Your Professional Summary
Your profile should be concise and include relevant keywords. This section should be a short paragraph summarizing your work history, interests, achievements, and career goals.
Step 4. Clearly Present Your Work Experience
It’s essential to list your work experience clearly and in chronological order.
- Use bullet points to list your most recent positions, including company name, job title, start and end dates.
- Highlight measurable achievements in each position.
To write your professional achievements, use the XYZ formula, structured as follows:
- X: what you did
- Y: how you did it
- Z: the result achieved.
For example:
“Improved the brand’s visual identity through an e-commerce rebranding project, reducing cart abandonment by 50%.”
Step 5. Your Education
List your academic background, including institution name, degree, and attendance dates.
Step 6. Highlight Your Skills
The skills section is key to making your resume stand out.
It’s recommended to separate this section into soft skills and technical skills.
- Soft skills: communication, teamwork, time management, attention to detail.
- Technical skills: design and editing software.
Step 7. Optional Sections
Depending on the vacancy and your profile, you can include additional sections, such as languages, certifications, or volunteer experience.
This information can set you apart from other candidates, as it gives you additional skills that could be relevant to the position.
Example of a U.S. Resume
Here’s an example of how an optimized resume should look, according to U.S. company standards.
On this page, you can download CV templates in English to customize yours according to your experience.
The last step is to adapt this example to your own professional profile and career path, which may differ depending on whether you are a recent graduate or already have experience.
- Recent graduate: if you have no experience, focus on your academic background, highlighting valuable projects, professional internships, volunteer work, and personal projects.
- Professional with experience: adapt the example to your own work history and use the XYZ formula to highlight your professional achievements.
Common Mistakes to Avoid When Writing a Resume in the U.S.
Here are some things to avoid when writing your resume.
- Using the same resume for every job: try to tailor your resume to the job you are applying for.
- Including a photo or unnecessary personal details: remember that in the United States, this data is irrelevant.
- Poorly translating key terms: if you have doubts about how to translate a term from Spanish to English, consult a translator or compare different sources on the internet.
- Making it too long: your resume should not exceed one page; otherwise, it may be discarded even if you have the necessary skills.
- Using a graphic-heavy design that doesn’t pass ATS filters: you may think that recruiters like resume templates with eye-catching designs, but the truth is that they are unlikely to pass ATS filters.
Común, Your Ally for Financial Stability in the United States
Having a strong resume is key to successfully entering the U.S. job market.
Just as a resume opens the door to great job opportunities, Común opens the door to financial stability for immigrants.
Discover Común, the option designed to serve the needs of immigrant communities in the U.S., with service available in Spanish.
Discover All the Benefits of Común!
- Open a checking account with a qualifying official identification from your home country.
- Mobile app available in Spanish and English.
- Easily receive payments from employers, cash checks, and send international money transfers to Latin America.
Discover Común, the option dedicated to meeting the needs of immigrant communities in the United States with services available in Spanish.
Frequently Asked Questions (FAQ)
If you still have questions, check out the next section.
Is It Necessary to Include References in the Resume?
It’s not necessary to include references in your resume, as companies usually request them later in the hiring process.
What Are the 3 Most Important Details in a Resume?
The 3 most important details are: contact information, professional experience, and skills.
What Language Should My Resume Be In When Applying in the U.S.?
The resume format used in the U.S. is becoming common in other countries, so the language should match the job posting.

International Money Transfers
How to make an international money transfer? Costs, times and requirements
8 min de lectura
International money transfers can be sent via bank wire, money transfer apps, or remittance services — each with different fees, speed, and delivery options. With Común, transfers to Latin America start at $2.99, with most arriving within minutes.
For immigrants in the United States, sending money to their home countries regularly is essential. Therefore, it is important to have access to affordable and accessible financial services.
If you want to know how to make an international money transfer, it is crucial to first compare the different providers of this service and choose the one that offers the most advantages for you and your family.
Comun stands out as a popular option among immigrants because it allows them to send money abroad from the United States, offering advantages in terms of cost, speed, and other key factors.
Below, we provide a comparison table that includes Comun and traditional financial institutions in the United States, such as Bank of America and Wells Fargo:
| Comun | Traditional Financial Institutions | |
|---|---|---|
| Fee | Transfer fee starting at 2.99 USD up to applicable limits | From 10 to 45 USD, depending on the bank |
| Intermediary fees | $0 USD | May generate extra fees from intermediary banks |
| Exchange rate | Competitive | Higher margin than official |
| Speed | Instant to a few minutes (average 8) | From 1 to 5 business days |
| Estimated total fee | 2.99 USD transfer fee + exchange rate, with no extra charges (The first transfer has no fee. Subsequent transfers have a fee starting at $2.99 USD, up to the applicable limit. ATM or intermediary charges may apply; check the app for more details). | From 20 to 60 USD, due to fees and less favorable exchange rates |
How Does an International Money Transfer Work?
The first point to understand is the types of bank transfers available, as this determines the final cost of sending an international money transfer.
In the United States, there are two types of international money transfers: through traditional banks or through specialized services for sending money abroad.
International Money Transfers via Traditional Banks
- Supported by official U.S. financial institutions and security measures, including:
- Identity verification (KYC/CIP) and ongoing AML monitoring (BSA).
- OFAC sanctions screening for senders and recipients.
- Consumer protections for remittances under Regulation E (pre-transfer disclosures, cancellation rights, and error resolution).
- Network and messaging security standards (e.g., SWIFT Customer Security Program).
- Multi-factor authentication and encryption for online banking access.
- A U.S. bank account is mandatory
- Operates through the SWIFT code
- Generates higher fees due to intermediaries
- Transfer time may take up to 5 business days
International Transfers via Specialized Applications
- Operates through digital networks connected with banks or physical branches in each recipient country
- Lower fees, as they do not use intermediaries and offer more competitive exchange rates
- Money transfers are completed within minutes or hours
- A U.S. bank account is not mandatory to use these services
Before paying unnecessary fees, make sure to choose the best international money transfer provider and make the most of your money.
Steps and Requirements for Making an International Money Transfer
Below, we outline what is needed to easily make an international bank transfer from the United States, whether you choose a traditional bank or a specialized application for this type of service:
1. Choose a Provider
Some of the traditional banks you can use are Chase, Bank of America, Capital Bank, Citibank, and Wells Fargo. If you don't have a US bank account, you'll need to make sure you have the necessary requirements to open an account, such as a Social Security Number (SSN). For the aforementioned banks, you can present an ITIN instead, along with a government-issued ID.
Another factor to consider is how long an international money transfer takes, as traditional banks usually take longer due to intermediaries involved in the process.
If you prefer a specialized application for international money transfers due to the flexibility they offer compared to banks, an excellent alternative is Comun, which allows you to transfer money from your phone without complications or intermediaries.
2. Create an Account
General Requirements for Opening an Account at a U.S. Bank
- Valid passport or immigration document
- Social Security Number (SSN)
- Individual Taxpayer Identification Number (ITIN)
- Proof of address in the United States
- Some banks require an initial deposit of approximately $25 USD
Depending on the bank, you may open the account online or by visiting a branch for data verification.
Requirements for Opening an Account with Comun
- Mobile phone compatible with Android or iOS
- Email address
- Official foreign identification
- Have a US residential address
In both cases, you will have access to a debit card and a mobile application that will allow you to make international money transfers and other transactions from the palm of your hand.
3. Enter Transaction Details
Once you activate your account, enter the information required for an international money transfer:
- Full name of your recipient, as it appears on their official ID
- Recipient’s phone number
- Recipient’s address (only if sending money to a bank account)
- Recipient’s account number (only if sending money to a bank account)
- SWIFT code (if transferring through a traditional bank)
Then, enter the amount you wish to send.
Comun and other specialized applications also allow cash pickup at physical locations, so your recipient does not need a bank account.
4. Review Costs and Rates
Next, review the international money transfer fees as well as the exchange rate, as these will impact the final amount your recipient receives.
The cost of an international money transfer depends on several factors, which we detail below.
5. Send the Money
Once you confirm that the information entered is correct, authorize the transfer, including any additional fees.
Comun allows you to track your transfers through its application, whether you choose to send money to a bank account or opt for cash pickup at a physical location.
Remember that transfer speed depends on the platform, and traditional banks can take up to 5 business days to complete these transactions.
6. Confirm Receipt
Finally, confirm with your recipient that the transfer was received within the stipulated timeframe. You can generate a transaction receipt directly in the mobile application.
Everything About the Cost of Sending Money Abroad from the U.S.
International money transfers are a common practice among immigrants in the United States.
That is why it is essential to detail the factors that influence the cost of transfers, as well as the best options for sending remittances to your family quickly and without complications.
These are the main factors to consider when calculating the cost of your international money transfers:
- Transfer Fees
International transfers incur a fee, which varies depending on the platform, whether it's a traditional bank or a specialized app.
Another factor that affects the fee level is the method used to send the money. The price can vary depending on whether the transaction is made through a website, an app, or at a physical branch.
International money transfer fees at traditional banks vary depending on the financial institution. Here are some examples:
- Bank of America: $45 USD
- Wells Fargo: from $25 to $40 USD
- Citibank: from $25 to $35 USD
- Truist Bank: $65 USD
On the other hand, some mobile applications offer international money transfer options for less than $3 USD, which is much more beneficial for the economy of foreign workers.
- Exchange Rate
The exchange rate also significantly impacts the final amount your recipient receives. It refers to the value applied by the platform when converting the dollar amount to the local currency.
Traditional banks generally use a lower rate than the official rate. For example, if the Mexican peso is officially 18.00, banks might apply approximately 17.20 MXN.
This means that if you send $300 USD, your recipient could receive about $13 less (240 MXN less), not counting the bank fees, which make the cost even higher.
- Hidden Fees
In addition to international money transfer fees, traditional banks may charge additional fees if intermediary banks are involved in processing the transfer.
We recommend checking all costs involved and choosing a competitive option that does not reduce the total amount your family will receive.
Comun is an excellent alternative for making international money transfers, as your first transfer fee is waived, and subsequent transfers have a fee starting at $2.99 USD per transfer, up to applicable limits, with no hidden fees or intermediaries.
Review our comparison table between traditional banks and Comun at the beginning of this article, and choose the best option for your money.
Want to Make Secure International Money Transfers? Do It Easily with Comun
In this article, we presented how to make an international money transfer from the United States through traditional banks or specialized applications such as Comun, an excellent choice for immigrants.
Comun is the solution for bringing immigrant families closer together through affordable and low-cost remittances.
Why Choose Comun for International Money Transfers?
- Easily open your account with official documentation from your country
- Send money to your family with a transfer fee starting at $2.99 USD, up to the applicable limits.
- Your money will arrive within minutes
- Access a mobile application and Visa debit card for better control of your finances
Discover an easy and fast way to access the financial services you deserve. Open your account with Comun and forget about complications.
What are the main ways to send money internationally?
Bank-to-bank wire transfers, dedicated money transfer apps, and remittance services are the three main options, each with different costs and delivery times.
What should I compare between international transfer options?
The fee, exchange rate, delivery speed, and whether the recipient needs a bank account or can pick up cash.
How does Común handle international transfers to Latin America?
Transfers start at $2.99, with your first transfer at no cost. Delivery options include bank deposit or cash pickup at locations like Elektra and Oxxo in Mexico, with most transfers arriving within minutes.
Frequently asked questions
What's the cheapest way to send money internationally?
It depends on the corridor and amount; always compare the fee AND the exchange rate, since a low fee can hide a worse exchange rate.
Do I need a bank account in the destination country to receive money?
Not always — some services, including Común, offer cash pickup options that don't require a bank account.
How long do international transfers usually take?
It varies by method — bank wires can take days, while modern remittance apps like Común often deliver within minutes.
Are international money transfers safe?
Yes, when using a licensed provider that's transparent about fees and exchange rates before you confirm.
What information do I need to send an international transfer?
Typically the recipient's name, destination country, and either their bank account details or pickup preference, depending on the method.
Does Común charge for international transfers?
Fees start at $2.99 per transfer, with your first transfer at no cost.
Checking account
What Is a Bank Account and What Are the Benefits of Having One?
8 min de lectura
A bank account is a financial account a customer holds at a bank. A bank account lets customers deposit and withdraw money, as well as write checks. That's why it's also called a checking account.
The advantages of having a bank account include:
- Easy access to your money — 24/7 banking access through the bank's website or app
- No need to carry cash
- The ability to earn interest on your deposits
- Building a credit history, which can matter when you want to apply for a loan in the future
How Do You Open a Bank Account?
Opening a bank account is relatively easy. You'll need to provide some personal information, like your name, date of birth, and address. You'll also be asked for ID — usually a Social Security Number (SSN) is enough. More modern banks, like Común, let you replace your SSN with a passport or consular ID. You may also be asked for documentation proving your address.
The Different Types of Bank Accounts Available
There are different bank accounts to choose from. The most common type is the checking account, which lets you deposit and withdraw money and write checks. A checking account is a great option if you want easy access to your money without carrying cash, since your account's debit card lets you pay at any business.
Another common type of bank account is the savings account. Savings accounts let you save money and earn interest on your deposits. It's a great option if you want to build up your savings over time.
There are also several specialized bank accounts, like accounts for students, seniors, and businesses. Be sure to research the different bank accounts available and choose the one that best fits your needs.
How to Manage a Checking Account Online
Many bank customers choose to manage their bank account online. You can do this through the bank's website or app. Managing your bank account online lets you access it 24 hours a day, 7 days a week.
Some things you can do online include:
- View your account balance and transaction history
- Transfer money between savings and checking accounts
- Pay bills
- Pay your credit card
- Deposit checks
- Set up banking alerts for specific events, like a low balance or a large deposit
What Does It Cost to Open a Bank Account in the United States?
Some accounts, like the one Común offers, come with no monthly fee and no minimum balance requirement. However, many banks do charge fees. These include some of the most popular banks in the United States: Bank of America, JPMorgan Chase, Citigroup, and Wells Fargo. Here are some of the fees they charge:
- Monthly service fee
- Minimum balance requirement
- Overdraft fee
- Check-cashing fee
Certain banks also limit Spanish-language support in their digital interfaces or customer service centers. Be sure to research the fees charged and the language support offered before opening an account with any bank.
FDIC Backing
The Federal Deposit Insurance Corporation (FDIC) is a government agency that insures consumer deposits at banks in its network. It's important to choose a bank with this backing, since you'll have up to $250,000 of your funds insured by the U.S. government if your bank fails.
The Benefits of Común
At Común, you'll find a checking account with no monthly fee and no minimum balance, in Spanish (from the mobile app to customer support), with the flexibility to apply using your passport, no matter your nationality. Opening an account is very easy, and you'll have 24/7 access, along with the ability to pay bills or deposit checks. Común is FDIC-insured, so your funds are protected up to $250,000 USD.
As with any financial service, be sure to research the different options available and choose the one that best fits your needs.

Financial Education
What is a W-2 form? Complete 2026 guide for immigrant workers in the U.S.
8 min de lectura
What is a W-2 form? Complete 2026 guide for immigrant workers in the U.S.
A W-2 form is one of the most important tax documents employees receive in the United States. If you worked for an employer during the year, your W-2 shows how much money you earned and how much money was withheld for taxes.
For many immigrant workers, this may also be the first time dealing with U.S. tax documents. Understanding how to read a W-2, when you should receive it, and what to do if something is incorrect can help you file taxes more confidently and avoid delays during tax season.
This article is for informational purposes only and does not constitute legal or tax advice. It is recommended to consult a qualified tax professional for guidance specific to your situation.
What is a W-2 form?
A W-2 form, officially called the Wage and Tax Statement, is a tax document employers send to employees every year. The form reports: total wages earned, federal income taxes withheld, Social Security and Medicare taxes withheld, state or local tax withholdings if applicable.
The IRS requires employers to provide a W-2 to employees who earned wages during the tax year. You typically receive a W-2 if you are considered an employee of a company. Independent contractors and certain gig workers generally receive Form 1099 rather than a W-2.
When should you receive your W-2?
Employers must send W-2 forms to employees by January 31 of the year following the reported tax year. If you haven't received your W-2 by early February, contact your employer. If you still don't receive it, you can contact the IRS for assistance.
What information does the W-2 contain?
- Box 1: Wages, tips, and other compensation
- Box 2: Federal income tax withheld
- Box 3: Social Security wages
- Box 4: Social Security tax withheld
- Box 5: Medicare wages
- Box 6: Medicare tax withheld
- Boxes 15–17: State tax information
W-2 vs. 1099: what is the difference?
| W-2 employee | 1099 contractor |
|---|---|
| Employer withholds taxes | Worker usually pays taxes independently |
| May receive benefits | Usually no employer benefits |
| Employer generally has greater control over work duties | Worker has more independence |
| Receives W-2 in January | Receives 1099-NEC if eligible |
Can ITIN holders get a W-2?
Yes. Employees can receive a W-2 using an ITIN instead of an SSN. If you are legally working in the U.S. with work authorization but do not yet have an SSN, you can use your ITIN for tax purposes. However, remember that an ITIN does not authorize employment on its own. For more information about ITINs, visit comun.app/itin.
What to do if your W-2 has errors?
If you find errors on your W-2, such as an incorrect name, SSN/ITIN, or incorrect figures: contact your employer immediately to request a corrected W-2 (Form W-2c), wait for the corrected W-2 before filing your tax return, if you cannot get a correct W-2 in time, the IRS has procedures to help you.
FAQ
What is the W-2 form?
It is the Wage and Tax Statement your employer sends you each January, showing how much you earned and how much you paid in taxes the previous year.
When will I receive my W-2?
No later than January 31 of the year following the reported tax year.
What do I do if I don't receive my W-2?
First contact your employer. If unresolved, you can contact the IRS for assistance.
This article is for informational purposes only and does not constitute legal or tax advice. Común is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank, Member FDIC.
Financial Education
How to renew your ITIN: step-by-step guide
8 min de lectura
How to renew your ITIN: step-by-step guide
Your ITIN may have expired if you have not used it on a federal tax return for three consecutive tax years. To renew it, you must submit Form W-7 to the IRS, which is the same form used to apply for a new ITIN. You do not need to wait until tax season to start the renewal process, and you can submit your renewal before filing a tax return.
When does an ITIN expire?
An ITIN (Individual Taxpayer Identification Number) is a 9-digit tax processing number issued by the IRS. It is designed specifically for individuals who need to report income and file taxes in the United States but are ineligible for a Social Security Number (SSN).
An ITIN expires when it has not been used on a federal tax return for three consecutive tax years. The IRS explains that the expiration takes effect on December 31 of the third year of non-use.
An ITIN does not expire because time has passed, but because it has not been used for federal tax filing. Once expired, the number remains the same and can usually be renewed rather than replaced. An expired ITIN does not erase previous tax filings or financial records associated with it.
How do you know if your ITIN has expired?
One sign that an ITIN may have expired is not having filed a federal tax return with that number for several years. If three consecutive tax years have passed without using the ITIN, the number may no longer be active according to current IRS rules.
The IRS may also send a notice informing you that your ITIN needs to be renewed. Receiving a renewal notice does not mean there is a problem with your record. It simply means the IRS has determined that renewal is required before the number can be used again for tax filing purposes.
Tax software may also indicate that an ITIN has expired when preparing a return. If you are unsure if your ITIN has expired, checking IRS correspondence or reviewing past tax filings can also be a way to confirm status.
What happens if your ITIN expires?
An expired ITIN can delay the processing of a federal tax return. According to the IRS, certain tax credits and benefits associated with a return may not be available until the ITIN has been renewed.
An expired ITIN does not cancel previous tax filings, change your tax history, or create a new tax identity. The IRS maintains records associated with the original number even if that number has expired due to non-use.
An expired ITIN also does not automatically affect financial accounts that were opened using that number. However, an active ITIN may be required when completing future tax-related paperwork or applying for certain financial products and services.
If your ITIN has expired, the most practical step can be to start the renewal process before filing your next federal tax return. Taking action early can help avoid delays and additional paperwork during tax season.
What do you need to renew your ITIN?
To renew an ITIN, you must complete Form W-7 and mark it as a renewal application.
You also need documentation that proves identity and foreign status. The IRS lists acceptable documents in its official instructions, which include: passport, U.S. Citizenship and Immigration Services (USCIS) photo identification, visa issued by the U.S. Department of State, U.S. driver's license, foreign driver's license, foreign military identification card, national identification card (must contain name, photograph, address, date of birth, and expiration date), among others.
If your legal name has changed since your ITIN was issued, supporting documentation such as a marriage certificate or court order may be required.
How to renew your ITIN: step by step
1. Complete Form W-7
Fill out Form W-7 and indicate that you are renewing an existing ITIN. Make sure all personal details match your official documents.
2. Gather required documents
Collect identification documents that prove identity and foreign status. The IRS outlines acceptable documents in the Form W-7 instructions.
3. Attach supporting documentation
Include any additional documents required for your situation, such as name change records or prior IRS notices.
4. Submit your application
You can submit Form W-7 by mail, through an IRS-certified Acceptance Agent, or at select IRS Taxpayer Assistance Centers.
5. Wait for IRS processing
The IRS reviews the application and supporting documents before issuing confirmation. Keep copies of everything submitted for reference.
How long does ITIN renewal take?
Processing times vary throughout the year, but the IRS currently advises applicants to allow approximately seven to eleven weeks to receive notification regarding an ITIN application or renewal. Processing may take nine to eleven weeks during peak tax season or when applications are submitted from outside the United States.
Submitting a complete application can help prevent unnecessary delays. Applications that are missing required documents may take longer because the IRS must request additional information before processing can continue.
Can Común help me renew my ITIN?
Yes. Común's ITIN service helps with both new ITIN applications and ITIN renewals.
Común's ITIN service costs $199 and includes guidance throughout the renewal process. The service works with IRS-certified agents who help prepare the required paperwork, explain the requirements, and answer questions in Spanish.
The process can be completed from your phone, making it easier to organize documents and track progress without visiting multiple offices. Común also offers a money-back guarantee if the ITIN application is not approved according to the program terms.
FAQ
Do all ITINs expire?
Not all ITINs expire immediately or at the same time. An ITIN expires if it has not been used on a federal tax return for three consecutive tax years.
Can I renew my ITIN without filing taxes?
In some cases, yes. The IRS allows exceptions where Form W-7 can be submitted without a tax return depending on eligibility.
What form do I use to renew my ITIN?
You use Form W-7 for both new applications and renewals.
How long does it take to renew an ITIN in 2026?
The IRS estimates about seven weeks for processing. Processing may take approximately nine to eleven weeks during tax season or for certain international applications.
Can I still use my Común account if my ITIN expires?
An expired ITIN does not erase your financial history. If you have questions about how an expired ITIN may affect your specific account, contact Común directly for guidance.
What happens to my tax refund if my ITIN expires?
If an ITIN is expired, the IRS may delay processing a return until it is renewed. Certain tax benefits may not be available until the ITIN has been renewed, which can affect the timing of a refund.
Común is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank, Member FDIC. The Común Visa® Debit Card is issued by Community Federal Savings Bank.
Checking account
What Is a Debit Card and How Does It Work?
8 min de lectura
A debit card is a bank card that lets you make purchases and withdraw money using funds available in your bank account. A debit card looks a lot like a credit card, but it works differently. When you use a debit card, the money is deducted directly from your bank account. That means you can only use the card if you have enough available funds — otherwise, the transaction won't go through.
Who Issues Debit Cards for Consumers?
Debit cards are issued by banks and are linked to individual checking accounts. You can get a debit card by opening a bank account at any bank or credit union that offers this service.
Many banking institutions also offer other digital services, like mobile and online banking, that let you manage your account over the internet or through a mobile device. In general, all banks offer services designed for people with different needs and income levels, giving nearly every adult access to banking.
Even though debit cards are easy to use, you should be careful with them. If you lose your card or it's stolen, report it to your bank immediately to prevent fraud or misuse. You should also regularly check your statements for fraudulent transactions or errors. With a bit of care, debit cards can be a useful tool for managing your money and making purchases online and in person.
How Can You Use Your Debit Card to Make Purchases or Withdraw Money From an ATM?
There are many ways to use a debit card to make purchases or withdraw money from an ATM.
To make a purchase, you can insert your card into the point-of-sale (POS) terminal and select "debit" as your payment method. Then enter your PIN and select the purchase amount.
To withdraw money from an ATM, insert your card into the machine's slot and select "checking/savings." Then enter your PIN and select the amount you want to withdraw.
You can also use your debit card to make payments online or by phone. To make an online payment, enter your card details on the merchant's website. To make a payment by phone, call the merchant's customer service number and provide your card details when asked.
What Protection Do Visa Debit Cards Have Against Unauthorized Charges?
If you have a Visa card, you're protected by Visa's Zero Liability policy. This policy guarantees you won't be held responsible for any unauthorized charges made with your card. That means if someone steals your card or uses it without your permission, you won't have to pay for those charges.
Visa's Zero Liability policy applies to all Visa cards, including debit and credit cards. It also applies to all transactions, including online and in-person transactions. This policy was put in place to help protect consumers against fraud and identity theft.
If you're a victim of fraud or identity theft, be sure to report it right away. You can call Visa's toll-free number 24/7 to report any incident. Visa will work with you to resolve the issue and help protect your money and identity.
What Are Virtual Debit Cards?
A virtual card is a card that isn't physical — it exists only in the digital world. Virtual cards are often used for online purchases, since they offer more security than using a regular debit card.
One of the benefits of virtual cards is that they can be used to limit how much money is spent on a purchase. For example, if you're buying something online and want to make sure you don't go over budget, you can use a virtual card instead of your regular credit or debit card. This can help you stay within budget and avoid racking up debt. Likewise, if your information is stolen during a transaction, the thief won't be able to access your other cards. This can help prevent fraud and keep your personal information safe.
If you're interested in getting a virtual card, there are a few things you should know. First, not all banks offer virtual cards, so you may need to open a new account at a bank that offers this service. Second, not all merchants accept virtual cards, so there may be some places where you can't use them. Finally, virtual cards sometimes come with associated fees, so be sure to read the terms and conditions before using one.
The Benefits of Común
When you get a checking account with Común, you'll get two debit cards: a physical one and a virtual one.
The physical card lets you make purchases at any business, and offers security thanks to its contactless capability and chip. This prevents your card details from being cloned or used for fraud.
The virtual card lets you make online purchases with more confidence, since contactless technology and chip protection aren't available on the internet — but if fraud does happen, the card can be canceled and replaced immediately. You can contact our support team anytime to report these cases.
Común debit cards work at more than 55,000 ATMs across the United States for deposits and withdrawals, and are protected by Visa's Zero Liability policy. That means any unauthorized charge won't be deducted from your checking account balance.
International Money Transfers
How to send money to Mexico via WhatsApp? Común vs. WhatsApp Pay
8 min de lectura
How to send money to Mexico via WhatsApp? Común vs. WhatsApp Pay
WhatsApp does not currently offer a service to send money directly from the United States to Mexico.
WhatsApp is one of the most popular ways to stay in touch with family and friends across borders. While the app supports payments in certain countries, its payment features are not available for sending money from the United States to Mexico.
However, for people living in the United States who are looking into sending money to Mexico, there are many different options available. From traditional service providers such as Western Union and MoneyGram to apps with instant international transfers like Wise, Remitly and Común.
Can I send money to Mexico via WhatsApp from the United States?
At this time, WhatsApp does not offer an official service that allows people in the United States to send money directly to recipients in Mexico through WhatsApp Pay. WhatsApp's payment functionality is only available in Brazil and India.
This means that you can still use WhatsApp every day to communicate with family and friends in Mexico, but you cannot transfer money from a U.S. account to a recipient in Mexico using WhatsApp Pay.
Some money transfer companies offer WhatsApp-based experiences that help initiate transfers, but those services are different from WhatsApp Pay itself. The actual transfer is processed through the remittance provider rather than through WhatsApp's native payment system.
What is WhatsApp Pay and how does it work?
WhatsApp Pay is a payment feature integrated into WhatsApp that allows eligible users to send and receive money without leaving the app. The service operates through local payment networks and financial partners in supported countries.
As of 2026, WhatsApp Pay is available in India and Brazil. It is not broadly available as a payment method in the United States, and it is not available as a direct remittance solution for sending money from the United States to Mexico.
Why can't I use WhatsApp to send money to Mexico?
Cross-border money transfers require financial institutions, payment networks, regulatory approvals, identity verification procedures, and international settlement systems. WhatsApp Pay was built around local payment systems in specific countries. Because of this, the service does not currently support direct remittances from U.S. bank accounts to recipients in Mexico.
This limitation often creates confusion because WhatsApp is widely used on both sides of the border. Messaging a family member in Mexico through WhatsApp is easy, but sending money through WhatsApp Pay is a different service with separate availability requirements.
How much does WhatsApp Pay charge for sending money?
There is no standard fee for sending money from the United States to Mexico through WhatsApp Pay because that service is not currently available.
If you're in the United States and need to send money to Mexico, you will need a remittance service provider. To compare the costs related to sending money to Mexico, it can be important to review: transfer fees, exchange rates, delivery methods, transfer speed, and recipient requirements.
What's the best way to send money to Mexico if not via WhatsApp?
There is no single answer because different money transfer methods work better for different situations. Bank transfers can be a familiar option for people who already have a checking account. Traditional remittance providers such as MoneyGram and Western Union offer multiple delivery methods, including bank deposits, cash pickup locations, and mobile wallets in some markets.
Digital remittance platforms have become increasingly popular because they offer the possibility of sending money directly from a smartphone. These services typically display the exchange rate, fees, and delivery method before the transfer is completed.
One option is Común through its remittances services, which allows eligible customers to send money to Mexico and other countries in Latin America directly from the Común app. Transfers start at $2.99, and many transfers are delivered on the same day depending on the destination and delivery method.
How to send money to Mexico with Común? (step by step)
1. Open the Común app on your phone.
Sign in to your account and navigate to the remittance section.
2. From the main page, select "Envía una Remesa".
Select the option on your app.
3. Choose your recipient or add a new one.
Provide the required details for the person receiving the transfer.
4. Enter the transfer amount.
Review the amount you want to send.
5. Review the transfer details.
Confirm the recipient information, delivery method, transfer amount, and estimated delivery timeframe.
6. Confirm the transfer.
Complete the transaction and wait for confirmation. Many transfers are delivered the same day, although delivery times may vary.
WhatsApp Pay vs. Común: a direct comparison
| Feature | WhatsApp Pay | Común |
|---|---|---|
| Send money from the United States to Mexico | No | Yes |
| Cross-border remittances | No | Yes |
| Starting transfer cost | Not available for U.S.-Mexico transfers | Starting at $2.99 |
| Delivery to recipients in Mexico | Not supported | Available |
| Transfer purpose | Domestic payments in supported countries | Money transfers to Mexico and Latin America |
WhatsApp Pay was created for payments within certain supported markets. Común remittance services make it possible to send money from the United States to recipients in Mexico and other countries in Latin America directly from the Común app.
A Común account can be opened with a passport or more than 100 Latin American IDs with no minimums or monthly fees.
FAQ
Can I send money to Mexico using WhatsApp?
No. WhatsApp does not currently provide an official service that allows users in the United States to send money directly to recipients in Mexico through WhatsApp Pay.
How does WhatsApp Pay work?
WhatsApp Pay allows eligible users in supported countries to send and receive money through WhatsApp using local payment networks and financial partners.
How long does it take for the money to arrive if I send it with Común?
Many transfers sent through Común are delivered on the same day. Delivery times may vary depending on the destination, delivery method, and recipient institution.
What do I need to send money to Mexico with Común?
You generally need a Común account, the recipient's information, the transfer amount, and any additional details required for the selected delivery method.
How much does it cost to send money to Mexico with Común?
Común international transfers start at $2.99. The total cost may vary depending on the transfer amount, destination, and exchange rate.
Is it safe to send money through apps from the United States?
Using a regulated money transfer provider can help protect your transaction through identity verification, encryption, fraud monitoring, and transaction tracking features.
Común is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank, Member FDIC. Peer-to-peer payments services are provided by Cross River Bank. No minimums, no maintenance fees. Remittance service provided by Service UniTeller, Inc. Remittance fees start at $2.99 but may vary. Común Inc. may earn revenue from the conversion of foreign currencies.







Thousands of immigrants are already achieving more with their money. You can too.
Comun is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank; Member FDIC. The Comun Visa® Debit Card is issued by Community Federal Savings Bank, pursuant to a license from Visa U.S.A Inc. and may be used everywhere Visa Cards are accepted.
Comun is a fintech company and not a bank or licensed money transmitter.
* Results may vary. For a complete list of eligible IDs and application requirements, follow this link.
^ No minimums, no maintenance fees. ATM or transfer fees may apply. See app for fee details.
‡ Direct deposit funds are typically available when we receive the payment file, up to two days before the scheduled payment date. This early availability is not guaranteed.
** A service provided by Service UniTeller, Inc. Service UniTeller, Inc. is licensed in all states that require a license. Remittance fees start at $2.99 but may vary. Please check the app for more details. Comun Inc. may earn revenue from the conversion of foreign currencies.
† Funds in your account are FDIC insured up to $250,000 by ownership category through Community Federal Savings Bank (CFSB), Member FDIC, in the event CFSB fails.


