
Financial Education
How To Register Your Business As An Immigrant
A simple walkthrough on getting the right licenses, tax IDs, and bank accounts to start your business.
8 min read

Olivia Rhye
03 Jun 2025
Registering a business as an immigrant in the U.S. generally involves choosing a business structure, obtaining an EIN from the IRS, and registering with your state. You don't need an SSN to get an EIN — an ITIN or foreign status works for this process.
Starting a business as an immigrant in the U.S. is an exciting step toward financial independence and long-term success. Fortunately, you don’t need U.S. citizenship or a Social Security Number (SSN) to register a business. Many immigrants successfully operate businesses using an Individual Taxpayer Identification Number (ITIN) and other available options. This guide walks you through the key steps to officially register your business, get the right tax IDs, and open a business bank account.
If you choose a Sole Proprietorship, you may need to register a Doing Business As (DBA) name, which allows you to operate under a name different from your personal name. For an LLC or Corporation, you’ll need to check your state’s Secretary of State website to confirm that your chosen business name is available. Each state has specific rules about what names can be used, so ensure yours complies with local guidelines.
What business structure should I choose?
Common options include sole proprietorship (simplest, no separation between personal and business liability), and LLC (separates personal assets from business liability, more paperwork).
Do I need a Social Security Number to register a business?
No — you can obtain an EIN (Employer Identification Number) from the IRS using an ITIN or by mail/fax if you don't have either an SSN or ITIN yet.
What are the basic steps to register my business?
Choose a business name and structure, register with your state, obtain an EIN from the IRS, and open a business bank account once you have your EIN and formation documents.
Frequently asked questions
Can I start a business in the U.S. without a Social Security Number?
Yes, you can obtain an EIN using an ITIN, or through an alternate IRS process if you have neither.
What's the difference between a sole proprietorship and an LLC?
A sole proprietorship has no legal separation between you and the business; an LLC separates personal assets from business liability but requires more paperwork.
How do I get an EIN?
Apply directly through the IRS website or by mail/fax — it's free and doesn't require a lawyer.
Do I need a lawyer to register my business?
Not necessarily for a simple structure like a sole proprietorship, though an LLC may benefit from professional guidance depending on complexity.
Can I use my personal bank account for my new business?
It's generally recommended to separate personal and business finances once your business is registered, for cleaner bookkeeping and liability protection.
What documents do I need to keep once my business is registered?
Your EIN confirmation letter, formation documents (for an LLC), and any state registration certificates.
About Común
Común aims to support the Latino community in the United States. It offers a debit account that can be opened with more than 100 valid Latin American IDs and an app available in Spanish.
Visit Común's website or download the app for free to learn more about the full offer and applicable terms.
Olivia Rhye
Community Partner

Living in the United States
What is the Alien Registration Number (A-Number)?
8 min de lectura
Alien Registration Number or A-Number: Everything you need to know if you’re in the United States
Immigrants living in the United States should become familiar with several terms and procedures to ensure their long-term stay in the country.
One way to compile all the information related to your immigration process is through the A-Number or Alien Registration Number. This identifier is assigned by the Department of Homeland Security (DHS) to foreign nationals residing in the country.
It’s very important to know this information, as it serves as the identification number for your immigration file.
In this article, we’ll explain what the Alien Registration Number is, what it’s used for, and why it’s so important for immigration procedures.
What is the Alien Registration Number (A-Number) and what is it for?
The first step to identifying an A-Number is knowing that it always begins with the letter “A” and contains 8 or 9 digits.
The main function of this number is to allow USCIS and other agencies to quickly track immigration cases and applications related to each person.
Here are some examples of when the A-Number is used:
- To track your permanent residence (Green Card) application.
- When you apply for a work permit (EAD).
- If you apply for an adjustment of status, your A-Number will be used to link your case file.
Where can you find the Alien Registration Number, and who receives it?
To locate your A-Number, you can check several official documents issued by USCIS or DHS, such as:
- Green Card
- Employment Authorization Document (EAD)
- USCIS notices
- Immigration court orders
How to identify the A-Number
Below we break down how the A-Number appears on various official documents.
Document
Location
Permanent Resident Card
On the front, next to “USCIS#” or “A#.”
Work Permit (EAD)
On the front
USCIS Notices
In the upper corner or near the applicant’s name
Immigration court documents
At the top of the document.
This is a unique number assigned only to individuals with formal and permanent files in U.S. immigration agencies, such as:
- Permanent residents (Green Card holders).
- Refugees or asylees.
- Adjustment of status or work permit applicants.
- Individuals with open cases before immigration court.
On the other hand, temporary visitors such as tourists, students, or non-immigrant visa holders do not receive an A-Number since their cases do not require a permanent immigration file.
Why is the Alien Registration Number important in immigration procedures?
The A-Number is a central identifier used in multiple immigration procedures needed to regularize your status in the country.
Here are the most common uses of the A-Number in immigration processes.
Tracking immigration cases (USCIS Case Status)
If you want to track the status of your pending applications, such as permanent residence, work permit, or adjustment of status, you need to enter your A-Number in the USCIS Case Status system.
This way, you can know exactly which stage your case is in and stay informed of updates to ensure your process stays on track.
Updating personal information
It’s essential to keep your immigration records updated. If you change your address, phone number, or legal name, your A-Number will help you update your information.
This helps ensure you receive official notifications and avoid delays in important procedures.
Avoiding mistakes in immigration processes
Since the A-Number functions as a unique identifier, it also helps avoid confusion between applicants with the same or similar names.
Be sure to use your A-Number correctly when filling out forms or official documents so that all your information stays under the same file and saves time when searching for a document or specific information.
In short, this number helps simplify the immigration process for immigrants and provides a sense of security and control during procedures that can often cause stress and uncertainty.
What to do if you don’t have or don’t remember your A-Number
If you don’t have an A-Number, remember that USCIS assigns one once you start an immigration process in the United States. If you already have one but can’t remember it, follow these tips to locate it.
- Check your official documents, such as your Green Card, work permit, or any forms submitted to USCIS.
- Log in to your USCIS online account and check the “manage your case” section.
- Call the USCIS Contact Center at 1-800-375-5283, explain that you can’t find your A-Number, and ask for assistance locating it.
Avoid using a fake A-Number, as this could cause problems with immigration authorities.
Organize your immigration life while managing your finances with Comun
As you can see, the A-Number is essential to staying organized during immigration procedures. It helps keep your documents together in one file, making them easier to locate and reducing the risk of delays caused by mistakes.
Another important aspect of immigrant life in the U.S. is having the right tools to keep personal finances organized.
Meet Comun, the platform designed to help immigrants manage their finances with ease.
Here are some of the benefits Comun offers:
- Open an account with a qualifying official identification from your home country.
- Send money to several countries with clear and competitive fees, up to the applicable limits.
- Access support in both Spanish and English.
Want to discover a truly fair and accessible financial service? Open your Comun account today!
Just as your A-Number helps you keep your immigration documents organized, Comun helps you maintain your financial stability in the United States.
Frequently Asked Questions (FAQ)
If you still have questions, check out our FAQ section.
What is the USCIS number? Is it the same as the A-Number?
The USCIS number appears on your permanent resident card or work permit. It’s actually the same identifier as your A-Number, which appears on these documents preceded by “USCIS#.”
What is the Alien Number?
The Alien Registration Number is the official name for the A-Number assigned by DHS or USCIS to individuals who are not U.S. citizens, allowing them to track their immigration process through a unique file.

International Money Transfers
How to receive money from the United States in Mexico: complete guide
8 min de lectura
How to receive money from the United States in Mexico: complete guide
To receive money from the United States in Mexico, you need to tell the sender which payment method you prefer. It can be a bank deposit, cash pickup at participating locations, or access through your bank account for ATM withdrawals. Depending on the service used, the money may arrive within minutes or on the same day.
Receiving money from the United States is easier today because there are more delivery options available than ever before. Depending on the remittance provider, recipients may be able to receive funds through a bank deposit, cash pickup, or other available methods. Understanding these options can help you choose the most convenient way to receive money and compare remittance services more effectively.
How does money sent from the United States arrive in Mexico?
Money sent from the United States can arrive in Mexico through several different delivery methods. The option available depends on the remittance service chosen by the sender and the payment preferences of the recipient. The most common delivery methods include:
- Direct deposit into a Mexican bank account
- Cash pickup at participating payment locations (like OXXO, Walmart, Bodega Aurrera, Waldos, etc.)
- Deposit into an account that allows access through ATMs
The delivery method should be selected before the sender completes the transfer. Choosing the correct option from the beginning can help make the process easier for the recipient.
What information does the sender need?
For a bank deposit, the sender will usually need:
- Your full name
- Your bank name
- Your account number or CLABE number
The CLABE is the standardized 18-digit banking number used in Mexico to identify bank accounts for electronic transfers.
For cash pickup, the sender may only need:
- Your full name
- Your city and state
- A valid government-issued identification document for collection
Before sharing information, verify that names and account details match your official documents. Small errors can delay delivery or require corrections before the funds are released.
What are the options for receiving money from the U.S. in Mexico?
| Payment method | Typical delivery time | Requires bank account | Where to receive |
|---|---|---|---|
| Bank deposit | Minutes to one business day | Yes | Mexican bank account |
| Cash pickup | Minutes to same day | No | Participating payment locations (OXXO, Walmart, etc.) |
| ATM access through deposited funds | Depends on deposit timing | Yes | ATM network linked to the account |
Bank deposits can be useful for paying bills, saving money, or making digital payments. Cash pickup may be a practical option when a recipient does not have a bank account or prefers to receive physical cash. Accessing funds through an ATM can provide additional flexibility after the money has been deposited into an account.
Can I receive money from the U.S. without a Mexican bank account?
Yes. Many remittance services allow recipients to collect funds in cash without having a bank account. Cash pickup services are available through networks of participating payment locations throughout Mexico.
To collect the funds, recipients are typically asked to present: a valid identification document, the transaction reference number if required, information that matches the transfer details.
How long does it take for money to arrive in Mexico from the United States?
Delivery times vary depending on the remittance provider, payment method, verification requirements, holidays, and banking schedules. Some transfers arrive within minutes, while others may take several hours or up to one business day.
Bank deposits may take longer if the transfer is initiated outside banking hours or requires additional verification. Public holidays in the U.S. or Mexico may delay the transfer delivery times and dates. Cash pickup transfers are often available more quickly because they do not depend on bank processing schedules.
What are the fees for receiving remittances in Mexico?
In many cases, the sender pays the remittance fee when initiating the transfer. Recipients in Mexico often receive the full amount designated by the sender, although the final amount can be affected by exchange rates and the terms of the transfer service. Some banks in Mexico have fees for international transfers, and some cash pick-up locations may have fees when collecting cash.
Before collecting a transfer, it can be useful to confirm: the amount sent, the exchange rate applied, any collection requirements, the delivery method selected, and if fees are applicable in your case.
How do I receive money sent with Común?
If your family member in the United States uses Común to send money, they can choose the delivery method that works best for you in Mexico. Depending on the available options for the transfer, funds may be delivered through a bank deposit or made available for cash pickup through participating payment locations.
Remittances sent through Común start at $2.99, which are covered by the sender. Many transfers are delivered the same day, although it will depend on the destination and delivery method selected. To learn more, visit comun.app/remittances.
What to do before receiving your next remittance
Decide whether you prefer a bank deposit or cash pickup before the sender initiates the transfer. Having your account details, documents, and personal information ready can help reduce mistakes and delays.
Make sure you share your preference for receiving remittances with the sender. If you're selecting a cash pick-up location, verify if they have locations available nearby or if you will need to travel to pick it up. When handling cash, it is always important to consider safety precautions.
If your family member in the United States doesn't know about Común yet, you can share the website so they can evaluate if it's an option that suits their remittance needs. Común offers the possibility of opening an account using a passport or more than 100 valid Latin American IDs. The account doesn't have any minimums or monthly fees.
FAQ
How do I receive money sent from the United States to Mexico?
You can receive money through a bank deposit, cash pickup at participating locations, or through funds deposited into an account that can be accessed through an ATM.
Can I receive money from the U.S. without a bank account?
Yes. Many remittance providers offer cash pickup services. A valid identification document is usually required.
How long does it take for money to arrive from the U.S. to Mexico?
Some transfers arrive within minutes, while others may take several hours or up to one business day.
What information do I need to provide to receive a remittance?
Bank deposits usually require account details. Cash pickup services generally require identification and matching recipient information.
How much is the commission for receiving money from the U.S.?
The recipient does not always pay a fee directly. Costs may depend on the provider, exchange rate, and transfer terms selected by the sender.
What happens if the money doesn't arrive on time?
The sender should verify the transaction status with the remittance provider. Delays can occur because of verification requirements, banking schedules, holidays, or incorrect recipient information.
Común is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank, Member FDIC. Peer-to-peer payments services are provided by Cross River Bank. No minimums, no maintenance fees. Remittance service provided by Service UniTeller, Inc. Remittance fees start at $2.99 but may vary. Común Inc. may earn revenue from the conversion of foreign currencies.
Financial Education
How to fill out a check in the United States in 5 simple steps (+ Example)
8 min de lectura
Have you ever filled out a check? Although most transactions today are digital, knowing how to fill out a check is essential—especially if you are just beginning your financial life.
According to recent data, one-third of Americans paid by check in 2024, demonstrating that checks still play an important role in the U.S. economy.
You might consider checks an outdated payment method; the reality is that they are useful in specific situations. For that reason, we will explain what a check is, the different types of checks, and how to complete them properly.
What Is a Check and What Is It Used For?
Despite the digital era, checks remain a relevant traditional payment method due to their formality and traceability. They are used for rent payments, purchases, and service payments.
Additionally, checks are a common payment method among the immigrant community, who often use them while adapting to the U.S. banking system.
But what exactly is a check and what are its characteristics? It is a physical document issued by an individual or business (the drawer) to order a bank to pay a specified amount to a third party. For the payment to be processed, the drawer must have sufficient funds in their checking account.
In general, a check contains the following information:
- Name of the drawer, whether an individual or a business
- Name of the payee
- Financial institution where the money will be drawn
- Amount to be paid, both in numbers and in words
- Signatures of the drawer
What Are the Different Types of Checks?
There are different types of checks in the United States. In this case, we will focus on the personal check, although you may choose the option that best suits your needs.
Personal Check
A personal check is a payment order issued by an individual to another individual using the funds in a checking account.
What Is a Personal Check Used For?
The most common uses for personal checks include:
- Rent and utility payments
- Purchase of everyday goods
- Legal agreements requiring documentary support
Certified Check
A certified check serves the same purpose as a personal check but is reviewed and guaranteed by the issuing bank, which verifies that the drawer has sufficient funds and holds them until the check is cashed.
A certified check provides certainty of available funds, making it a more secure method for making and receiving payments.
Cashier’s Check
Unlike a personal check, a cashier’s check is issued directly by the bank, offering greater security for the payee, as the bank is responsible for issuing and safeguarding the funds.
To obtain a cashier’s check, the drawer must visit a bank branch and pay the amount to be transferred. The bank then issues the check in the name of the payee, guaranteeing that it can be cashed using the institution’s own funds and not a personal account.
It is commonly used for high-value purchases such as homes and vehicles.
Money Order
While not strictly a check, it is a traditional payment method with similar functionality.
A money order is a financial instrument that allows funds to be sent via traditional mail using a certified check, which must be purchased and paid for by the drawer at an authorized location.
It allows secure money transfers without requiring a bank account.
How to Fill Out a Check in the U.S.
Before issuing this type of payment order, you must know how to do it properly. Below is an example of how to fill out a check easily, starting from step one:
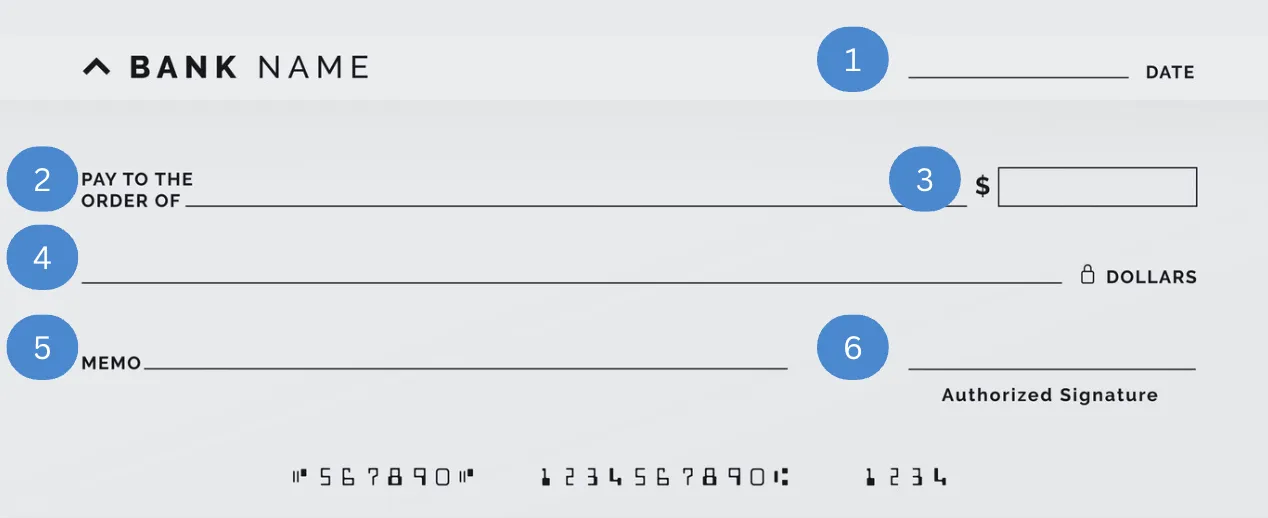
1. Write the Date
Remember that in the United States, the date format is mm/dd/yyyy.
2. Payee’s Name
Write the full name of the person to whom you are issuing the check, exactly as it appears on their official identification.
3. Amount in Numbers
Write the numerical amount clearly.
4. Amount in Words
Write the amount in words, including cents.
5. Add a Memo
You may include a note specifying the reason for the payment.
6. Sign the Check
Sign the check legibly in the space designated for the drawer.
7. Review the Information
Ensure that all information is accurate to avoid issues for the payee when cashing the check.
It is essential to complete checks legibly, without strike-throughs or corrections, as these may invalidate the document.
How to Correctly Write Numbers in Words on a Check
Writing amounts in words may be confusing when dealing with U.S. dollars. The following points should be kept in mind:
- Dollar amounts must be written in full words
- Cents must be written as fractions
- Avoid using dollar symbols or similar notations
- If there is leftover space at the end of the line, draw a line to prevent fraud
- For example, $1,000.75 is written as: One thousand and 75/100 dollars
Cash Checks and Manage Your Money Easily with Comun
As you can see, knowing how to fill out a check is useful for sending and receiving money in the United States. It is a reliable and accessible alternative if you do not have a banking account.
However, issuing and cashing a check can also require significant time and effort. That’s why you can skip the trip to the bank, avoid wasting time or money on gas, and cash your check directly from your phone using Comun—no lines, no questions, no complications.
Discover Comun, the only platform designed to serve the needs of immigrant communities in the United States, with support available in Spanish.
Why Choose Comun?
- Open your account with an official ID from your country
- Access a mobile app specifically designed for immigrants in the U.S.
- Make payments, receive your salary, and manage your finances
- Send money to your loved ones in LATAM for just a $2.99 transfer fee
Frequently Asked Questions
Still have questions about how to fill out a personal check? See our FAQ section.
What if I Make a Mistake Filling Out a Check?
If there are strike-throughs or inconsistencies in the amounts, the check must be voided and a new one used.
How Do I Void a Check?
Write the word VOID in large letters on the front of the check.
What Information Appears on the Back of a Check?
The back of the check contains the endorsement, meaning the payee’s signature for cashing the check.

International Money Transfers
The Role of Mobile Apps in the Money Transfer Revolution
8 min de lectura
In an era where digital innovation shapes every aspect of our daily lives, the financial sector hasn't been left behind. The introduction of mobile apps for managing finances and transferring money has revolutionized how we interact with our money, offering unprecedented convenience, efficiency, and security. This evolution isn't just about technological advancement — it's about breaking down barriers, making financial services more accessible, and fostering inclusion.
At the heart of this transformation is the rise of apps designed not just to facilitate financial transactions, but to seamlessly fit into users' lives, regardless of their background or financial status. At Común, we're leading the charge toward a more inclusive financial future. Through our innovative services, we aim to empower this vibrant demographic, highlighting the important role mobile apps play in the money transfer revolution and laying the groundwork for a discussion on the broader impact on society and the economy.
Unpacking the Impact of Mobile Apps on Money Transfers
The digital era has marked a major shift in how financial transactions happen, particularly money transfers. At the forefront of this revolution are mobile apps, which have transformed the traditional banking landscape. Mobile banking apps and money transfer services have simplified how we send and receive money. By linking bank accounts to mobile apps like Google Pay, Apple Pay, and Cash App, users can transfer funds instantly, pay bills, and manage their finances with just a few taps on their smartphones.
These apps offer features including international money transfers, multi-factor authentication for security, and the ability to monitor account activity in real time. However, they're often not inclusive of immigrant communities, with barriers to entry like language, documentation, and cost. At Común, we stand out because of our inclusive financial services aimed at helping grow the already considerable impact immigrants have on the U.S. economy, including:
- 62 million Latinos now live in the U.S.
- Latinos contribute $3.2 trillion to GDP.
- More than 1 million immigrants annually play a key role in addressing labor shortages.
Apps like Común embody the seamless integration of banking services into our digital lives, promoting financial planning and letting immigrants reach their financial goals more effectively. The arrival of mobile money transfer apps represents a significant leap forward in financial technology. By offering convenience, speed, and security, we at Común aren't just meeting users' immediate needs — we're also paving the way for a more inclusive financial ecosystem.
Security and Trust Measures in Money Transfer Apps
As money transfer apps become increasingly central to our daily financial activities, concerns about data security and fraud prevention have taken center stage. Financial institutions and app developers have prioritized security, implementing robust measures like multi-factor authentication, encryption, and fraud detection technology to protect user data and transactions.
Mobile banking apps now come with advanced security features designed to prevent unauthorized access and ensure money transfers are safe and reliable. Despite these measures, users are encouraged to exercise caution, such as not sharing sensitive information like bank account numbers or phone numbers, and using secure payment methods to mitigate risk. With Común, that's why our users know their money is safe:
- Their card is protected by VISA's guarantee against unauthorized charges.
- They can easily lock and unlock their card from the app.
- They receive instant notifications about all transactions so they can stay on top of charges and make sure there's no fraudulent activity.
Trust in money transfer apps is built on the foundation of strict security measures and financial institutions' ongoing efforts to improve user security. While fraud risk can't be completely eliminated, implementing comprehensive security protocols has made money transfer apps a safe, reliable option for financial transactions.
The Convenience of Money Transfers Through Mobile Apps
Looking ahead, it's clear money transfer apps will keep evolving, introducing new features and innovations that will further revolutionize the financial landscape. The ongoing development of money transfer apps promises exciting innovations, like greater integration with digital payment systems, better international transfer capabilities, and even more robust security measures. For example, here are some of the new features we're rolling out at Común:
- Send money to your loved ones in Latin America from the app without breaking the bank, including Mexico, the Dominican Republic, Panama, Guatemala, and more.
- More locations to add cash to your account, using a barcode at stores like CVS or 7-Eleven.
- Personalized 24/7 customer service, so you can reach us day or night.
- Transfers to other bank accounts.
- Check deposit through your app.
Future iterations may offer more sophisticated financial planning tools, personalized banking services, and seamless integration with other digital payment platforms. The potential for innovation in money transfer apps is limitless, with advances poised to redefine the efficiency, security, and accessibility of financial transactions. As our app continues to evolve, it will undoubtedly play a crucial role in shaping the future of money transfers, giving our diverse users even more control over their financial lives and opening new possibilities for global financial inclusion.
1. U.S. Census Bureau. "Hispanic Population to Reach 111 Million by 2060." U.S. Census Bureau, 2018, https://www.census.gov/newsroom/facts-for-features/2023/hispanic-heritage-month.html
2. Hamilton, Dan, Ph.D., Matthew Fienup, Ph.D., David Hayes-Bautista, Ph.D., and Paul Hsu, Ph.D. "2023 U.S. Latino GDP Report." Center for the Study of Latino Health and Culture, California Lutheran University and UCLA David Geffen School of Medicine, 2023.
3. Ward, Nicole, and Jeanne Batalova. "Frequently Requested Statistics on Immigrants and Immigration in the United States." Migration Policy Institute, March 14, 2023, https://www.census.gov/library/visualizations/2018/comm/hispanic-projected-pop.html
Financial Education
Digital Banks in the United States: How to Open Your Account Easily and Quickly
8 min de lectura
Digital Banks in the United States: A Clear Guide to Opening Your Account
Having access to affordable financial services with features that let you carry out multiple operations in one place is essential for immigrants living and working in the United States.
Digital banks are a comprehensive solution that combines financial management with mobile technology to streamline processes compared with traditional banks.
These features are especially beneficial for immigrants looking for an alternative to access services that are often less feasible through institutions with physical branches.
In this guide, we explain why you should consider integrating digital banking into your lifestyle, how to open an account, and options for digital banks in the United States.
What Is a Digital Account and How Does It Work?
A digital account is a financial product that operates entirely online through mobile applications and digital platforms (website), removing the need to travel to a physical location to complete banking operations.
Here are some benefits of digital accounts.
- Mobility and 24/7 access from anywhere: they are not limited to teller hours and allow transactions at any time and place.
- Convenience for making payments and international money transfers: they allow sending money within and outside the country quickly.
- Security and transaction control from the app: they include safeguards to prevent misuse of personal data and crimes such as fraud.
How to Open a Digital Account in the United States Step by Step
Opening a digital account is usually simpler than with traditional financial institutions—not only because it can be done from a mobile device, but also due to flexible requirements that allow immigrant communities to access financial services with the same quality standards.
These are the steps to open a digital account in the United States.
Required Documents
Unlike traditional banking services, you can open a digital account with documents you use day to day.
- Official identification from your home country (valid passport, consular ID, driver’s license).
- In some cases, proof of address in the United States.
Account Opening Process
Once you have your documents ready, follow these steps.
Step 1. Register on the digital platform/mobile app.
Go to the digital bank’s website or mobile application of your choice and enter your personal information to register.
Step 2. Identity Verification and Approval.
For security reasons, digital banks require an identity verification process that includes submitting an official ID, a selfie, and, in some cases, facial recognition.
Step 3. Account Activation and Access to the Mobile App.
Once the digital bank verifies your identity, you’ll receive an activation notice. Immediately afterward, you can access all services, set up direct deposits, send money in real time, and manage your finances.
U.S. Financial Platforms Recommended for Immigrants
If you’re wondering which digital platform for immigrants is ideal, there are several effective options, so it’s best to compare them and choose the one that best fits your expectations.
Común
Fees: Affordable fees for international money transfers to Latin America.
Ease of use: Open an account from a mobile device with a qualifying official identification from your home country.
Spanish support available: offers 24/7 customer service also available in Spanish via WhatsApp or the mobile app itself.
Mobile access: you have access to a mobile app for comprehensive financial management.
Zelle compatibility: not integrated.
Ally Bank
Fees: most accounts do not charge monthly maintenance fees. Approximately $20 for domestic wire transfers.
Ease of use: a 100% digital platform offering a mobile application and a website.
Spanish support: limited Spanish-language service.
Mobile access: service compatible with mobile devices.
Zelle compatibility: integrated.
Wells Fargo
Fees: maintenance and overdraft fees vary by account type.
Ease of use: offers mobile banking, online banking, and a digital assistant.
Spanish support: available.
Mobile access: full mobile features.
Zelle compatibility: integrated.
Revolut
Fees: charges a 1–3% fee for adding money via credit or debit card.
Ease of use: offers comprehensive, easy-to-use digital products.
Spanish support: you can change the app language, but there is no Spanish-language support.
Mobile access: fully available.
Zelle compatibility: not integrated.
Mercury
Fees: offers international USD transfers at no additional cost.
Ease of use: focused on corporate and tech companies.
Spanish support: not available.
Mobile access: fully available, but more focused on web dashboards.
Zelle compatibility: not integrated.
Cash App is another efficient financial platform—here we explain its benefits.
The Importance of Using Your Account Safely and Efficiently
Although digital platforms offer security measures to protect your assets, it’s always wise to keep the following recommendations in mind to reduce risks.
- Set up transaction notifications and security alerts: they help you stay on top of your activity and detect any suspicious behavior.
- Use strong passwords and enable two-step verification: this reduces the risk of falling victim to hackers.
- Review activity regularly and learn to identify suspicious alerts: check text messages and transaction notifications, and report any unrecognized charges immediately.
- Take advantage of the mobile app’s functionality for quick and reliable transfers: send and receive money easily within and outside the United States.
Discover Común, the Financial Option for Immigrants
In this article, we presented a practical alternative to traditional institutions so you can decide which digital bank in the United States fits your needs.
Común is not a bank, but a digital platform, it offers a mobile app and a debit card that work together to provide a service ideally for the immigrant community.
You can open an account with qualifying official identification from your home country and a mobile device to access the financial service you deserve.
Open your account with Común and start sending, receiving, and withdrawing money.
Frequently Asked Questions (FAQ)
If you still have questions, see the section below.
Can I open a digital account without a Social Security Number?
Unlike traditional banks, digital accounts often have more flexible requirements, and it may be possible to open one with a qualifying official identification from your home country and, in some cases, proof of address in the United States.
Are digital banks in the U.S. safe?
Yes, digital banks in the United States have security measures such as two-step verification and encryption. It’s advisable to apply all possible security measures, such as using a strong password and enabling notifications.
Immigration
What is an immigration sponsor? 4 requirements to be a sponsor in the U.S.
8 min de lectura
For immigrants in the United States, finding a legal way to remain in the country indefinitely can be a long and confusing process. That’s why it’s important to know all the alternatives to help pave the way toward lawful permanent residence.
Getting a sponsor is a path that can help you regularize your immigration status in the United States. A sponsor is a person who assumes legal and financial responsibility for someone who is in the process of regularizing their documents in the country.
Below, we explain in detail what a sponsor is, the income table to sponsor a family member in 2025, and all the forms and documents needed to formalize this process.
What does it mean to be a sponsor in the United States?
In simple terms, a sponsor is a person who takes on legal and financial sponsorship of someone who is in the process of obtaining an immigrant visa or a Green Card.
It’s a measure by which the U.S. Government, through USCIS, ensures the sponsored person will not become a public charge, since sponsorship entails the sponsor’s financial and legal responsibility.
During this process, some terms can be confused and are worth clarifying—namely sponsor and petitioner.
- Petitioner: the person who files the initial application with USCIS.
- Sponsor: the person who provides financial and legal support for the immigrant. If the petitioner doesn’t meet the requirements, a joint sponsor can be added.
On the other hand, there are two relevant forms you should know during this process.
- Form I-864 (Affidavit of Support):
This form is generally used for permanent resident visas, employment-based visas, or family-based Green Cards for immediate relatives.
- Form I-134 (Declaration of Financial Support):
This form is required for temporary or nonimmigrant visas—for example, a tourist or fiancé(e) visa.
4 requirements to be a sponsor in the U.S.
These are the requirements your sponsor must meet to proceed:
- Be a U.S. citizen or lawful permanent resident.
- Be at least 18 years old.
- Live in the United States (have a domicile there).
- Meet the minimum income requirements.
Regarding income requirements, sponsors must meet the minimums set by the Department of Health and Human Services (HHS), which requires household income above 125% of the federal poverty guideline.
Household size includes the sponsor, their spouse, dependent children, and the sponsored immigrant.
Below is a comparative table with the minimum figures by household size.
| Household size | For sponsors on active duty in the U.S. Armed Forces sponsoring a spouse or child | All other sponsors | Alaska | Hawaii |
|---|---|---|---|---|
| 2 | $21,150 | $26,437 | $33,037 | $30,400 |
| 3 | $26,650 | $33,312 | $41,637 | $38,312 |
| 4 | $32,150 | $40,187 | $50,237 | $46,225 |
| 5 | $37,650 | $47,062 | $58,837 | $54,137 |
| 6 | $43,150 | $53,937 | $67,437 | $62,050 |
| 7 | $48,650 | $60,812 | $76,037 | $69,962 |
| 8 | $54,150 | $67,687 | $84,637 | $77,875 |
| Each additional person | $5,500 | $6,875 | $8,600 | $7,913 |
If the sponsor does not meet these minimum incomes, you can turn to a joint sponsor or a household member.
It’s also important to consider some special cases.
- Sponsors with TPS (Temporary Protected Status): cannot be sponsors because they are not permanent residents.
- Humanitarian parole: not eligible to be sponsors unless they obtain permanent residence.
- Armed Forces: U.S. citizens serving in the Armed Forces have more flexible income minimums to sponsor immediate relatives.
What are a sponsor’s responsibilities and how long do they last?
To formalize sponsorship, the sponsor must sign an affidavit committing to provide legal and financial support.
Sponsor’s legal obligations
By signing the affidavit of support, the sponsor commits to providing the financial resources necessary so the sponsored person does not become a public charge.
If the immigrant receives public assistance, such as Medicaid, the U.S. Government may require the sponsor to reimburse those funds.
Duration of sponsorship
Sponsorship has no fixed duration, but it can end when:
- The immigrant adjusts status and obtains permanent residence.
- The immigrant accrues 40 quarters of work and proves it to Social Security.
- The immigrant permanently leaves the country.
Cases where sponsorship does not end
In marriage-based sponsorship, divorce does not terminate the sponsor’s obligations. The same applies if the parties stop living in the same household.
5 documents and forms you need to be a sponsor
Finally, it’s essential to know the documents needed to formalize sponsorship and to assess your sponsor’s eligibility.
Form I-864 or I-134, as applicable
This form serves as an affidavit in which the sponsor commits to meeting their economic and legal obligations to the sponsored person.
There is no fee to file these forms. Unless filed from outside the U.S. through the National Visa Center, in which case Form I-864 costs $120.
Proof of citizenship or permanent residence
The sponsor must present documents proving U.S. citizenship or lawful permanent residence—for example, a passport, Green Card copy, or naturalization certificate.
Tax returns or proof of income
You must provide the most recent annual tax return (Form 1040) and proof of income.
Employer letter, if needed
An employer letter may also be required to confirm the sponsor’s position, salary, and length of employment.
Proof of U.S. domicile
The sponsor must show a U.S. domicile and residence there. Deeds or utility bills can serve as proof.
Organize your finances in the U.S. with Común
Throughout this article, we reviewed in detail what a sponsor is—a person who assumes legal and financial responsibility for an immigrant—as well as the minimum income table and required documents.
Even with a sponsor’s support, it’s important to continue legalizing your situation in the country and to obtain steady work and income.
To that end, it’s vital to manage money well and have fair financial services suited to you.
Discover all the benefits of Común, the financial platform created for immigrants!
- Open your account with qualifying official ID from your country of origin.
- Use the mobile app available in Spanish, transparent and easy to understand.
- Send remittances to LATAM countries with clear and competitive fees.
Open your Común account today and organize your personal finances with clarity and security.
Frequently Asked Questions (FAQ)
If you still have questions, consult our FAQs.
Can I be a sponsor if I don’t have sufficient income?
If your income does not reach 125% of the Poverty Guidelines, you can look for a joint sponsor who must meet the same requirements—per the Federal Poverty Guidelines published annually by the Department of Health and Human Services (HHS).
What happens if the immigrant receives public benefits?
The primary sponsor and joint sponsor are responsible for reimbursing the Government for any public assistance the sponsored immigrant receives.
Living in the United States
What is the best health insurance in the United States? Complete guide
8 min de lectura
What is the best health insurance in the United States?
Having health coverage is essential to ensure you receive care when you need it. It’s also a way to invest in your future by preventing large out-of-pocket expenses from costly procedures.
There are many health insurance options in the U.S., so there isn’t a single “best” plan—what’s best depends on your needs and budget.
Although access to healthcare is a basic need, enrolling in a plan can be confusing for immigrant communities.
Below you’ll find a comparison of the main health insurance options in the U.S., key evaluation criteria, and answers to frequent questions—so you can choose the best option to protect you and your family.
Factors to consider when choosing health insurance
Before choosing a plan, carefully assess your personal and family needs, as well as benefits, medical terms, and the features of each option.
Key points to keep in mind before signing anything.
- Coverage level.
Some plans cover only basic services, while others offer comprehensive coverage including hospitalization, specialist visits, and prescription drugs. Review your medical needs (and your family’s) to gauge the right level.
- Monthly premium cost. Coverage level affects the monthly price. Make sure the amount is sustainable for your long-term budget.
- Deductibles and copays.
You must understand both before enrolling. The deductible is what you pay out of pocket before your plan starts paying; the copay is the fixed amount you pay each time you use a covered service.
- Provider network.
Check that the plan includes a robust network of hospitals and clinics near your home or work, so you can access care when needed.
- Eligibility requirements.
As an immigrant in the U.S., note that some plans require certain immigration status, state residency, and/or income qualifications.
- Additional benefits.
Also review extras such as preventive care, mental health, wellness programs, and maternity coverage.
Remember: a low price doesn’t automatically mean the best option—it must fit your (and your family’s) specific needs.
Health insurance options in the United States
The U.S. health insurance market includes a range of public and private plans.
Here are key options you should know.
- Health insurance via the Marketplace (ACA).
Plans under the Affordable Care Act (ACA) are offered through federal/state marketplaces. They must include essential health benefits and prescription coverage. Income-based subsidies may lower costs.
- Medicaid.
A public program for people with low incomes; covers children, pregnant people, people with disabilities, and families. Usually no premium; some services may have small copays.
- Medicare.
A program for people 65+ (and some with disabilities). It’s divided as follows:
- Part A: hospital inpatient.
- Part B: medical services. Part C: Medicare Advantage (private insurers) that can bundle extra benefits.
- Private plans and employer-sponsored insurance.
Private coverage can be purchased directly or provided as an employer benefit. These plans vary in coverage levels and typically include broad provider networks.
Comparison of common health insurance options
Remember: beyond a policy, a health plan is protection for you and your family—take the time to choose well.
Here’s a comparative table of major U.S. health plan types.
Plan type
Who it serves
Approx. costs
Primary coverage
ACA Marketplace
People without employer private insurance.
Costs vary by coverage; income-based subsidies can lower premiums.
Essential benefits: hospitalization, preventive care, prescriptions, emergency care, etc.
Medicaid
People with low incomes.
Generally no premium; small copays for some services.
Broad medical and hospital coverage nationwide.
Medicare
People 65+ and certain disabilities.
- Part A: per-period deductibles.
- Part B: monthly premium ~$185.
Hospital and medical services coverage
Employer-sponsored private insurance
Workers (and dependents) covered by employers.
Costs include premiums, deductibles, and copays—vary by plan.
Hospital, specialists, prescriptions, emergency services, etc.
Don’t forget: as an immigrant in the U.S., verify eligibility rules related to immigration status.
Manage your finances in the U.S. with Común
In this article, we covered what to consider before enrolling, the different plan types, and how to compare benefits.
There’s no single “best” plan—it depends on your personal and family needs and budget.
Beyond medical costs, immigrants need safe financial services to manage their money.
Común is the financial platform you’ve been looking for—discover the benefits!
- Checking account with clear, competitive fees.
- International money transfers at affordable costs.
- Mobile app available in Spanish that accepts 100+ official IDs for account opening.
- Debit card for everyday purchases and payments.
Open your Común account today and manage U.S. medical bills simply and transparently.
Frequently Asked Questions (FAQ)
If you still have questions, see the section below.
What is the number-one health insurer in the U.S.?
Among the top U.S. health insurers are:
- Cigna.
- Aetna.
- Blue Cross Blue Shield.
- Ambetter.
- Anthem.
Is health insurance mandatory in the U.S.?
It isn’t required at the federal level, but some states—like California and New Jersey—mandate coverage or impose penalties.
Where can I officially compare health plans?
Official sources include: HealthCare.gov (federal Marketplace to view/compare/enroll); Finder.Healthcare.gov (to find off-Marketplace plans); Medicare.gov (compare Medicare plans by ZIP code).

Instant payments
Safe and fast ways to send money without a bank account
8 min de lectura
Did you know it is possible to send money without having a bank account? The lack of access to financial services is a problem that negatively affects the quality of life of thousands of immigrant workers in the United States.
For example, according to a recent survey, the rate of the Latino community in the United States without a bank account dropped from 15% to 10% over the last two years. However, it remains high compared to the national average of 4.5%.
While having a bank account facilitates financial transactions such as transfers, in-store payments, and online purchases, there are now alternatives that allow you to access banking services without needing an account.
Below, you will discover how to transfer money from one card to another without an app or bank account, as well as the safest and simplest methods available to you.
Sending Money Online
Not having a U.S. bank account is not an obstacle to sending money domestically or internationally, as there are methods widely used among immigrant workers who regularly send remittances and conduct other transactions using prepaid cards and cash payments.
International Money Transfer Providers
This is one of the most popular ways to send money without a bank account due to the accessibility, variety of payment methods, and broad coverage typically offered.
International money transfer providers are companies that specialize in facilitating money transfers from one country to another. The key features of these services include:
- Specialization in international money transfers, unlike traditional banks, which have certain limitations, such as high commissions, unfavorable exchange rates, extensive delivery time, and participation of intermediaries that increase costs.
- More affordable fees.
- Various sending methods.
- Multiple Money Transfers Locations
How to Send Money Without a Bank Account Through an International Transfer Platform
Comun allows you to send money to your loved ones for a modest transfer fee starting at USD 2.99 up to the applicable limits. It is very simple; just follow these steps:
1. Open your account with Comun; it will only take a few minutes!
2. Choose the most convenient delivery method for your recipient, such as cash pick up at a physical store like Oxxo, Grupo Elektra, 7 Eleven, and more.
3. You may also send money directly to a bank and have it picked up at one of its branches.
4. Track the delivery directly in your Comun mobile application.
Comun is an excellent option for our community, as it provides Spanish-language service, which is highly appreciated by the immigrant community. Open your account today and start sending money without complications.
What Information Do You Need to Send Money Without a Bank Account?
To send money without a bank account, you only need the following information about your recipient:
- Full name of the recipient, exactly as it appears on their official ID.
- Recipient’s phone number.
- If the transfer is made to a bank account, you will also need:
- Recipient’s address.
- Bank account number, depending on the receiving country.
P2P Services
P2P (peer-to-peer or person-to-person) services allow immediate money transfers between individuals without intermediaries. These options are useful for everyday needs such as paying rent, shared services, splitting transportation costs, and sending money to your relatives in the US or internationally.
How to Send Money Without a Card Using P2P Services
- Choose a reliable provider, such as Cash App or Venmo.
- Enter the recipient’s phone number in the mobile app.
- Confirm the transaction and track it.
Sending Money by Mail
Other alternatives involve sending a cashier’s check, a certified check, or a money order through the postal service.
Cashier’s Check
This type of check is issued with the bank’s funds. The customer must pay in cash or directly from their account, and the check is made payable to the recipient.
Certified Check
This check is issued using the customer’s funds. The issuer must have a bank account so that the bank can verify the availability of funds. The recipient may cash the check directly at a bank branch.
Money Order
Another way to send money without a bank account is by using a money order, which is a type of prepaid payment order. To do so, you will need to:
1. Go to a post office or authorized retailer, such as USPS or Walmart, to purchase a money order.
2. Write the beneficiary’s name in the “pay to the order of” section.
3. Write your name in the “purchaser” section.
4. Sign in the space designated for the purchaser, generally on the front of the document.
5. Keep the receipt with the serial number.
6. Pay the amount to be sent plus applicable service fee.
7. Send the money order via regular or certified mail.
8. Write the recipient’s address in the center of the envelope and the sender’s address in the upper left corner.
9. Purchase a postage stamp at the post office and attach it to the envelope.
10. Drop off the envelope at the post office.
The recipient may cash the money order at an authorized branch upon presenting valid personal identification.
The downside of this alternative is that it takes longer to arrive, as it relies on a traditional mailing method.
Sending Money With Prepaid Load
There are other options available to send money without a bank account, such as prepaid cards and mobile applications.
Reloadable Prepaid Cards
Reloadable prepaid cards function similarly to debit cards, with the main difference being that they are not linked to a bank account. They also allow you to pay for services and make online purchases.
To send money using a prepaid card, you only need to:
1. Identify an international money transfer service that supports prepaid cards, such as Western Union or MoneyGram.
2. Select your preferred provider and choose the prepaid card option on their website.
3. Enter the recipient’s information, making sure it is compatible with the selected platform.
4. Confirm the transfer and pay the amount plus the applicable service fee.
Done! The recipient will receive the money on the prepaid card as if it were a bank transfer.
Mobile Wallets/Applications
Lastly, you may opt for mobile wallets or applications that offer money transfer capabilities. Some examples include Cash App, Venmo, and Remitly, which provide access to an mobile app you can use to send and receive money.
These applications do not require a bank account and are user-friendly. Some also offer physical cards that function similarly to debit cards.
7 Essential Tips for Sending Money Without a Bank Account
1. Verify the Identity and Information of the Recipient
Ensure that the recipient’s information, such as name, account number, or phone number, is entered correctly. Any discrepancies could prevent the recipient from collecting the funds.
2. Compare Fees and Exchange Rates
Each provider has its own rates depending on the receiving country, amount, and exchange rate. Remember, with Comun you do not pay excessive fees, and you ensure your family receives more for less.
3. Know the Sending Limits
Some platforms have sending limits that should be considered before selecting a service. For instance, Western Union has a daily limit of USD 7,499, while Cash App allows up to USD 7,500 per week for verified accounts.
4. Keep All Receipts and Reference Numbers
Even though these methods are secure, it is important to keep receipts and reference numbers in case a clarification or issue arises.
5. Use Reputable and Secure Services
It is essential to ensure that you use a trusted service. Check online reviews and verify that the provider has an official website and/or physical offices.
6. Be Cautious of Scams
Unfortunately, scams are common around financial services. No legitimate institution will request passwords or verification data. Always access official websites. If in doubt, visit an authorized branch.
7. Consider Delivery Time
Most options allow you to complete transfers in minutes, but some may take several days. Consider this before choosing your preferred service.
Frequently Asked Questions
Is it safe to send money without a bank account?
Absolutely. Comun is backed by leading financial institutions to protect your funds up to the applicable limits. Additionally, you can track your transfer directly through the Comun mobile app.
How much does it cost to send money without a bank account?
Comun offers a transfer fee starting at USD 2.99, regardless of the amount you send up to the applicable limits. Your first transfer is commission-free!
How long does it take for the money to arrive?
Cash is typically available within approximately 1 hour at the selected store or bank branch.
What documents do I need to send/receive money without an account?
You need the full name of your recipient, and they must present official identification.

International Money Transfers
Money Transfers: From Traditional Methods to Digital Innovations
8 min de lectura
Money transfers have evolved from traditional methods like checks and money orders to instant digital solutions. With Común, most international remittances arrive within minutes, with no need to visit a branch.
The financial evolution of money transfer methods from traditional practices to digital innovations marks a crucial shift, revolutionizing how we think about and manage our finances in our bank accounts and beyond. This transition isn't just about technological advancement — it reflects a fundamental shift in user expectations, security standards, and global connectivity, especially in international money transfers and seamless bank account integration.
Accelerating Transactions: The Digital Revolution in Money Transfers
The rise of digital platforms and money transfer apps has transformed the speed and accessibility of transactions. Where bank transfers between financial institutions once took days to complete, digital innovations now enable instant money transfers, letting users transfer money around the world in just a few business days or even instantly. This monumental shift in convenience lets users send money or transfer funds from one bank account to another 24/7, without the traditional visit to a bank or credit union.
These changes encapsulate the journey from traditional methods like bank transfers and bank-to-bank transfers to the digital innovations now dominating our financial ecosystem. As we continue exploring these developments, it's clear that ways of transferring money — from using a debit card for instant transfers to leveraging payment app capabilities like Google Pay and Apple Pay — aren't just evolving, they're being redefined for a new era of global connectivity and digital empowerment, making money transfer apps an indispensable tool in our daily lives.
Navigating International Money Transfers: Considerations
Additionally, the rise of mobile apps, from money transfer services like Cash App to full banking apps, has democratized access to financial services. These platforms offer user-friendly interfaces that simplify the money transfer process, whether sending money abroad through international transfers or managing domestic transfers between checking and savings accounts within the same bank. This broadens financial inclusion, letting even those with a basic savings account or checking account participate easily in bank transfers and person-to-person payments.
It's equally important to have a solid understanding of the regulatory framework surrounding international money transfers. This includes being aware of anti-money laundering (AML) laws and the various transfer limits imposed by different countries. These regulations are designed to prevent financial crimes and ensure the security of cross-border transactions. Following these laws not only helps avoid legal complications, but also ensures your transactions process without unnecessary delays.
In addition to choosing the right service and understanding regulations, it's also helpful to be aware of the exchange rates offered by different services. Exchange rates can significantly affect the final amount received on the other end, especially for large transactions. It's also crucial to consider delivery times, especially if the transfer is time-sensitive. While some services can transfer funds almost instantly, others may take several business days. This can be particularly important in emergency situations or when making payments with strict deadlines.
Exploring Different Money Transfer Options: Wire, ACH, and Beyond
Digital advances have also introduced a new level of security and transparency to money transfers. With modern encryption and authentication technologies, including features like fraud detection, financial transactions — whether internal transfers, external transfers, or even online payments for online purchases — are safer than ever.
Money transfer apps have become a safe haven for personal finances, offering real-time transaction tracking and ensuring that transferring money — from a linked bank account via Automated Clearing House (ACH) transfers or direct deposit — stays secure and straightforward. ACH transfers stand out for domestic efficiency and cost-effectiveness, ideal for regular payments like salaries and bills. Additionally, traditional methods like checks, cash deposits, and money orders retain their usefulness for specific scenarios, offering tangible options in a predominantly digital world.
The Rise of Person-to-Person (P2P) Money Transfer Apps
P2P transfer apps have fundamentally transformed how we exchange money, making transactions as simple as sending a message. These apps let users send funds directly to others, using just an email address or phone number, eliminating the need for intermediaries. Among the many options available, several apps have gained prominence, each standing out for its distinctive features.
For example, some apps are celebrated for their integration with social networks, enhancing the social aspect of money transfers. Others prioritize security, offering advanced encryption and authentication methods to protect transactions. There are also apps designed to facilitate cross-border payments by simplifying the process of sending money internationally, offering competitive exchange rates and low fees. This diversity ensures there's a P2P transfer app suited to practically every need and preference, reflecting the dynamic, user-centered evolution of financial technology.
Decoding the Costs: Fees in Money Transfers
The rise of mobile apps, from money transfer services like Cash App to full banking apps, has democratized access to financial services. These platforms offer user-friendly interfaces that simplify the money transfer process, whether sending money abroad through international transfers or managing domestic transfers between checking and savings accounts within the same bank. This broadens financial inclusion, letting even those with a basic savings account or checking account participate easily in bank transfers and person-to-person payments.
Understanding the fees associated with money transfers is pivotal for managing your finances effectively and avoiding unexpected costs. The fee landscape for transfers can vary significantly, spanning service charges, transaction fees, and currency conversion fees, among others. Transparency around these fees is crucial — so it's essential to choose services that offer clear, straightforward information about all the costs involved.
Service charges and transaction fees are often the most visible costs associated with transferring money. These can vary widely depending on the provider and transfer method chosen. For example, traditional bank transfers might carry higher fees compared to online platforms or mobile apps. Currency conversion fees also play a significant role, especially for international transfers, where money needs to be exchanged from one currency to another. Some services build their profit into the exchange rate offered, making it less favorable than the market rate. This practice underscores the importance of scrutinizing the exchange rates provided, not just the explicit fees.
This approach not only helps you make informed decisions, but also helps avoid hidden charges that can add up. To minimize these costs, adopting strategies like selecting the transfer method best suited to your needs — considering factors like speed, destination, and amount — and diligently comparing providers to find the best rates and lowest fees can lead to significant savings. By prioritizing transparency and using cost-minimizing strategies, users can navigate the complexities of money transfers more confidently and economically.
Send abroad with peace of mind with your Común account¹
Open your account in 3 minutes!
Conclusion
In conclusion, the shift from traditional methods to digital innovations in money transfers represents a significant advancement in financial management. Digital platforms and money transfer apps have revolutionized how we send money, providing unprecedented convenience, speed, and security. From seamless bank account transfers to the global reach of international money transfers, these digital solutions offer a full range of services that meet our diverse financial needs.
By emphasizing transparency, these platforms minimize hidden fees, making it easier than ever to manage our savings and checking accounts. Additionally, innovations like instant transfers and robust fraud detection technology have made money transfer apps a reliable option for consumers. As we continue embracing these digital advances, the essence of mastering money transfers lies in leveraging technology to enhance our personal finance capabilities, ensuring we can navigate the complexities of modern financial transactions with confidence and cost-effectively.
How have money transfers changed over time?
From checks, money orders, and bank transfers that took days, to mobile apps that process payments and remittances in minutes.
What advantages do digital transfers have over traditional methods?
Greater speed, real-time tracking, and the ability to send money without leaving home. With Común, you can send a remittance from the app anytime.
Are traditional methods still useful?
Yes, checks and cash are still relevant in certain cases, such as when the recipient doesn't have a digital bank account.
Frequently asked questions
Why are digital transfers faster than traditional ones?
Because they use real-time processing networks, instead of the multi-day cycles of traditional banking methods.
Do I need to visit a branch to send money with Común?
No, the entire process happens through the app, with no need to visit any physical location.
Are traditional methods like checks still valid?
Yes, they're still useful in certain cases, though digital apps tend to be faster and more convenient.
How fast does a remittance sent through Común arrive?
Most arrive within minutes, depending on the country and delivery method.
Can I track my transfer in real time?
Yes, the app shows you your transfer's status while it's being processed.
Is sending money digitally safer than by check?
Both methods have different protections; digital apps usually offer additional verification and encryption.

Community
Investment Basics for Immigrants in the U.S.
8 min de lectura
The Importance of Investing for Immigrant Families
Investing is one of the most powerful tools for building long-term wealth. For immigrant families in the U.S., understanding investment basics can make the difference between merely surviving and financially thriving. In this guide, we explain the fundamental concepts you need to know before you start investing.
What is investing?
Investing means putting money into assets with the goal of growing it over time. Unlike saving, which keeps money safe but with low returns, investing takes on some risk in exchange for the possibility of higher gains. The most common assets are stocks (ownership stakes in companies), bonds (loans to governments or companies), mutual funds (diversified portfolios), and real estate.
Key concepts you need to understand
Risk and return
The higher the potential risk, the higher the return can be. Individual stocks are more volatile than government bonds. Index funds offer a balance between reduced risk through diversification and historically positive long-term returns.
Diversification
Do not put all your eggs in one basket. Spreading investments across multiple assets, sectors, and geographies reduces the risk that one bad investment will ruin your entire portfolio.
Compound interest
Compound interest is the phenomenon of earning interest on previously earned interest. An investor who starts at age 25 will reach retirement with significantly more money than someone who starts at 35, even if they contribute the same monthly amount.
Investment horizon
The length of time you plan to hold your investments affects which assets to choose. For goals more than 5 years away, you can take on more risk. For short-term goals, prefer more conservative options. Never invest money you need in the short term.
Frequently asked questions about investing for immigrants in the U.S.
Can an immigrant invest in the U.S. stock market?
Yes. Most brokers in the U.S. allow non-citizens to invest, including permanent residents and people with work visas (H-1B, L-1, etc.). Some brokers also accept non-residents. To open an investment account, you generally need a tax identification number (SSN or ITIN) and a U.S. bank account.
How much money can I start investing with in the U.S.?
Most modern brokers like Fidelity, Charles Schwab, and Robinhood have no minimum amount to open an account. You can buy fractional shares starting at $1. What matters is not the starting amount but consistency—investing $50-100 per month regularly produces better results than irregular large sums thanks to dollar-cost averaging (DCA).
What is an index fund and why is it recommended for beginners?
An index fund is a fund that tracks the performance of a stock market index such as the S&P 500. Instead of selecting individual stocks, you invest in a “basket” of the 500 largest companies in the U.S. They are popular for their low cost (fees of 0.03-0.20%), automatic diversification, and historical returns that have outperformed most active managers over the long term.
What happens to my investments if I move back to my country?
You can usually keep your U.S. investment account while abroad, although some brokers restrict nonresident accounts. When you sell, you will pay capital gains taxes in the U.S. (and possibly in your country of residence). Consult a tax advisor before leaving the country to plan the transition properly.
Is a 401(k) account the same as a regular investment account?
No. A 401(k) is a tax-advantaged retirement account generally offered by your employer—the contributions reduce your taxable income now, and the money grows tax-deferred until retirement. A regular investment account (brokerage account) does not have special tax advantages but also no withdrawal restrictions. Both are complementary tools for building wealth.
What are the most common mistakes beginner investors make?
The most common mistakes are: investing money you need in the short term (investments require a 3+ year horizon), selling when the market drops out of panic, not diversifying (putting everything in one company or sector), paying unnecessarily high fees, and not investing because you are “waiting for the perfect moment.” Discipline and consistency matter more than perfect market timing.

Financial Education
What Is Financial Freedom and How Can You Achieve It?
8 min de lectura
What Financial Freedom Means and How to Achieve It
Financial freedom is more than a simple definition — it's a state of life many aspire to reach. It's the ability to cover all your financial needs without being tied to a conventional job. Imagine a world where your decisions aren't dictated by your financial obligations, but by your desires and passions. That's financial freedom.
In a constantly changing world, where the retirement age keeps rising and working conditions keep getting more challenging, financial freedom has become an essential goal. It provides not just economic security, but also a better quality of life, freedom of choice, and the chance to pursue personal passions and projects without restrictions.
Steps to Achieve Financial Freedom
Cutting Expenses: Taking Control of Your Personal Finances
Before you can save or invest, it's essential to understand where your money is going. Keeping a detailed record of your expenses lets you identify areas where you could potentially save. Adopting a frugal lifestyle doesn't mean sacrificing your quality of life — it means making more informed decisions about your spending.
To stay on top of your personal or family finances, it's important to create a budget and review it regularly. A budget helps you categorize your income and expenses over a period of time — usually once or twice a month — so you can identify your necessary expenses versus your discretionary or luxury spending. This makes it easier to figure out which expenses you can cut to improve your financial stability.
One of the biggest problems with not having a budget is falling into the most common mistake that keeps us from achieving financial freedom: going into debt — spending more than you earn and constantly being "in the red," a hole that's hard to climb out of as debt grows over time. The secret is living below your means: rather than adopting a lifestyle that reflects your salary or your wants, the advice from many financial experts is to live frugally and spend less than you earn. This lets you save and invest more over time.
Saving: The Foundation of Financial Freedom
Saving isn't just about setting money aside — it's a mindset and a discipline that lays the groundwork for a healthy financial life. Dave Ramsey, a well-known financial expert, has developed a series of principles and steps that have helped millions find their way to financial freedom.
Dave Ramsey is famous for his "Baby Steps," a series of seven steps designed to guide people toward financial freedom. The first step — and perhaps the most crucial — is saving $1,000 as a starter emergency fund. This fund acts as a cushion against the unexpected, keeping people from going into debt over surprise expenses.
"Not having an emergency fund is an emergency in itself" is a popular Dave Ramsey saying, and if you've ever been in an unexpected situation that required funds you didn't have on hand, you can probably vouch for how true that is. And while $1,000 doesn't sound like a lot compared to the cost of many emergencies, the point of this emergency fund is to push a person to take that first step and start building financial discipline.
Investing: Generating Passive Income
Warren Buffett, one of the most successful investors in the world, has always emphasized the importance of investing in what you know and understanding the intrinsic value of your investments. His investing philosophy, which has been the cornerstone of his success, is built on several core principles that can serve as a guide for those seeking financial freedom:
- Invest in what you know: Buffett has always been a strong advocate for investing in companies and sectors you fully understand. If you can't explain in simple terms how a company makes money, it might not be the best fit for your portfolio.
- Look for value, not price: Buffett distinguishes between the price and the value of a stock. While price is what you pay, value is what you get. His approach is based on identifying companies that are undervalued relative to their true intrinsic value and that have long-term growth potential.
- The market is volatile, but don't get swept up in the panic: Buffett compares the stock market to an unpredictable neighbor named "Mr. Market." Some days Mr. Market is optimistic and offers high prices, while other days he's pessimistic and offers bargains. Rather than getting carried away by Mr. Market's emotions, Buffett suggests staying calm and focusing on the intrinsic value of your investments.
- Long-term investing: Buffett isn't chasing quick gains. Instead, he looks for companies with lasting competitive advantages and holds them for decades. His famous quote, "my favorite holding period is forever," reflects his long-term investing approach.
- Reinvesting dividends: One of the strategies behind Buffett's success is reinvesting dividends. By reinvesting dividends, you benefit from compound interest, which can lead to exponential growth in your investment over time.
Passive income — whether through dividends, rental income, or online businesses — is essential for financial freedom. This income, which doesn't require constant direct involvement, lets your money work for you, generating regular cash flow that can support a lifestyle free from the constraints of a conventional job. Warren Buffett's investing philosophy centers on patience, education, and a deep understanding of investments. By adopting these principles and focusing on generating passive income, you can chart a path toward true financial freedom.
Conclusion
Financial freedom is an ideal that goes beyond simply accumulating wealth — it's the manifestation of a balanced life where our decisions aren't dictated by economic pressures, but by our true passions and desires. Through the discipline of saving, wisdom in investing, and understanding our finances, we can move closer to this ideal. The teachings of experts like Dave Ramsey and Warren Buffett offer us a clear roadmap toward this goal. At the end of the day, financial freedom isn't just about money — it's about living a life with purpose, security, and genuine independence. It's a journey that requires commitment, education, and constant action, but the rewards, both tangible and intangible, are invaluable.
International Money Transfers
How long does an international money transfer take? Business days, time zones, and type of transfer
8 min de lectura
If you need to send money to your home country from the United States, it is important to consider how long an international money transfer takes. In general, the processing time for this type of operation is usually 1 to 5 business days.
However, this depends on several factors, such as the payment system, the banks involved, the currency conversion, and the holidays in between.
That is why it is important to know the different types of international money transfers available, the advantages and disadvantages of each one, and, of course, how long they take to deliver the money to its destination.
Below, we offer you a guide to answer those questions so you can send money home as quickly and safely as possible.
What is an international money transfer and how long does it usually take?
First of all, an international transfer is the sending of money to a bank entity located outside the country of the originating account. Unlike domestic transfers, international transfers involve additional banking systems, such as the SWIFT networks, which can increase costs and processing times in many cases.
There are several factors that influence the total time an international money transfer takes, but in general, it takes 1 to 5 business days.
For example, one relevant aspect that influences this is the system used, whether SWIFT or SEPA, which have different conditions and characteristics.
SWIFT Transfers
The SWIFT system is the largest network: it connects thousands of traditional banks worldwide to send money from one country to another through secure mechanisms.
Characteristics of the SWIFT system
- In general, it takes 3 to 5 days to complete money transfers.
- The involvement of intermediary banks is common, which can generate additional fees.
- It is useful for sending money in different currencies, although it implies disadvantages in time and costs.
- To use this system, check the SWIFT code of the receiving bank.
SEPA Transfer
On the other hand, the SEPA system is focused on international money transfers within the European Union.
Characteristics of the SEPA system
- International money transfers are usually completed in 1 business day.
- Fees are more affordable compared to the SWIFT system.
- This system works exclusively in the SEPA area, and for transactions in euros.
As you can see, both the SWIFT and SEPA systems are useful for making international money transfers safely. Although for those living in the United States, the latter is not recommended due to its geographic limitations.
Here is a comparison table:
| SWIFT | SEPA | |
|---|---|---|
| Time | 3 to 5 business days | 1 business day |
| Cost | Expensive, due to the involvement of intermediaries | Affordable |
| Geographic availability | Worldwide | Exclusively in Europe |
Factors that influence the time of an international money transfer
The time an international money transfer takes is not fixed. It varies according to the type of transfer and other elements involved in the operation.
Here is what you need to know to estimate how long it will take for your money to reach your loved ones.
Payment system
So far, we have presented the SWIFT system, which takes 3 to 5 business days, and SEPA, which is generally reflected the next business day.
In addition, there are ACH (Automated Clearing House) transfers, which are a more common system in the U.S., characterized by being a more economical option, although the process usually takes 2 to 3 business days.
Intermediary banks
There are cases in which the financial institutions participating in an international money transfer do not have a direct relationship with each other, so they need to involve intermediary banks. This, in addition to increasing costs, lengthens transfer times, because it makes the operation take longer than usual.
Cut-off times and business days
Another essential aspect is the cut-off time banks have for executing transactions. If you send money after this time, the operation is processed the next business day.
Also, do not forget to take into account the holidays of both the sending country and the receiving country, which also extend the waiting time.
Currency conversion and destination country
When sending money from the United States to your home country in Latin America, the bank will need to make the corresponding currency exchange and apply an exchange rate. This also usually adds time to the international money transfer process.
Security verifications and compliance controls
Banks often carry out security checks to prevent money laundering and fraud, especially when large amounts are involved.
What information do you need to make an international money transfer?
You are almost ready to start sending money abroad. But first, it is very important that you make sure you have the necessary information to process this type of transfer. Otherwise, the transfer could be rejected or take longer than usual.
Sender’s information
You will need to provide your basic personal information: full name, bank account, official address, and phone number.
Beneficiary’s information
It is also essential to provide the details of the person who will receive the money: full name, recipient’s account number, address, and country of origin.
Bank codes
- IBAN: for transfers within the European Union.
- SWIFT/BIC code: for transfers in most of the world, including the United States.
Amount and currency
Indicate the amount of the transfer and the currency in which it will be received.
Purpose or payment reference
Finally, indicate the purpose of the transfer. It may be: maintenance payment, family support, family savings, etc.
How can you speed up an international money transfer?
We know that sending money to your family and loved ones is very important, which is why it is vital that you avoid mistakes and bad practices that could delay your transfers even more.
- Verify that the beneficiary’s details are complete and correct: check that your recipient’s details are written as they appear on their official identification.
- Make the transfer before the bank’s cut-off time: remember that doing it after this time causes the transfer to be processed the next business day.
- Avoid sending money on weekends or holidays: try to send money on business days to avoid delays.
- Consider using specialized remittance services with faster processes: there are alternative services that offer better conditions than traditional banks.
Make your international money transfers quickly and safely with Común
This time, we learned that international transfers are money transfers made from one country to another, and there are several factors involved in the time they take to be completed.
Are you looking for a way to send money home without complications?
Discover Común, the digital platform that connects you with your family through a service that understands your needs.
Make your first international money transfer, forget about hidden fees, and get transparent rate so your loved ones receive more for less.
Frequently Asked Questions (FAQ)
If you still have questions, check our FAQ.
What is the average time of an international money transfer?
Approximately 1 to 5 business days.
Why do some transfers take longer than usual?
It depends on the system used, the involvement of intermediaries, the currency exchange, and other factors. That is why you should make sure to check the estimated time before sending your money, to see if it fits your timing and needs.
Can I send money on weekends?
Yes, but it will be processed the next business day in most cases.







Thousands of immigrants are already achieving more with their money. You can too.
Comun is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank; Member FDIC. The Comun Visa® Debit Card is issued by Community Federal Savings Bank, pursuant to a license from Visa U.S.A Inc. and may be used everywhere Visa Cards are accepted.
Comun is a fintech company and not a bank or licensed money transmitter.
* Results may vary. For a complete list of eligible IDs and application requirements, follow this link.
^ No minimums, no maintenance fees. ATM or transfer fees may apply. See app for fee details.
‡ Direct deposit funds are typically available when we receive the payment file, up to two days before the scheduled payment date. This early availability is not guaranteed.
** A service provided by Service UniTeller, Inc. Service UniTeller, Inc. is licensed in all states that require a license. Remittance fees start at $2.99 but may vary. Please check the app for more details. Comun Inc. may earn revenue from the conversion of foreign currencies.
† Funds in your account are FDIC insured up to $250,000 by ownership category through Community Federal Savings Bank (CFSB), Member FDIC, in the event CFSB fails.


