
Immigration
Benefits of Having an ITIN in the U.S. for Non-Citizens
The ITIN is obtained through IRS Form W-7 along with identity and foreign status documentation. A passport is the only.
8 min read


How to get an ITIN
The ITIN is obtained through IRS Form W-7 along with identity and foreign status documentation. A passport is the only document that satisfies both requirements on its own. The process takes between 7 and 11 weeks.
1. It allows federal tax filing
The ITIN allows you to file tax returns with the IRS, including claiming credits such as the Child Tax Credit and the Earned Income Tax Credit.
2. Access to credit and financial services
Some banks and credit unions accept an ITIN as an alternative ID to an SSN for opening accounts. Platforms like Común do not require either an SSN or an ITIN.
3. It facilitates business operations
For entrepreneurs, the ITIN is vital for filing business taxes and applying for an Employer Identification Number (EIN).
4. It supports residence and immigration processes
Consistently filing taxes with an ITIN can demonstrate good moral character, a factor considered in some immigration cases.
5. It helps establish identity and secure income
In the absence of an SSN, the ITIN is recognized by financial institutions and government agencies as a valid identification number.
6. Access to state services and benefits
In some states, the ITIN allows access to a driver’s license, health insurance, or in-state college tuition rates.
7. It protects against tax identity theft
Using the ITIN consistently links your tax data to your identification number, reducing the risk that someone files a return in your name.
Frequently asked questions about ITIN benefits
What is the ITIN used for in daily life?
The ITIN allows you to file tax returns with the IRS, claim tax credits such as the Child Tax Credit, open bank accounts at institutions that accept it, and in some states access services such as driver’s licenses or in-state tuition. It is the tax identification number for those who do not qualify for an SSN.
Does the ITIN give me the same rights as an SSN?
No. The ITIN is exclusively for tax purposes. It does not authorize you to work legally in the U.S., does not generate Social Security credits, does not provide automatic access to federal benefits such as Medicare or unemployment, and is not equivalent to an SSN for most government procedures. It is a tool for tax inclusion, not immigration status.
Does filing taxes with an ITIN affect me in an immigration process?
In general, filing taxes with an ITIN can be beneficial in immigration processes because it demonstrates a history of tax compliance and “good moral character,” one of the criteria evaluated in some adjustment-of-status cases. However, the impact varies by case — consult an immigration attorney before using it as an immigration strategy.
Can I open a bank account with an ITIN?
Some banks do accept an ITIN. Bank of America and certain local banks have specific programs for ITIN holders. However, many large banks require an SSN. Alternatives like Común do not require either an SSN or an ITIN — they accept a passport, consular ID, or other Latin American IDs for immediate account opening.
Does the ITIN help me access credit in the U.S.?
Yes, partially. Some credit card issuers and lenders accept an ITIN. Certain mortgage programs (ITIN loans) allow you to buy a home without an SSN. Building credit history with an ITIN is possible, although more limited than with an SSN. Credit built with an ITIN generally does not automatically transfer if you later obtain an SSN.
How do I apply for an ITIN if I have never had one?
You submit IRS Form W-7 along with identity and foreign-status documentation — a passport is the only document that satisfies both requirements on its own. You can mail it with your tax return, go in person to an IRS Taxpayer Assistance Center, or apply through an authorized Certifying Acceptance Agent (CAA), which is the fastest and safest method.
About Común
Común aims to support the Latino community in the United States. It offers a debit account that can be opened with more than 100 valid Latin American IDs and an app available in Spanish.
Visit Común's website or download the app for free to learn more about the full offer and applicable terms.
Olivia Rhye
Community Partner


Checking account
How to Identify Where to Deposit Cash
8 min de lectura
Depositing cash into your Común account is simple and convenient. Whether you prefer using your physical card at an AllPoint+ ATM or generating a barcode in the app, here is a step-by-step guide to help you understand both methods.
Using a Physical Card
Step 1: Wait for Your Physical Card
After opening your online bank account, your physical debit card will be mailed to your home. This usually takes 7 to 10 business days.
Step 2: Activate Your Card
Before you can use your card, make sure to activate it through the Común app. Your card must be active for any transaction.
Step 3: Locate an AllPoint+ ATM
AllPoint+ ATMs are part of a broad network of ATMs, perfect for cash deposits. Here is how to find one:
- Open the Común app.
- Go to the "Move Money" section.
- Use the map to locate the nearest AllPoint+ ATM. These machines are usually found at popular retail locations.
Step 4: Deposit Cash at an AllPoint+ ATM
Once you are at the ATM:
- Insert your activated card.
- Follow the on-screen instructions to deposit cash into your checking account. Please note that deposits can only be made into checking accounts, not savings accounts.
- Make sure your deposit is within the limits: up to $250 per deposit and up to $1,000 per day, including deposits and withdrawals.
Tip: If there are no AllPoint+ ATMs near you, do not worry. You can also deposit cash using a barcode at many other locations!
Using the Barcode in the App
Step 1: Generate a Barcode
Here is how to generate a barcode in the Común app:
- Open the app and go to the "Cash" section.
- Select the option to generate a barcode for deposit.
- The barcode will appear on your screen, ready to use.
Step 2: Find Locations That Accept the Barcode
To find a nearby location that accepts the barcode:
- In the "Cash" section, look for the list of participating locations.
- You can also use the map feature to find the nearest store.
Step 3: Using the Barcode
Take your barcode to a participating location and show it to the cashier. They will scan the barcode, allowing you to deposit your cash.
Important Details:
- Expiration: The barcode expires after 15 minutes, but you can generate as many as you need.
- Limits: Keep in mind the deposit limits that may apply when using the barcode method.
Troubleshooting ATM Transactions
Problems Depositing Money
When troubleshooting ATM transactions, especially problems depositing money, it is important to make sure you are using an AllPoint+ ATM, since these machines do not charge fees for deposits. Your physical card must be activated; if it is not, you can easily activate it from the app. Also, make sure you enter the correct PIN. If you do not remember your PIN, you can view it or change it in the app settings section. Verify that your deposit is within the limits, which are up to $250 per deposit and up to $1,000 per day. Finally, always select "checking account," since Común accounts are checking accounts, not savings accounts.
Problems Withdrawing Money
If you run into problems withdrawing money, first make sure you have enough balance by checking your balance in the app before making a withdrawal. Use an AllPoint+ ATM to avoid withdrawal fees, since other ATMs may charge a fee. Enter the correct PIN; if you do not remember your PIN, you can view it or change it in the app settings section. Verify that your withdrawal is within the limits, which are up to $250 per withdrawal and up to $1,000 per day, including deposits and withdrawals. If you continue having problems, contact us through the chat in your app for more help.
Alternative Deposit Methods
If you cannot find a nearby store to deposit cash, Común offers other options:
- Receive Money: Use apps like Zelle, CashApp, Venmo, or PayPal.
- Direct Deposit: Set up direct deposit with your employer.
- External Transfers: Send money to your Común account from an external bank or other financial institutions.
Additional Tips and Information
Fraud Prevention
Always keep your account number and PIN secure. Do not share this information with anyone to avoid unauthorized transactions.
Know Your Limits
Be aware of the deposit amount limits. For example, you can only deposit up to $250 per deposit and up to $1,000 per day. This helps you manage your funds and avoid any unexpected issues.
Use Común Features
The Común app provides a map to find the nearest ATMs and stores that accept barcodes for deposits. This feature helps you quickly locate convenient deposit points.
Stay up to date with the latest features and benefits offered by Común through the app, ensuring you get the most out of your online banking experience.
Cash Deposit Fees
Depositing cash at an AllPoint+ ATM has no fees, while other ATMs may charge a fee. Always check for possible fees before making a deposit.
Mobile Check Deposits
In addition to cash deposits, Común also supports mobile check deposits, adding more flexibility to the way you manage your money..
Conclusion
In short, depositing cash into a bank account is a practical decision driven by safety, convenience, possible earnings, financial management, and legal compliance. By understanding these reasons, people can make informed decisions about how to handle and manage their cash effectively, ensuring financial stability and growth.
Whether you use your physical card at an AllPoint+ ATM or a barcode in the app, depositing cash into your Común account is simple and convenient. Always make sure your card is activated, check nearby locations, and keep deposit limits in mind. With these steps, you will be able to manage your cash deposits effortlessly.
Do not worry, if there are no locations near you, you can also deposit with a barcode at many more locations! Visit Común for more details and get started with your deposits today.
By understanding the process and using the tools provided by Común, you will be able to handle your cash deposits effectively and ensure your funds are always accessible.
Community
Común: Digital Banking for Immigrants in the U.S.
8 min de lectura
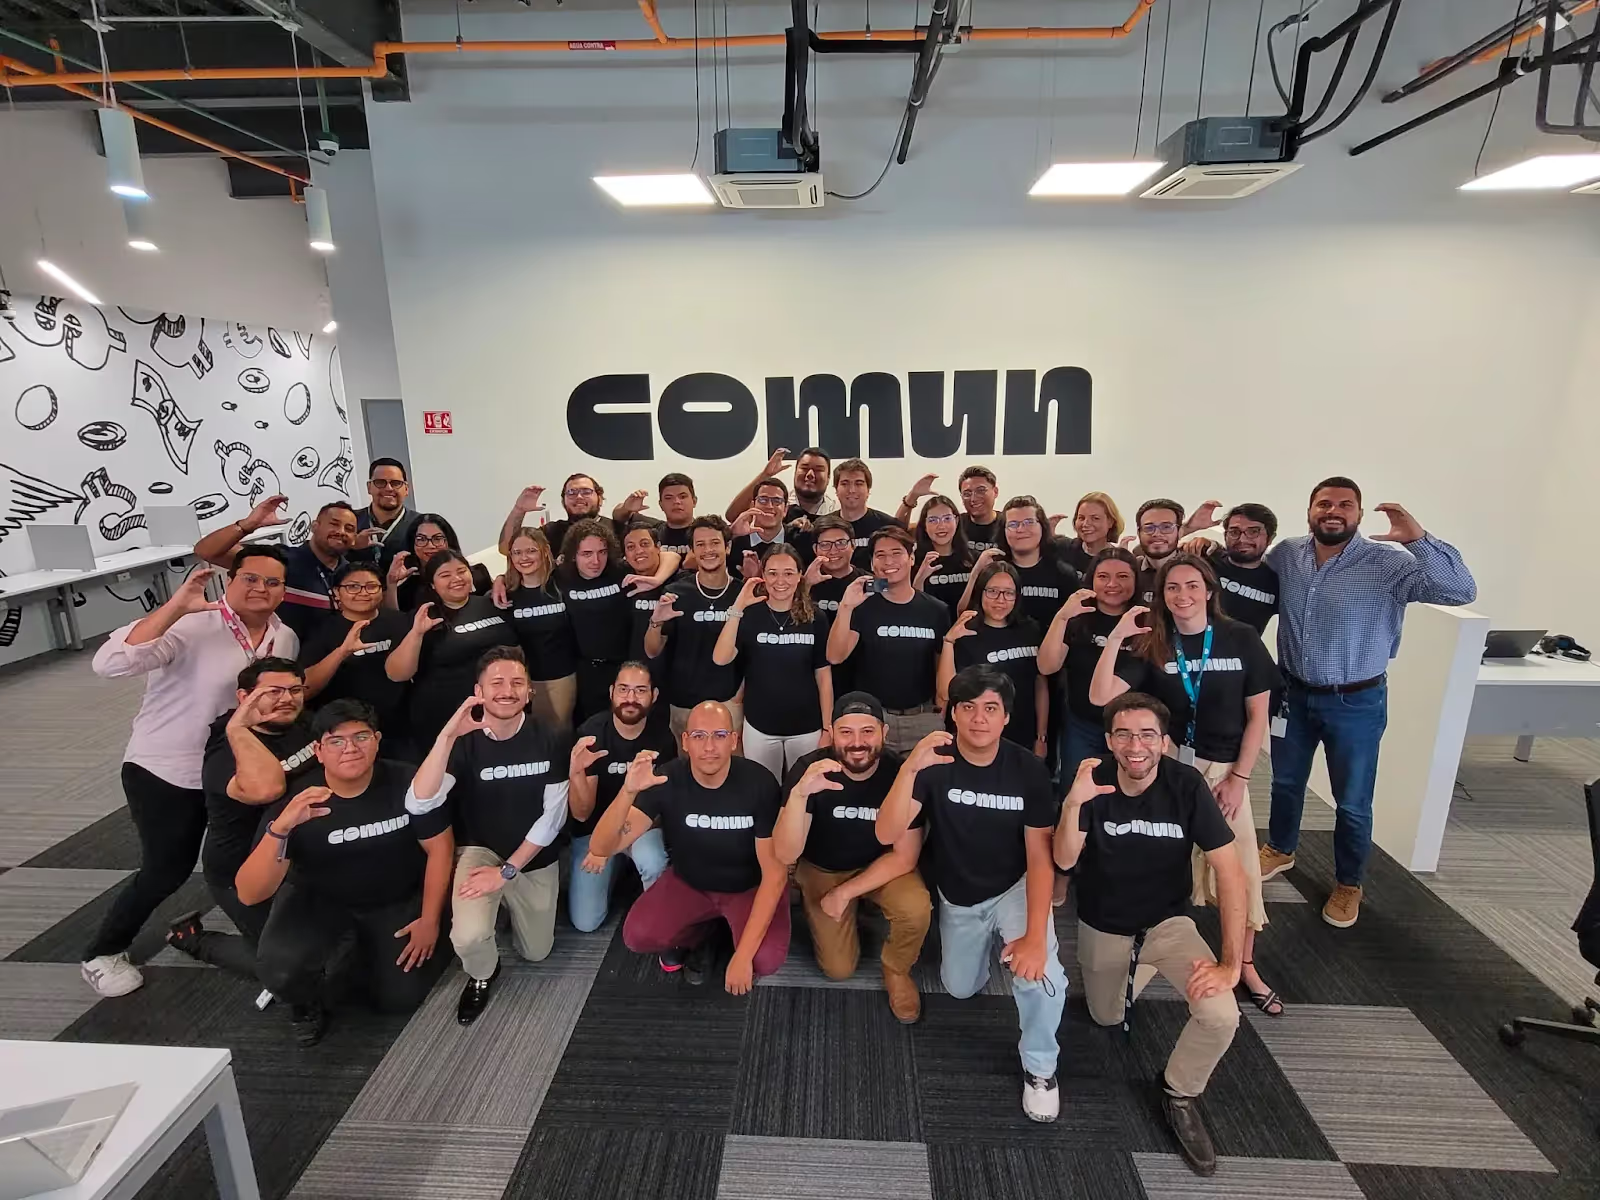
Común does not have branches, but it has a team that supports its customers 24 hours a day, 7 days a week, from the comfort of their homes, in three different languages.
Building a better future for immigrants in the U.S. is a core principle of Común’s mission. Accessible and easy-to-understand banking options are a key part of the immigrant journey. However, the options are scarce.
Complex, cumbersome, and expensive options are the norm. Activities that may seem trivial and intuitive to those born in the U.S. are overwhelming and confusing for a newly arrived immigrant. Everything from setting up direct deposit with an employer to sending money home, making payments for goods and services, or understanding how to build a credit score seems too complex for anyone who has never had to do this in the U.S., let alone at all.
Hidden fees and costly charges add another layer of stress when starting a financial life in the U.S. Between minimum account balances, monthly fees, overdraft charges, large check deposit fees, extortionate international transfer fees, and everything else, maintaining and using a bank account in the U.S. can be expensive. For manual laborers, this can represent a significant percentage of their wages.
The physical locations of traditional banks can also be scarce in some areas. Since opening a bank account or depositing a check or cash into the account must be done at a branch, this is a significant burden for someone living in a remote area. Many immigrants, sometimes working on remote farms or factories, live miles away from the nearest bank branch. Transportation costs to those branches add to the already high fees of using and maintaining an account.
Even if the banking services provided were more intuitive, digital, and lower cost, another major barrier remains. Obtaining the necessary documentation to open a bank account can also make access to fair and simple financial services difficult. Immigrants fortunate enough to have work authorization still need to gather important documentation that is not always available to them. For those who have come to the U.S. seeking asylum or better work opportunities through a more unconventional path, the documents required to open an account are often prohibitive.
Building a 100% digital banking platform to solve the issues mentioned above is part of what Común seeks to achieve because we believe in helping unlock social mobility. But a digital, low-cost, and intuitive platform is not enough. To navigate this process, immigrants need help, and help is best found in a Community that understands them when they need it most.
That is why not only our customers are part of our Community, but also the people who help them 24 hours a day, 7 days a week through our app, social media, WhatsApp, or by phone. Beyond solving an immediate problem, the support provided goes further. It teaches and educates, empathizes, and strives to foster a sense of Community among people who understand them, in terms they comprehend and in the language they speak. This is the core of true digital community banking. Our team helps them set up direct deposit, get refunds for charges they disagree with, and everything else.
At Común, the first step in this journey has already begun. Our team in Mérida, Mexico, is part of our Community and the one we seek to serve. They are an extension of our mission and our digital platform, and a necessary ingredient in unlocking social mobility for millions of immigrants in the U.S.
Financial Education
5 requirements to renew your Mexican passport in the U.S.
8 min de lectura
Everything you need to know to renew your Mexican passport
Living far from your country carries a set of family, social, and legal responsibilities—from keeping up with loved ones to complying with immigration laws.
Mexican community is one of the largest in the United States,so it’s essential for immigrants living there to renew their passports to avoid potential issues that could affect their stability.
If you hold a Mexican passport and have recently discovered your Mexican passport is about to expire, this guide is for you! Below we explain, step by step, how to renew it from the United States and why keeping it valid matters.
Why keeping your Mexican passport valid matters
The passport is one of the most important official documents for anyone; it serves not only as identification but also as the document that allows you to enter and leave countries.
Why is it important to renew your passport?
- Avoid travel delays
Before you buy a ticket or pack your bags, check the expiration date on your passport and your family’s. Remember that airlines generally require at least 6 months’ validity.
- Handle consular procedures
A passport is essential for immigration procedures you may need in the U.S., such as visas and permanent residence processing.
- Serves as official ID
A passport is one of the documents most often required to identify yourself and to complete important banking and legal procedures such as opening a bank account, getting a Social Security Number, or a driver’s license.
- Avoid legal issues
An expired passport could cause problems with U.S. immigration authorities and, in turn, jeopardize your ability to remain in the country.
Who can renew their Mexican passport in the United States?
The following documents are basic requirements to obtain a new passport:
- Previous passport, even if expired.
- Mexican birth certificate.
- Valid official ID.
- CURP (Unique Population Registry Code).
However, the renewal process varies slightly depending on the applicant’s profile.
Adults (18 and over)
Adults can complete the Mexican passport renewal process directly at a Mexican consulate in the U.S.
In most cases you must book an appointment in advance via the MiConsulado portal.
Minors
For minors, renewal involves a few additional steps.
Additional documentation:
- School ID or proof of enrollment.
- Proof of address for the parents.
Both parents must attend the appointment and sign the authorization. If one cannot attend, a notarized authorization is required.
People with disabilities
People with disabilities can also renew their Mexican passport under the following criteria.
Additional documentation:
- Medical certificate proving the disability.
- If the person cannot legally sign the authorization, parents or guardians must appear with identification proving their status.
Note that some Mexican consulates offer priority services for these needs.
5 requirements and documents needed to renew your Mexican passport
Before booking a consular appointment, make sure you meet the requirements to renew your Mexican passport.
1. Previous passport
- For minors, include the authorization signed by both parents.
- In cases of theft or loss, a special declaration is required.
- Passports issued before 1995 may not be digitized in the Foreign Affairs Ministry database, so additional documentation may be required.
2. Certified birth certificate
This is a basic document proving Mexican nationality. Make sure you obtain a certified copy issued by the Civil Registry.
3. CURP
The Unique Population Registry Code (CURP) is essential to confirm personal data.
4. Required payment
Note the latest update to Mexican passport government fees.
Fees (validity — estimated consular fee): • 3 years — $99.00 • 6 years — $133.00 • 10 years — $203.00
Passport validity
Consular fee in U.S. dollars
3 years
$99.00
6 years
$133.00
10 years
$203.00
You must pay the fee on the day of your appointment. Commonly accepted methods: cash, debit or credit card, and money order. You’ll generally receive your passport the same day, unless there’s an issue with the documentation or information must be verified.
5. Original identification
You may present an INE card, driver’s license, High-Security Consular ID, or school IDs.
Renewal can only be done at authorized Mexican consulates. While you may book at any Mexican consulate in the U.S., some may have operational restrictions.
How to book your appointment and what to expect on renewal day
Step 1. Book the appointment
Booking an appointment is essential to renew your passport.
- Via the website citas.sre.gob.mx.
- Via WhatsApp at 1-424-309-0009.
Step 2. Prepare your documents
Make sure you have all required documents. If you have children or care for a person with disabilities, remember you’ll need the additional documentation.
Step 3. Attend the appointment
Arrive on time and present your documents in order. Once processed, you’ll receive your passport.
Additional tips to renew your Mexican passport without setbacks
An expired passport could cause easily avoidable setbacks and difficulties. Below are some tips to help you keep your official documentation up to date.
- Check your passport’s validity in advance before planning trips: don’t forget to take the expiration date into account. Consider setting reminders on your phone 6 months before it expires.
- Make copies of all important documents: it’s essential to keep backups of your official documents. Also consider digitizing them for convenience.
- Use only the SRE’s official channels to book appointments; if you have questions, contact the SRE’s official channels only.
- Arrive early to your appointment and organize your documents in a folder: avoid day-of delays that could slow your process.
- Verify the payment method and fees before your appointment: if you’re not sure whether your preferred payment method is accepted at the consulate, ask directly before your appointment.
Común: the next step after renewing your passport
Throughout this article, we showed how and why renewing your Mexican passport matters to avoid issues with U.S. authorities and delays in your plans. We also explained the application process, requirements, and practical tips.
Just as a valid Mexican passport opens the door to international travel and access to official services, a checking account with Común opens the door to financial stability in the United States.
Why choose Común as your financial ally?
- Open your checking account at Común with your passport or another qualifying official ID from your country of origin.
- Mobile app available in Spanish, intuitive and secure.
- Remittance transfers to Mexico and Latin America in a simple way and with clear, competitive fees
Común is the platform that understands the needs of people living between two countries. Your passport connects with your own identity, and Común connects your money with your family across borders.
Open your checking account with Común today and start sending money from the U.S. easily, safely, and affordably!
Frequently Asked Questions (FAQ)
If you still have questions, see this section.
Can I pay for my Mexican passport renewal with a credit card at the consulate?
Yes, credit card is an accepted payment method.
How do I renew my Mexican passport if it was stolen or lost in the U.S.?
You must present a theft or loss report issued by the local police and complete the loss declaration form at the consulate.
What documents do I need to renew my Mexican passport in the United States if I am a minor?
Mexican birth certificate, official ID, official IDs for both parents or guardians, and their in-person presence at the consulate.
Do I need a specific immigration status to renew my Mexican passport in the U.S.?
The passport is a right of Mexican citizenship, and you do not need to have any specific U.S. immigration status.
Financial Education
What is a certified check and how does it work?
8 min de lectura
What is a certified check and how does it work?
Certified checks are a common form of payment for thousands of immigrants living in the United States, especially for major purchases such as rent payments, buying a car, and legal settlements.
However, it is not always clear why the certification process matters and how it differs from other types of checks.
A certified check is a physical payment order that has been reviewed in advance by a financial institution to ensure there are sufficient funds in the issuer’s bank account. This is the fundamental reason it’s considered a safer form of payment than a personal check.
Below, we explain in detail what a certified check is, how it works, and why it’s important to understand the differences from other types of checks.
What is a certified check?
A certified check is a type of check with guaranteed funds, since the issuing bank has verified the money exists in the checking or personal account.
This makes it a safer form of payment than personal checks, because the bank sets aside the amount to be paid so it can be collected by the payee.
How is a certified check issued?
Issuing a certified check is a straightforward process you can complete directly at the financial institution of your choice.
- The customer requests the check
The account holder must go to a bank and request a certified check, specifying the payee and the amount.
- Customer identification
You must present an official ID to verify that you are the holder of the savings or checking account from which the funds will be drawn.
- The bank freezes the amount in the account
The bank then certifies there are sufficient funds to cover the check and freezes them to ensure the payee can cash it.
- Signature certification
You must sign the check before finishing the process so the bank can confirm the signature matches the one on file.
Affixing the certification stamp
Finally, once the bank has verified the funds and the signature, it places a certification stamp to document completion of the process.
Differences between a certified check and a cashier’s check
A cashier’s check is another way to make secure payments using a physical instrument. In this case, the bank branch issues the check after receiving the customer’s payment, so the funds come from the bank itself.
Below is a comparison between a cashier’s check and a certified check.
Cashier’s check
Certified check
Security
High; the bank verifies sufficient funds and places a hold for the payee.
Very high; the check is backed by the bank and does not depend on the issuer’s account.
Cost
At some banks they have no cost at others up to approximately $15.
Depends on the bank; typically $10–$20.
Issuance time
At the branch, after funds are verified.
Immediate.
When is a certified check typically required?
A certified check is commonly used for significant transactions or large amounts. This gives the recipient assurance that funds are available.
- Paying an apartment security deposit.
When finalizing a lease or purchasing an apartment, the landlord or agent may request payment via certified check to guarantee funds.
- Buying a used car.
Whether dealing directly with owners or dealerships, a certified check can be a suitable option because of the security it provides.
- Closing an important contract or legal settlement.
For example, to pay fees, settlements, or indemnities, certified checks provide security for both parties.
- For tuition or school fees.
Some educational institutions accept certified checks as a form of payment, especially for international or first-time payments.
Do you know what to do if a check is stolen or lost? We explain it here!
Practical tips for using certified checks safely
While certified checks are among the safest payment methods due to the bank’s verification process, there are still fraud attempts using forged documents.
With this in mind, keep these tips in mind to avoid becoming a victim of check fraud.
How to know if a check has funds and avoid scams
- Verify with the issuing bank.
Call the bank directly and provide the check number, account holder, and amount; ask them to confirm authenticity and that funds are guaranteed. Make sure you call the bank’s official number, not the one printed on the check.
- Be alert if you receive an overpayment check.
A common scam is sending a check for more than the amount due and asking for the difference in cash. Confirm the check’s validity with the bank before proceeding.
- Wait for the check to clear before handing over any goods.
Clearing can take 3–10 days. Make sure the funds have fully settled and are not just on hold.
- Avoid accepting checks from unknown parties.
Whenever possible, accept checks only from people you trust. If you must take a check, follow the security measures above.
Manage your money securely with Común
In this article we explained what a certified check is, how it’s issued, how it differs from cashier’s checks, and how to use this payment method safely.
While certified checks can be a good payment option, a checking account in the U.S. is a much more secure and practical way to manage money.
Meet Común, your financial ally in the United States!
Send, receive, and cash money within and outside the United States. Our platform lets you move your money easily, quickly, and securely. You need a qualifying official ID from your country of origin to get started.
Open your account with Común today and discover a financial platform tailored to you.
Frequently Asked Questions (FAQ)
Where can I get a certified check in the United States?
You can request certified checks at financial institutions such as banks, credit unions, and some digital banks.
How much does it cost to get a certified check at the bank?
The cost depends on the bank but is typically between $10 and $15.
What other types of checks exist in the U.S. besides certified checks?
Other types of checks in the United States include: Money order; Personal check; Cashier’s check.
Financial Education
How to Call Guatemala from the USA in 2025
8 min de lectura
How to Call Guatemala from the United States Easily and Affordably
One of the main wishes of Guatemalan immigrants arriving in the U.S. is to stay in frequent contact with loved ones through efficient and affordable telecom services.
However, confusion is common when dialing because of the codes needed to connect U.S. phone service to Guatemala.
In reality, once you have the right codes, calling Guatemala from the U.S. is quite simple—and this article shows you how.
Below you’ll learn the step-by-step dialing process with examples, plus money-saving options and tips to avoid extra charges.
3 Basic Steps to Dial Guatemala from the USA
First, know the U.S. international exit code—it goes at the very start of the number.
Here are the basic steps to dial Guatemala.
1) Dial 011 from a landline or “+” from a mobile
The U.S. international exit code is 011 (landlines). On mobile phones, use the “+” sign.
2) Dial 502 - Guatemala’s country code
The next step is to enter Guatemala’s code, which is 502. Every country has a code that identifies it internationally to connect telephony services.
3) Dial the 8-digit local number (landlines and mobiles)
Finally, dial the Guatemalan phone number exactly as it is, whether you’re calling from a landline or a mobile phone.
Keep in mind that the first digit of a Guatemalan phone number indicates whether it’s a landline (2) or a mobile (5).
Here you have some dialing examples:
- Landline, Guatemala City: 011 + 502 + 2 ### ####
- Mobile, metro area: 011 + 502 + 5 ### ####
Guatemala Prefixes: Identify Landline vs. Mobile
As mentioned in the previous section, the first digit of a Guatemalan number indicates whether it’s a landline or mobile. It also indicates the carrier and the region.
Therefore, before calling Guatemala, identify this digit so you know exactly what type of number you are dialing.
Below is a table with the prefixes to make them clearer.
Number type
Prefix
Example from U.S.
Landline, Guatemala City
2
011 502 2 ### ####
Landline, Metro Area
6
011 502 6 ### ####
Landline, rest of country
7
011 502 7 ### ####
Mobile, major operators
3, 4 or 5
011 502 3 ### ####
Modern Ways to Save on Calls to Guatemala
It’s very likely that the distance between the United States and Guatemala will make you need to place phone calls more often to keep up with your family and friends.
Fortunately, today’s international calling rates are very different from what they were a decade ago, when callers were charged per minute. That made it difficult to maintain constant communication between families living in different countries.
Today you can choose telecommunications services with far more affordable calling plans, as well as apps that work over a Wi-Fi connection.
Here are some options to call Guatemala easily.
VoIP applications
Nowadays, the easiest way to make calls—both domestic and international—is through VoIP (Voice over IP) apps, which connect over Wi-Fi or mobile data.
One of the most popular is WhatsApp, which has millions of users worldwide and, in addition to calls, also offers video calls, text messages, voice notes, and frequent updates.
Other similar apps available include FaceTime, Google Voice, and Skype.
International plans from phone carriers
Although apps offer a very affordable way to stay in touch, one downside is that call quality depends on the internet connection.
If you need consistently smooth calls, an international plan is ideal. Major U.S. carriers like Verizon, AT&T, and T-Mobile offer international plans with affordable rates.
Prepaid calling cards
Prepaid cards are a more traditional option. They’re best if you won’t be in the U.S. for long, since you only pay for the minutes you need and don’t rely on a phone plan or internet connection.
Bundles with minutes to Guatemala included
Some providers offer low-cost bundles with minutes to call Guatemala. Examples include Rebtel and Boss Revolution.
Tips to avoid extra charges on your calls
The cost of calling Guatemala can end up higher than expected. Here are some tips to keep in mind.
Common dialing mistakes when calling Guatemala:
- Not dialing the full international prefix.
If you don’t dial the U.S. exit code 011 + Guatemala’s country code 502, the call may not connect or may be billed as a domestic call.
- Adding a 0 to mobile numbers.
In Guatemala, both landlines and mobiles have 8 digits, so there’s no need to add a leading 0.
- Mixing up the first digit.
The first digit indicates landline vs. mobile. If you confuse it, the call may fail or connect using another country’s code.
- Not checking your plan or rates before calling.
Carefully review plan costs and pick the best rates to avoid overpaying.
Tips for immigrants who need to call Guatemala
- Use apps over Wi-Fi whenever possible.
Mobile apps over Wi-Fi are the most affordable option—just make sure you have a strong signal for smooth calls.
- Confirm the Guatemalan number has 8 digits.
Guatemalan numbers always have 8 digits, whether landline or mobile.
- Compare rates across providers.
Take time to compare rates and benefits—unlimited minutes, included data, social apps, etc.
Stay connected with your family in Guatemala with Común
Ready to call your loved ones in Guatemala? Remember you need the U.S. exit code, the country code, and the local number. You also learned practical tips to make the process easier.
Staying in touch across borders is essential to bridge the distance. Another way to care for your loved ones is by sending money through fair, secure services.
Discover all the benefits of Común!
- Checking account with clear, competitive fees.
- International money transfers.
- Común’s mobile app available in Spanish and English that accepts 100+ official IDs for account opening.
- Debit card for everyday purchases and payments.
Open your Común account today and complement your calls with a fintech platform that connects and supports you in the U.S.
Frequently Asked Questions (FAQ)
If you still have questions, see the section below.
What happens if I don’t dial 011 or “+”?
Your call won’t be recognized as international, so it may be treated as local or fail with an error.
What’s the cheapest option to call Guatemala?
Internet-based apps like WhatsApp are the most economical option.
How can I tell if a Guatemalan number is landline or mobile?
Landlines start with 2 and mobiles with 5.

Financial Education
Money Transfer Scams: How to Recognize and Avoid Them
8 min de lectura
Understanding Money Transfer Scams
Money transfer scams are fraudulent schemes designed to trick people into sending money or sharing sensitive financial information. These scams can happen through various channels, including emails, phone calls, text messages, and even social media. Scammers often pose as legitimate entities, like banks, government agencies, or trusted companies, to earn the victim's trust and prompt immediate action.
Common Tactics Used in Money Transfer Scams
- Impersonation: Scammers often pose as credible entities to make their requests seem legitimate. They may pretend to be from your bank, a government agency, or even a friend or family member in trouble.
- Urgency and Fear: Scammers create a sense of urgency or fear, insisting immediate action must be taken. This tactic pressures victims into making hasty decisions without proper verification.
- Emotional Manipulation: Many scams exploit the victim's emotions. For example, a scammer might claim a loved one is in trouble and needs money right away.
- Phishing: Scammers use emails or messages that appear to be from legitimate sources to steal personal information, like login credentials or bank details.
Impact of Money Transfer Scams
The consequences of falling victim to a money transfer scam can be severe:
- Financial Loss: The most direct impact is losing money, which can range from a few dollars to substantial sums.
- Identity Theft: Scammers can use stolen information to commit identity theft, leading to further financial and legal complications.
- Emotional Stress: Victims often experience significant stress and anxiety after realizing they've been scammed.
Understanding these tactics and their potential impact is the first step to protecting yourself from money transfer scams. Learn about Común account security
Types of Scams
Money transfer scams come in several forms, each with unique methods for deceiving victims. Below are two common types of scams to be aware of:
They Send You a Check in Exchange for a Return Payment
In this scam, the victim receives a check, often for a large amount, with instructions to deposit it into their bank account. The scammer then asks the victim to send part of the money back to them or to a third party, usually under the pretext of covering fees, taxes, or another made-up reason.
How It Works:
- Receiving the Check: The scammer sends a check that looks real, often claiming it's an overpayment, a prize, or some other reason.
- Depositing the Check: The victim deposits the check into their account. Initially, the bank may credit the amount to the victim's account, making it appear the funds are available.
- Return Payment Request: The scammer then asks the victim to send back a portion of the funds before the check fully clears.
- Returned Check: Eventually, the check is returned as fraudulent, leaving the victim responsible for the full amount, including the money they sent to the scammer.
Warning Signs:
- Receiving a check from an unknown source.
- Instructions to send money or gift cards in return.
- Pressure to act quickly before verifying the check's authenticity.
They Ask for a Confirmation Code Before Withdrawing Funds
In this scam, the scammer poses as a legitimate company or financial institution and contacts the victim, asking them to provide a confirmation code to verify their identity or complete a transaction.
How It Works:
- Initial Contact: The scammer contacts the victim, often through a phone call, text message, or email, posing as a representative of a trusted entity.
- Confirmation Code Request: The victim is asked to provide a confirmation code, usually sent to their phone or email.
- Unauthorized Access: Once the victim provides the code, the scammer uses it to access the victim's bank account or complete an unauthorized transaction.
- Withdrawal of Funds: The scammer withdraws funds from the victim's account, leaving them with financial losses.
Warning Signs:
- Unexpected requests for confirmation codes or personal information.
- Calls or messages claiming urgent verification needs.
- Requests to share codes sent to your phone or email, especially if you didn't initiate any transaction.
By understanding these specific types of money transfer scams, you can better protect yourself and recognize warning signs when they come up.
How to Avoid Money Transfer Scams
Avoiding money transfer scams requires vigilance and following certain best practices. Here are some essential tips to help protect you from falling victim to these fraudulent schemes.
Never Send Money to Someone You Don't Know
One of the most important rules to remember is to never send money to someone you don't personally know. Scammers often pose as legitimate businesses or people in urgent need, but once the money is sent, it's nearly impossible to get it back.
Key Points:
- Verify Identity: Always verify the identity of the person or organization requesting the transfer. Use official contact information to confirm their legitimacy.
- Question the Request: Be skeptical of any request to send money, especially if it comes from someone you haven't dealt with before or don't know in person.
- Consult Trusted Sources: Before sending money, check with friends, family, or financial advisors for a second opinion.
Remember: Money Transfers Are Like Sending Cash
Money transfers are a convenient way to send money, but they're also irreversible and can be easily exploited by scammers. Treat money transfers with the same caution you'd use with cash transactions. Learn how to make international transfers
Key Points:
- Understand the Risks: Money sent via transfer is money that's gone. Unlike credit card transactions, money transfers don't have fraud protection or dispute mechanisms.
- Use Alternative Methods: For transactions with unknown parties, consider using payment methods with better security and fraud protection, like credit cards or payment platforms like PayPal.
- Double-Check Details: Before completing a money transfer service, double-check all the recipient's details to ensure accuracy and legitimacy.
Verify Identity and Authenticate Transactions
Verifying the identity of the parties involved in a transaction and ensuring the transaction itself is authentic are crucial steps to preventing money transfer scams. Scammers often rely on impersonation and fake transactions to deceive victims.
User Authentication at the Point of Purchase
Implementing strong user authentication methods at the point of purchase can significantly reduce fraud risk. This involves verifying the buyer's identity before completing the transaction.
Effective Authentication Methods:
- Biometric Verification: Use biometric data, like fingerprints or facial recognition, for added security during transactions.
- Secure Payment Gateways: Use secure payment gateways that offer robust authentication processes.
- Verification Codes: Require verification codes sent to the user's mobile device or email before completing the purchase.
Be Cautious When Transferring Money
Exercising caution and diligence when transferring money is essential to avoid scams. Here are some tips to keep in mind:
- Double-Check Recipient Details: Always double-check the recipient's information before starting a transfer. Make sure the name, account number, and routing or control number are accurate.
- Avoid Public Wi-Fi: Only complete financial transactions on secure, private networks. Public Wi-Fi can be easily compromised by scammers.
- Limit Transfer Amounts: If possible, limit how much money you transfer at once, especially when dealing with new or unknown parties.
Protect Your Bank Account
Protecting your bank account from unauthorized access is vital to preventing financial losses due to scams.
Security Measures:
- Strong Passwords: Use complex, unique passwords for your bank accounts. Avoid easy-to-guess information, like birthdates or common words.
- Regular Monitoring: Regularly monitor your bank statements and account activity for suspicious transactions.
- Account Alerts: Set up account alerts to notify you of large withdrawals, suspicious activity, or login attempts from unrecognized devices.
- Secure Devices: Make sure your devices are protected with up-to-date antivirus software and that you use secure browsers for online banking.
By following these guidelines and putting these security measures in place, you can significantly reduce your risk of falling victim to money transfer scams.
Recovering From a Money Transfer Scam
If you suspect you've fallen victim to a money transfer scam, it's crucial to act quickly to limit any potential damage and increase your chances of recovering lost funds. Here are the steps to take to address the situation:
What Are the Steps to Recover Funds From Money Transfer Scams?
Contact Your Bank Immediately
The first and most critical step to recovering from a money transfer scam is contacting your bank. Here's what to do:
- Provide Details: Give your bank all the information about the transaction, including dates, amounts, and any communication with the scammer.
- Request an Investigation: Ask the bank to investigate the transaction. They may have specific procedures for handling fraud cases.
- Follow Up: Stay in regular contact with your bank to stay updated on the investigation's progress and any action they take.
Report to Authorities
- File a Report: Report the scam to your local law enforcement agency. Give them all the details and any evidence you have.
- Contact Federal Agencies: In the United States, report the scam to the Federal Trade Commission (FTC) and the Internet Crime Complaint Center (IC3). These agencies can help investigate the fraud and potentially recover funds.
Notify Your Employer
If the scam involves your workplace or business accounts, notify your employer right away. They may have additional resources or protocols to help mitigate the impact.
Monitor Your Accounts
- Watch for Unauthorized Activity: Closely monitor your bank accounts and credit reports for any signs of unauthorized transactions or identity theft.
- Set Up Alerts: Enable alerts on all financial accounts to get notified of any suspicious activity.
Change Security Details
- Update Passwords: Change the passwords on all your financial accounts and any other accounts that may have been compromised.
- Enable Two-Factor Authentication: Improve your account security by enabling two-factor authentication wherever possible.
Seek Professional Advice
- Legal Advice: Consider consulting with an attorney specializing in financial fraud to understand your legal options and rights.
- Financial Advisor: A financial advisor can help you assess the scam's impact on your finances and advise you on steps to prevent future occurrences.
By following these steps, you can take proactive measures to recover from a money transfer scam and protect yourself from future incidents. Staying informed is key to safeguarding your financial well-being in an increasingly digital world. Learn more about the immediate actions you can take if your account has been compromised
Conclusion
Money transfer scams are pervasive threats in today's digital landscape, targeting both individuals and businesses with sophisticated tactics. However, armed with knowledge and vigilance, you can protect yourself against these fraudulent schemes. By understanding common tactics, recognizing warning signs, and implementing preventive measures like verifying identities and protecting your bank accounts, you can significantly reduce your risk of falling victim to scams.
In the unfortunate event that you're scammed, quick action is crucial. Contact your bank immediately, report the scam to authorities, and monitor your accounts for unauthorized activity. By staying cautious and skeptical of unsolicited requests for money or personal information, you can navigate financial transactions with confidence and security.
Instant payments
Learn how to use Cash App for your finances in the U.S.
8 min de lectura
The popularity of digital personal finance applications continues to grow among users in the United States. According to recent data, 8 out of 10 Americans have embraced the digital economy by using financial applications for purchases, digital payments, online banking, and more.
Cash App is one effective alternative to facilitate personal finance management. In 2024, it recorded 57 million monthly active users and $16.2 billion in earnings.
If you're curious to know what Cash App is, how it works, all its benefits, and its associated fees, below we provide all the details so you can decide whether it is the best option to meet your needs.
What Is Cash App and What Is It Used For?
Cash App is an alternative to traditional banking that operates through a mobile financial services application. Its functionality is highly versatile, as it not only allows users to send and receive money but also to make purchases and receive direct deposits from payroll.
The application was developed by Block Inc. (formerly Square Inc.) and aims to offer a comprehensive and more accessible service through digital solutions.
To open an account on Cash App, you must meet certain requirements, such as having a Social Security Number (SSN) and a U.S. bank account.
Cash App: How It Works, What Features It Offers, and What Fees It Charges
Cash App is available through its official mobile application, in which you must complete the registration and verification process to access all available features. Once completed, you may link a bank account if needed.
You will also have a Cash Tag: a unique username that allows you to send and receive money easily.
The following are the main features offered by the Cash App application:
Sending and Receiving Money
Cash App allows instant transfers between users of the application free of charge (free instant transfers; standard network fees may still apply).
Cash Card
This is a free debit card linked to your balance. It allows you to make online and in-store purchases and withdraw cash from ATMs.
QR Code
Pay directly in physical stores using a QR code.
Cash App Pay
A payment method that allows users to complete transactions in online stores and directly through the application.
Cash Boosts
You can obtain discounts at selected physical and online establishments.
Fees for Using Cash App
Although many of Cash App’s features are free, such as account maintenance, use of the Cash Card, and transfers between Cash App accounts. Below is a table with some of the main fees and charges associated with the aforementioned features:
| Service | Cost |
|---|---|
| Instant transfer to bank card | 0.5 % to 1.75 % |
| Standard transfer (1 to 3 days) | Free |
| ATM withdrawals | 2.50 USD per withdrawal |
Cash App registration requirements
If you want to use Cash App to control your finances, make sure you meet the following requirements:
Have a U.S. phone number
You can also use an email to verify your identity.
Reside in the United States or England
Cash App is only available in the United States and the United Kingdom. The application and information are available in English only.
Have a bank account
It is recommended if you want to have access to all the functions of the application.
Do the identity verification
This will allow you to access features such as sending or receiving more than 1,000 USD over 30 calendar days and applying for the Cash Card.
But remember that to perform identity verification you need:
- Full name
- Birthdate
- Social Security Number (SSN)
How secure is Cash App? : 9 important considerations
The issue of security is one of the most relevant in relation to financial services applications. You should always verify that your provider has the necessary measures in place to keep your assets and personal data safe.
For its part, Cash App has the following security measures, among others:
Multifactor authentication
Cash App requests identity authentication via email or SMS. In addition, it allows you to activate a PIN or biometry to log in.
End-to-end encryption
Your personal data stored in Cash App is secure through TLS/E2E.
System for the detection and prevention of illegal activities
Cash App has implemented technologies trained to detect unusual behavior and prevent fraud, such as machine learning and algorithms.
Subsequent payment monitoring
The application has an additional monitoring system to do a double check and detect unusual activities.
Although the above features offer some certainty regarding the application's security measures, it's always important to take into account some considerations:
Turn off automatic login
To prevent an outsider from accessing your account without your authorization, avoid using automatic login. Instead, use strong, unique passwords and enable 2-step authentication.
Beware of fraud
Stay alert to scams, either by phone or email. Never give out personal information or passwords through these means. If you need to contact application support, do so through official means.
Keep active alerts
Cash App allows you to receive alerts for your transactions directly on your cell phone. Make sure to keep them active.
Verify data before making transfers
Send money only to people you know and verify their information before confirming the operation, since once the money has been sent, it is not possible to recover it.
Activate the PIN to carry out transactions
You have the option of activating the PIN or biometric data to confirm your transfers before doing them, and avoid the use of your application by third parties in case of theft or loss.
Are you looking for more than just a payment app? Comun is your financial ally in the U.S. UU.
There is no doubt that Cash App is a popular alternative among those looking for a fairly comprehensive and easy-to-use financial solution.
But if you are looking for a financial ally that offers a simple and secure experience, with customer service and a platform also available in Spanish, we present Comun.
Comun goes beyond traditional limitations, so that immigrant communities in the United States have access to quality financial services, without complications. With Comun you can:
- Receive and send money conveniently, without complications and without the need for a traditional bank account.
- Open your Comun account with the qualified Official Identification of your country of origin.
- Get a simple mobile application for hassle-free daily international money transfers.
Open your Comun account today and breaks down the barriers of traditional financial services, language and cultural ones.
FAQs
If you still have questions about what Cash App is for and its features, check out our frequently asked questions.
What are Cash Boosts in Cash App?
These are instant discounts available on the Cash Card. To activate them, enter the mobile application and select “Cash Card”, followed by “Add Boost” and “Save Boost”. Select the discount you are interested in and it will be applied when you pay with your debit card.
What happens if I receive a lot of money through Cash App?
Some necessary checks may be activated starting at $1000.
How much is the maximum that can be sent via Cash App?
1000 USD over 30 calendar days for unverified users; if you verify your user, you can increase this limit to 20,000 USD.
What is Cashtag in the Cash App?
This is a unique username that is used so that other users of the application can send you money. It starts with the $ symbol followed by an identifier.
Checking account
Debit Account in the United States
8 min de lectura
In this article, we'll walk you through the advantages and requirements of having a debit account in the United States. It's worth noting that the world's financial center is New York, home to the most important payment hubs where the world's top-ranked financial institutions are connected. That's why having an account in the United States is essential if you do business globally.
Why Having a Debit Account in the United States Matters
Here are the advantages of having a debit account in the United States and what it means to have one — among the most notable benefits:
Cost: The cost to open an account in the U.S. is actually minimal, largely thanks to the digital account types available today. This gives you the ability to handle financial transactions smoothly with the people you want to do business with.
Requirements: Requirements are usually basic, as long as you're of legal age and have some form of address documentation. If you're a foreigner, it's possible to open an account in the United States without a long list of requirements or needing to be physically present.
Control: You can track fees, deductions, and payments made through the platform — for that, we recommend reading: How to Manage My Money in a Debit Account.
Ideal for Freelancers: If you do remote work, global companies typically require an account on some payment platform. For that, you'll need a U.S.-based account. That's why it's worth opening one, so you can meet the requirements of that payment platform.
Security: You get the security that comes with U.S. regulation. On top of that, funds are protected by the Federal Deposit Insurance Corporation (FDIC).
Options: There's a wide variety of ways to get a U.S. account, and among the main options is starting with a debit account, which offers alternatives for people who want an account without being a U.S. resident.
General Requirements to Open an Account in the United States
The requirements listed here are for opening a general account — keep in mind that requirements vary by account type. Among the requirements U.S. financial institutions typically ask for:
ID document: Issued by your country of residence's government (passport, national ID, or identity card depending on your country of origin).
Proof of residence: A current utility bill showing your physical address. It must include a zip code.
Email address: So the confirmation email can be sent this way if you open the account through a platform or app.
Mobile device: To authenticate transactions made through the bank's platform.
If you want to open an account in the United States, there are several options and account types available. Just choose the one that fits your needs, requirements, and that you can comfortably and securely meet the requirements for.

Community
Using Your Digital Card From Day One: A Step-by-Step Guide
8 min de lectura
¿Por Qué Configurar una Tarjeta Digital?
Tu tarjeta digital está disponible para su uso tan pronto como financies tu cuenta, ofreciendo varias ventajas:
- Acceso Instantáneo: No hay período de espera para una tarjeta física.
- Conveniencia: Realiza compras en línea fácilmente en comerciantes populares como Amazon, Walmart y más.
- Flexibilidad: Usa la tarjeta digital para varias transacciones, incluyendo depósitos en efectivo con un código de barras en tu aplicación.
Configuración de Tu Tarjeta Digital
Sigue estos pasos para configurar y comenzar a usar tu tarjeta digital con Común¹:
1. Financia Tu Cuenta
Asegúrate de que tu cuenta bancaria esté financiada. Este paso es crucial, ya que tu tarjeta digital solo estará disponible después de que la cuenta tenga fondos.
2. Accede a la Tarjeta Digital
Abre tu aplicación bancaria Común y navega hasta la página principal.Busca el botón “Administrar tarjetas” en la esquina superior izquierda de la página principal.
3. Ver Detalles de la Tarjeta
Haz clic en “Administrar tarjetas” para acceder a las opciones de gestión de tarjetas.Para ver los detalles de tu tarjeta, haz clic en “Ver información de la tarjeta”.
4. Usando Tu Tarjeta Digital para Compras en Línea
Con los detalles de tu tarjeta visibles, ahora puedes usar tu tarjeta de débito digital para hacer compras en línea. Simplemente ingresa la información de la tarjeta en el proceso de pago en cualquier sitio web que acepte pagos con tarjeta de crédito o débito, incluidos grandes minoristas como Amazon y Walmart.
5. Depositar Efectivo
No necesitas esperar tu tarjeta física para depositar efectivo. Usa el código de barras en tu aplicación para hacer depósitos en efectivo en lugares compatibles.
Beneficios e Inconvenientes de Usar una Tarjeta Digital
Seguridad: Las tarjetas digitales ofrecen una capa adicional de seguridad para transacciones en línea. Se pueden bloquear o reemplazar fácilmente si se ven comprometidas, reduciendo el riesgo de robo de identidad y transacciones no autorizadas.
Uso Inmediato: Comienza a comprar en línea o deposita efectivo sin esperar tu tarjeta física.
Control: Gestiona los detalles de tu tarjeta directamente desde tu aplicación Común, lo que facilita el seguimiento de gastos y la actualización de información según sea necesario.
Conveniencia: No es necesario llevar una tarjeta física, lo que reduce el riesgo de perderla.
Inconvenientes Potenciales de Usar una Tarjeta Digital
Aceptación Limitada: Algunos comerciantes pueden no aceptar tarjetas digitales, especialmente para transacciones en tienda donde se requiere una tarjeta física.
Dependencia de la Tecnología: El acceso a tu tarjeta digital depende de tener tu dispositivo móvil y conexión a internet. Si pierdes tu teléfono, te lo roban o se queda sin batería, podría ser difícil acceder a los detalles de tu tarjeta.
Transición a Tarjeta Física: Una vez que llegue tu tarjeta física, necesitarás activarla y actualizar cualquier método de pago guardado, lo que puede ser un paso adicional.
Riesgos de Seguridad Potenciales: Aunque las tarjetas digitales son generalmente seguras, no son inmunes a ataques de phishing u otras estafas en línea. Es esencial estar alerta y practicar buenos hábitos de seguridad.
Why Set Up a Digital Card?
Your digital card is available to use as soon as you fund your account, offering several advantages:
- Instant Access: No waiting period for a physical card.
- Convenience: Easily make online purchases at popular merchants like Amazon, Walmart, and more.
- Flexibility: Use the digital card for various transactions, including cash deposits using a barcode in your app.
Setting Up Your Digital Card
Follow these steps to set up and start using your digital card with Común¹:
1. Fund Your Account
Make sure your bank account is funded. This step is crucial, since your digital card will only be available once the account has funds.
2. Access the Digital Card
Open your Común banking app and navigate to the home page. Look for the "Manage cards" button in the top left corner of the home page.
3. View Card Details
Click "Manage cards" to access card management options. To view your card details, click "View card information."
4. Using Your Digital Card for Online Purchases
With your card details visible, you can now use your digital debit card to make online purchases. Simply enter your card information at checkout on any website that accepts credit or debit card payments, including major retailers like Amazon and Walmart.
5. Depositing Cash
You don't need to wait for your physical card to deposit cash. Use the barcode in your app to make cash deposits at supported locations.
Benefits and Drawbacks of Using a Digital Card
Security: Digital cards offer an extra layer of security for online transactions. They can be easily locked or replaced if compromised, reducing the risk of identity theft and unauthorized transactions.
Immediate Use: Start shopping online or depositing cash without waiting for your physical card.
Control: Manage your card details directly from your Común app, making it easy to track spending and update information as needed.
Convenience: No need to carry a physical card, reducing the risk of losing it.
Potential Drawbacks of Using a Digital Card
Limited Acceptance: Some merchants may not accept digital cards, especially for in-store transactions where a physical card is required.
Technology Dependence: Access to your digital card depends on having your mobile device and an internet connection. If you lose your phone, it's stolen, or the battery dies, it could be difficult to access your card details.
Transition to a Physical Card: Once your physical card arrives, you'll need to activate it and update any saved payment methods, which can be an extra step.
Potential Security Risks: While digital cards are generally secure, they aren't immune to phishing attacks or other online scams. It's essential to stay alert and practice good security habits.
How to Avoid the Drawbacks of a Digital Card
While digital cards offer many benefits, being aware of potential drawbacks and mitigating them ensures a smooth, secure experience. Here are some tips on how to avoid common issues associated with digital cards:
Confirm Merchant Acceptance:
Before making a purchase, especially in-store, confirm that the merchant accepts digital cards or mobile wallet payments like Google Pay or Apple Pay. For online purchases, most major retailers will accept digital cards without issue.
Prepare for Technology Dependence:
Always have a backup plan. Keep a secondary payment method, like a physical card or another digital wallet, available in case your mobile device isn't accessible. Charge your phone regularly and consider carrying a portable charger.
Smooth Transition to a Physical Card:
When your physical card arrives, activate it right away and update your payment information across all your regular services. This includes updating saved card details on online shopping sites and digital wallets to ensure continuity.
Improve Security Measures:
Protect your digital card against phishing attacks by only entering card details on trusted websites. Use a secure browser extension or app to generate unique digital card numbers for different transactions, adding an extra layer of security.
Enable notifications for all transactions to monitor for any unauthorized activity. This helps you quickly detect and respond to any suspicious transactions.
Stay Informed and Proactive:
Regularly review your account settings and transaction history in the Común app to stay on top of your finances.
Set spending limits on your digital card to manage your budget and avoid overspending. Keeping an eye on your available balance ensures you don't face declined transactions due to insufficient funds.
Use Customer Support:
If you run into any issues or have questions about using your digital card, don't hesitate to contact Común customer service. They can provide additional assistance and help you resolve any issues quickly.
Get your digital card with Común right now!
Open your bank account¹ in 3 minutes with your country's ID²
Integrating Digital Cards With Digital Wallets
For added convenience, you can integrate your digital card with digital wallets like Google Pay and Apple Pay. This lets you use your digital card for both online and in-store purchases without needing the physical card. Simply add your digital card details to your preferred digital wallet app and start spending safely and conveniently.
Managing Your Digital Card
Using your digital card effectively means staying on top of your account settings and spending limits. Here are some tips for managing your digital card:
- Monitor Transactions: Regularly review your transaction details in your Común app to make sure all charges are correct.
- Set Spending Limits: Control your spending by setting limits on your digital card, helping you avoid overspending and better manage your budget.
- Update Payment Information: Keep your payment information up to date, especially if you receive a new digital card or need to change your billing address.
Conclusion
Setting up and using your digital card from day one is a simple process that offers immediate access and convenience. While there are numerous benefits, including greater security and instant availability, it's important to be aware of potential drawbacks. By understanding both the pros and cons, you can make informed decisions about how best to use your digital card.
Take advantage of the ease of modern banking by activating your digital card today and enjoy the benefits of instant access to your funds. Whether you're making online purchases or depositing cash, your digital card provides a flexible, secure way to manage your finances. Visit Común to learn more about setting up your digital card and explore other innovative banking solutions we offer.

Community
How Common Makes Money: A Transparent Look at Our Business
8 min de lectura
Founded by Mexican co-founders who themselves navigated the banking system as immigrants in the United States, Común brings a unique perspective to the challenges faced by its target audience.
Let’s look at how Común remains profitable through innovative revenue streams, cost-saving strategies, and a deep commitment to its customers, emphasizing how these factors contribute to the ease and benefits of virtual banking for newcomers to the financial world.
Revenue Streams: Banking Services
Común not only offers essential banking services¹, but also features such as international remittances⁴, which provide significant benefits for Común customers. Común monitors cash flows and payment channels to ensure efficient and secure transactions. Consumers often pay high remittance fees with other services, but Común offers a cost-effective alternative.
This service is crucial for immigrants who regularly send money home, increasing Común’s appeal as a banking solution that understands and responds to the specific financial dynamics of its users.
Cost-Saving Strategies: Financial Inclusion
The strategic absence of physical branches allows Común to minimize operating costs and maximize profits. Común allocates resources to expand its reach and improve financial services for Latina immigrant families. These savings are passed on to customers through lower fees and better rates, making financial services more accessible. Común’s digital platform makes banking easier to access, offering 24/7 services that make money management secure and efficient from any browser or app.
Company Values and Customer Relationship
Común champions financial inclusion, particularly within the Latino community, positioning itself among companies dedicated to serving Latino communities and enabling account setup with a variety of international IDs. This inclusivity strengthens trust and understanding between Común and its customers, fostering a supportive banking environment.
Competitive Advantage
By creating a customer-focused digital bank that offers services in Spanish and accepts nontraditional IDs, Común specifically addresses the barriers faced by Latino immigrants. This personalized service not only sets Común apart from its competitors, but also deepens customer loyalty and trust.
Target Audience
Común focuses on Latino immigrants, a group often overlooked by traditional banks. In its latest funding round, Común raised $5 million in June 2022 to further develop its services. By offering accessible and empathetic financial services, Común not only meets a significant market need, but also empowers its customers toward greater financial stability and integration into the U.S. economy. South Park Commons, along with Costanoa Ventures, has played a key role in supporting financial inclusion banking solutions for Latina immigrant families in the United States.
Conclusion
Virtual banks like Común present an easy-to-use, cost-effective, and inclusive alternative to traditional banking, particularly beneficial for those who are new to banking or marginalized by conventional financial institutions. By focusing on accessibility, cost efficiency, and customer-oriented services, Común not only maintains profitability, but also significantly improves the banking experience for its users.

Instant payments
How do I send money through Xoom? Your complete 7-step guide
8 min de lectura
Today, sending money to other countries has become a basic need for millions of immigrants living in the United States.
According to the IDFR ( International Day of Family Remittances) campaign in 2025, over the last decade, immigrants sent around 5 trillion dollars in remittances to their countries of origin, which are essential for food, housing, health, and other basic expenses.
To meet this need, there are applications such as Xoom, a PayPal service for transferring money using various payment methods and in a secure manner.
In this guide, we will review how to send money with Xoom step by step, its main features, and some alternatives to connect with your family outside the U.S.
What is Xoom, and is it safe to send money with this service?
Xoom is a digital transfer network owned by PayPal that operates entirely online and offers different sending options to facilitate transactions.
It has become one of the most popular options for making international digital money transfers, due to the backing provided by PayPal, which gives users a sense of security.
In addition to PayPal’s backing, Xoom has high security standards for transferring money, such as SSL encryption and the VeriSign seal.
Additionally, its services are available to send money from the United States to more than 70 countries, including Mexico, Guatemala, Honduras, Peru, among others.
7 detailed steps to send money with Xoom
To send money through Xoom, just follow the steps below.
Access Xoom (web or mobile application) and sign in or register
You can choose to log in via the website www.xoom.com or the mobile application. Once there, sign in or open an account with your email address. You can also use your PayPal account to access.
Select the destination country and the amount to send
Choose the country to which you want to send the transfer. Then you will see the sending options available for the selected destination.
Choose the sending method
Xoom offers the following payment methods:
- Bank deposit
- Cash pickup at physical locations, such as Oxxo or Elektra
- Mobile top-up
- Bill payment
- Cash delivery
Provide the recipient’s details
The information you must enter is:
- Full name, as it appears on their official ID
- Address
- Phone number
- Bank account (if applicable, depending on the sending method)
Select your payment method
Next, enter the amount you want to send and select the payment method, among which are:
- Linked bank account
- Debit card or credit card
- Available balance in your PayPal account
Review and confirm the transaction
Before confirming the transfer, Xoom will display the details so you can verify they are correct, along with the amount corresponding to fees, as well as the exchange rate used for the currency conversion.
Track your transfer with the tracking number
Obtain a tracking number and check the status of your transfer directly in Xoom’s application or website.
Key aspects to consider when using Xoom
Although Xoom is a popular alternative for making fast and secure transfers, it is important to consider several aspects before choosing this option.
Sending fees
Xoom’s sending fees are not fixed; they depend on the destination country, the amount to send, and the payment method.
Generally, the most expensive method is with a credit card and the least expensive is through an account.
| Platform | Fee | Exchange rate | Delivery time | Delivery options |
|---|---|---|---|---|
| Xoom | From 2.99 USD, depending on the sending type | Less favorable | Minutes to hours | Bank deposit, cash pickup, home delivery |
| Común | Fee starting at 2.99 USD, up to the applicable limits | Competitive (Clarification: Results may vary depending on destination country and sending method) | Minutes | Cash pickup, bank deposit |
Exchange rate
The exchange rate can be another drawback because, in addition to being calculated directly on Xoom’s platform, it varies depending on the selected transfer method.
Sending limits
Xoom imposes sending limits that depend on each account’s verification level. For unverified users residing in the U.S., the daily limit is $2,999 USD. By contrast, verified users can send up to $10,000 or $50,000 USD per day, depending on their verification level.
Receiving options
Xoom has different receiving options, but they may vary depending on the destination country.
In general, it is possible to send money for cash pickup at different payout locations, by bank deposit, top-up, or bill payment.
Security and reliability
Xoom is backed by PayPal, in addition to SSL/TLS encryption to protect your financial information and anti-fraud monitoring to ensure your money reaches its destination.
Delivery times
Generally, money transfers via debit card and cash are reflected within minutes. However, other sending methods, such as bank deposit, can take from 1 business day.
The total time will appear before you confirm your transaction in Xoom’s application or on its website.
Accessibility
Xoom is also available in Spanish and, overall, is easy for migrants in the United States to use.
Modern alternatives to sending money with Xoom: Why is Común a smart choice?
Sending money outside the U.S. is essential, as is having efficient international transfer services such as Xoom. However, there are also more innovative options that offer you greater advantages and lower costs so that your family and friends receive much more.
Común is an innovative and comprehensive financial service that meets the financial needs of users living in the United States, especially immigrants. Unlike Xoom, Común has a specialized focus and transparent fees.
With Común:
- Open your account with an official ID from your country; more than 100 identifications are accepted.
- After your first free transfer, pay a fee starting at $2.99 USD per transfer, up to the applicable limits.
- Access customer service in Spanish and English, available 24/7.
- Get a Visa debit card to make purchases at physical merchants.
- Manage your finances from Común’s mobile platform, where you can sync your external bank account and manage your finances from the Común platform.
Still unsure which option is most convenient for sending money? Discover Común and get to know the easy and safe side of finance.
Frequently asked questions
If you want to learn more, see our FAQ section
How do I send money from Mexico to the United States using Xoom?
It is not possible to send money from Mexico through Xoom, since it only allows transfers from the United States, Canada, and other European countries.
How long does it take for money to arrive via Xoom?
Depending on the sending method, it ranges from minutes to up to 3 business days.
Is it safe to use Común to send money to Latin America?
Yes, Común has the necessary security measures in place to keep your money and personal data safe.
Can I use Común even if I don’t have a PayPal account?
Yes, Común is an independent platform from PayPal, and you can open an account with official ID from your country.
Can I make cash deposits if I don’t have a bank account in the U.S.?
Yes, Común allows you to deposit cash at numerous locations near you.
International Money Transfers
How to send money to Mexico via WhatsApp? Común vs. WhatsApp Pay
8 min de lectura
How to send money to Mexico via WhatsApp? Común vs. WhatsApp Pay
WhatsApp does not currently offer a service to send money directly from the United States to Mexico.
WhatsApp is one of the most popular ways to stay in touch with family and friends across borders. While the app supports payments in certain countries, its payment features are not available for sending money from the United States to Mexico.
However, for people living in the United States who are looking into sending money to Mexico, there are many different options available. From traditional service providers such as Western Union and MoneyGram to apps with instant international transfers like Wise, Remitly and Común.
Can I send money to Mexico via WhatsApp from the United States?
At this time, WhatsApp does not offer an official service that allows people in the United States to send money directly to recipients in Mexico through WhatsApp Pay. WhatsApp's payment functionality is only available in Brazil and India.
This means that you can still use WhatsApp every day to communicate with family and friends in Mexico, but you cannot transfer money from a U.S. account to a recipient in Mexico using WhatsApp Pay.
Some money transfer companies offer WhatsApp-based experiences that help initiate transfers, but those services are different from WhatsApp Pay itself. The actual transfer is processed through the remittance provider rather than through WhatsApp's native payment system.
What is WhatsApp Pay and how does it work?
WhatsApp Pay is a payment feature integrated into WhatsApp that allows eligible users to send and receive money without leaving the app. The service operates through local payment networks and financial partners in supported countries.
As of 2026, WhatsApp Pay is available in India and Brazil. It is not broadly available as a payment method in the United States, and it is not available as a direct remittance solution for sending money from the United States to Mexico.
Why can't I use WhatsApp to send money to Mexico?
Cross-border money transfers require financial institutions, payment networks, regulatory approvals, identity verification procedures, and international settlement systems. WhatsApp Pay was built around local payment systems in specific countries. Because of this, the service does not currently support direct remittances from U.S. bank accounts to recipients in Mexico.
This limitation often creates confusion because WhatsApp is widely used on both sides of the border. Messaging a family member in Mexico through WhatsApp is easy, but sending money through WhatsApp Pay is a different service with separate availability requirements.
How much does WhatsApp Pay charge for sending money?
There is no standard fee for sending money from the United States to Mexico through WhatsApp Pay because that service is not currently available.
If you're in the United States and need to send money to Mexico, you will need a remittance service provider. To compare the costs related to sending money to Mexico, it can be important to review: transfer fees, exchange rates, delivery methods, transfer speed, and recipient requirements.
What's the best way to send money to Mexico if not via WhatsApp?
There is no single answer because different money transfer methods work better for different situations. Bank transfers can be a familiar option for people who already have a checking account. Traditional remittance providers such as MoneyGram and Western Union offer multiple delivery methods, including bank deposits, cash pickup locations, and mobile wallets in some markets.
Digital remittance platforms have become increasingly popular because they offer the possibility of sending money directly from a smartphone. These services typically display the exchange rate, fees, and delivery method before the transfer is completed.
One option is Común through its remittances services, which allows eligible customers to send money to Mexico and other countries in Latin America directly from the Común app. Transfers start at $2.99, and many transfers are delivered on the same day depending on the destination and delivery method.
How to send money to Mexico with Común? (step by step)
1. Open the Común app on your phone.
Sign in to your account and navigate to the remittance section.
2. From the main page, select "Envía una Remesa".
Select the option on your app.
3. Choose your recipient or add a new one.
Provide the required details for the person receiving the transfer.
4. Enter the transfer amount.
Review the amount you want to send.
5. Review the transfer details.
Confirm the recipient information, delivery method, transfer amount, and estimated delivery timeframe.
6. Confirm the transfer.
Complete the transaction and wait for confirmation. Many transfers are delivered the same day, although delivery times may vary.
WhatsApp Pay vs. Común: a direct comparison
| Feature | WhatsApp Pay | Común |
|---|---|---|
| Send money from the United States to Mexico | No | Yes |
| Cross-border remittances | No | Yes |
| Starting transfer cost | Not available for U.S.-Mexico transfers | Starting at $2.99 |
| Delivery to recipients in Mexico | Not supported | Available |
| Transfer purpose | Domestic payments in supported countries | Money transfers to Mexico and Latin America |
WhatsApp Pay was created for payments within certain supported markets. Común remittance services make it possible to send money from the United States to recipients in Mexico and other countries in Latin America directly from the Común app.
A Común account can be opened with a passport or more than 100 Latin American IDs with no minimums or monthly fees.
FAQ
Can I send money to Mexico using WhatsApp?
No. WhatsApp does not currently provide an official service that allows users in the United States to send money directly to recipients in Mexico through WhatsApp Pay.
How does WhatsApp Pay work?
WhatsApp Pay allows eligible users in supported countries to send and receive money through WhatsApp using local payment networks and financial partners.
How long does it take for the money to arrive if I send it with Común?
Many transfers sent through Común are delivered on the same day. Delivery times may vary depending on the destination, delivery method, and recipient institution.
What do I need to send money to Mexico with Común?
You generally need a Común account, the recipient's information, the transfer amount, and any additional details required for the selected delivery method.
How much does it cost to send money to Mexico with Común?
Común international transfers start at $2.99. The total cost may vary depending on the transfer amount, destination, and exchange rate.
Is it safe to send money through apps from the United States?
Using a regulated money transfer provider can help protect your transaction through identity verification, encryption, fraud monitoring, and transaction tracking features.
Común is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank, Member FDIC. Peer-to-peer payments services are provided by Cross River Bank. No minimums, no maintenance fees. Remittance service provided by Service UniTeller, Inc. Remittance fees start at $2.99 but may vary. Común Inc. may earn revenue from the conversion of foreign currencies.







Thousands of immigrants are already achieving more with their money. You can too.
Comun is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank; Member FDIC. The Comun Visa® Debit Card is issued by Community Federal Savings Bank, pursuant to a license from Visa U.S.A Inc. and may be used everywhere Visa Cards are accepted.
Comun is a fintech company and not a bank or licensed money transmitter.
* Results may vary. For a complete list of eligible IDs and application requirements, follow this link.
^ No minimums, no maintenance fees. ATM or transfer fees may apply. See app for fee details.
‡ Direct deposit funds are typically available when we receive the payment file, up to two days before the scheduled payment date. This early availability is not guaranteed.
** A service provided by Service UniTeller, Inc. Service UniTeller, Inc. is licensed in all states that require a license. Remittance fees start at $2.99 but may vary. Please check the app for more details. Comun Inc. may earn revenue from the conversion of foreign currencies.
† Funds in your account are FDIC insured up to $250,000 by ownership category through Community Federal Savings Bank (CFSB), Member FDIC, in the event CFSB fails.


