
International Money Transfers
Which banks offer Zelle in Mexico? What you need to know in 2026
Zelle does not send money directly to Mexico. Learn why, which banks support Zelle in the U.S., and the best alternatives to send remittances to Mexico in 2026.
8 min read

17 Jul 2026
Which banks offer Zelle in Mexico? What you need to know in 2026
Zelle does not send money directly to Mexico. Zelle only works between eligible U.S. bank accounts and credit unions within the United States.
If you are looking into different methods for sending money to your family in Mexico, you may be searching for 'which banks offer Zelle in Mexico' or trying to understand if Zelle works internationally. This is a common misunderstanding for immigrant families in the U.S. No Mexican bank officially offers Zelle for receiving transfers from the U.S., and Zelle itself is not designed for international money transfers or currency conversion.
What is Zelle and how does it work?
Zelle is a digital payment service that facilitates peer-to-peer transfers at select partner banks in the United States. It is known for its speed, with transfers appearing in minutes, and for its extensive coverage across the U.S. Some U.S. financial institutions that support Zelle include Bank of America, Chase, Wells Fargo, Citi, PNC, and many more.
Why doesn't Zelle work for sending money to Mexico?
Cross-border money transfers require financial institutions, payment networks, regulatory approvals, identity verification procedures, and international settlement systems. Zelle was built around domestic payment systems in the U.S. Because of this, the service does not support direct transfers from U.S. bank accounts to recipients in Mexico.
Alternatives for sending money to Mexico from the U.S. (2026 comparison)
| Service | Typical starting fees | Delivery speed | Exchange rate model | Cash pickup |
|---|---|---|---|---|
| Remitly | Varies; ~$1.99+ for bank deposit to Mexico | Express: minutes to same day; Economy: 3–5 days | Exchange rate markup applies | Yes |
| Wise | From ~0.48% of transfer; shown upfront | Usually same day to 2 days | Mid-market rate, no markup | Limited (select corridors) |
| Xoom | Depends on payment method and destination | Minutes to 1 day | Exchange rate markup applies | Yes |
| Western Union | Varies widely by method and destination | Minutes to several days | Exchange rate markup applies | Yes (extensive agent network) |
| Común | Starts at $2.99 via UniTeller; may vary | Varies by destination and method | Rates displayed before transfer | Yes (depending on delivery option) |
Fees, exchange rates, and delivery times vary based on transfer amount, destination, funding method, and payout option. In 2026, a 1% federal excise tax applies to cash-funded transfers. Bank, debit, and credit card transfers are exempt.
How the new 1% tax on cash remittances affects transfers to Mexico
Starting in 2026, a 1% federal tax applies to certain remittance transfers. The tax applies when you pay with cash, money order, or cashier's check. Transfers funded from a U.S. bank account or with a U.S.-issued debit or credit card are exempt by law.
FAQ
Does Zelle work in Mexico?
No. Zelle does not support international transfers. There is no Mexican bank that offers Zelle for receiving money from the U.S.
What is the best app to send money to Mexico?
It depends on your specific situation. Común offers transfers starting at $2.99 with transparent pricing. Visit comun.app/remittances to learn more.
Remittance service provided by Service UniTeller, Inc. Remittance fees start at $2.99 but may vary. Común Inc. may earn revenue from the conversion of foreign currencies.
About Común
Común aims to support the Latino community in the United States. It offers a debit account that can be opened with more than 100 valid Latin American IDs and an app available in Spanish.
Visit Común's website or download the app for free to learn more about the full offer and applicable terms.
Olivia Rhye
Community Partner

Instant payments
Banks that support Zelle in 2026: Sending and receiving money in the U.S.
8 min de lectura
Banks that support Zelle in 2026: sending and receiving money in the U.S.
Zelle is built directly into many bank accounts in the U.S., which is why it has become one of the most widely used ways to send money. Today, more than 2,000 banks and credit unions offer access to the service.
Understanding how that network works is key to knowing whether you can use it with your account. That distinction matters more today than it did a few years ago. Since April 2025, Zelle is no longer available as a standalone app. Access depends entirely on whether your bank is part of the network.
What Is Zelle?
Zelle is a peer-to-peer payment network owned by Early Warning Services LLC (EWS), a company co-founded by seven of America's largest banks: Bank of America, Capital One, Chase, PNC, Truist, U.S. Bank, and Wells Fargo. It allows you to send money directly from your bank account to another person's bank account using only a phone number or email address. Transfers are typically completed within minutes.
What are the benefits of Zelle?
The main appeal of Zelle is its speed, simplicity, and convenience. Transfers are typically completed within minutes and move directly between bank accounts without the need to load funds into a separate app or digital wallet. In most cases, there are no fees for sending or receiving money, making it a practical option for everyday payments such as rent, shared expenses, or paying friends and family.
Because Zelle is integrated into your bank's app, there is usually no additional setup beyond enrolling your email address or mobile number. Funds are deposited directly into your account and are generally available quickly.
Why does bank support matter?
As of April 1, 2025, Zelle can only be accessed through participating financial institutions. If your bank or credit union does not support Zelle, you generally can't use the service.
Zelle supported banks list
Zelle partners with more than 2,300 financial institutions. To search for a specific bank or credit union, visit zellepay.com/get-started.
Below is a representative, not exhaustive list of financial institutions that currently offer Zelle:
| Name | Transfer limit |
|---|---|
| TRADITIONAL FINANCIAL INSTITUTIONS | |
| Bank of America | Up to $3,500 USD per day |
| Chase | Dynamic limit; typically $500 to $10,000 USD per day |
| Citi Bank | Up to $2,500 USD per day for accounts open longer than 30 days |
| TD Bank | $1,000 USD for instant transfers; up to $2,500 USD for scheduled transfers |
| PNC Bank | Typically $500 to $2,500 USD per day |
| Wells Fargo | Up to $3,500 USD per day |
| DIGITAL BANKS | |
| Ally Bank | Up to $600 USD per day |
| Discover Bank | $500 USD per transaction; $1,000 USD per day |
| SoFi | Up to $1,000 USD per day |
| Truist Bank | Typically $2,000 USD per day to $10,000 USD per month |
| EverBank | Up to $2,000 USD per day |
| CREDIT UNIONS | |
| BECU (Boeing Employees Credit Union) | $1,500 USD per day (instant); $3,000 USD per day (standard) |
| Bethpage Federal Credit Union | Limits vary by account and membership |
| Delta Community Credit Union | Limits vary by account and membership |
| First Tech Federal Credit Union | Limits vary by account and membership |
| Navy Federal Credit Union | Limits vary by account and membership |
Please note that Zelle limits often depend on factors such as account age, transaction history, recipient details, and other risk-based criteria established by the financial institution. Please refer to your financial institution for the most up-to-date information.
How to enroll in Zelle with your bank?
Since the standalone Zelle app has been discontinued, you must enroll through a participating bank or credit union app. The following steps generally apply to most participating financial institution apps:
- Open your bank's mobile app and locate 'Zelle' in the payments or transfer section
- Select 'Enroll with Zelle' or 'Send Money with Zelle'
- Enter your U.S. mobile number or email address
- Verify your identity using a one-time verification code
- You're then able to send and receive money using a recipient's phone number or email address
Please note that both the sender and recipient generally must be enrolled with Zelle through participating financial institutions for transfers to be completed. If the recipient isn't enrolled, they may receive instructions on how to enroll. If enrollment is not completed within the applicable timeframe, the transaction may be canceled and refunded.
Is Zelle Safe? Common scams to avoid
Zelle uses bank-level encryption and security protocols and operates within participating financial institution apps. However, many reported issues involving Zelle are associated with fraud or social engineering scams rather than technical failures.
Because Zelle transfers are typically processed quickly and may be difficult or impossible to reverse once authorized, scammers may attempt to pressure users into sending funds.
Common Zelle Scams in 2026:
Fake bank fraud alerts:
Scammers may send text messages appearing to come from your bank asking whether you authorized a transaction. After you respond, you may receive a call from someone falsely claiming to represent the bank and instructing you to transfer funds to 'reverse' fraud. In reality, the funds are being sent to the scammer.
Impersonation scams:
Scammers may claim to represent a bank, government agency, utility company, or another trusted organization and pressure victims into sending money immediately.
Marketplace scams:
Fraudsters on platforms such as Facebook Marketplace or Craigslist may request payment through Zelle. After funds are sent, the item may never arrive or the payment may later prove fraudulent.
Overpayment scams:
A scammer may claim to have 'accidentally' sent money and ask for it to be returned. Their original payment may later be reversed or determined to be fraudulent.
How to stay safe:
- Use Zelle primarily with people you know and trust
- Never send money to 'verify' your account or reverse fraud
- If you receive an unexpected call claiming to be from your bank, hang up and contact the bank using the number on the back of your debit card
- Enable transaction alerts through your banking app
- Treat every Zelle payment as potentially final before authorizing it
Are there alternatives to Zelle for people without a traditional bank account?
Zelle's transition away from a standalone app in April 2025 created challenges for individuals who do not have accounts with participating financial institutions.
Venmo and Cash App
Remain popular alternatives for domestic transfers and may not require a traditional bank account to get started. However, they generally do not support international money transfers.
Wise
Allows users to receive and send funds internationally using local bank details in many currencies. It is commonly used for international transfers and is known for transparent pricing and exchange rates based on the mid-market rate.
Común
Is a financial platform that promotes financial inclusion for individuals who may face barriers with traditional U.S. banks, offering user-friendly, Spanish-language support. With Común you can make transfers within and outside the U.S. and send money to friends and family throughout Latin America, with fees starting at $2.99 per transfer. Visit comun.app to learn more.
FAQ
Does Zelle charge fees?
Zelle itself generally doesn't charge fees to send or receive money. However, your financial institution may have its own fee structure for the underlying account. It is important to check the specific details with your financial institution.
What if my bank doesn't use Zelle?
Since the standalone Zelle app was discontinued in April 2025, your options may include opening an account with a participating financial institution or using an alternative service such as Venmo, Cash App, Wise, or Común.
Can I use Zelle without a U.S. bank account?
No. Zelle generally requires a U.S. bank or credit union account at a participating financial institution.
Can I send money internationally with Zelle?
No. Zelle supports transfers only between U.S. bank or credit union accounts at a participating financial institution. For international transfers, consumers may consider alternatives such as Wise, Remitly, or international money transfer providers.
What happens if I send money to the wrong person?
Contact your financial institution immediately. Once funds are delivered, cancellation or recovery may not be possible.
Access Matters When Choosing a Bank for Zelle
Choosing between banks that supports Zelle ultimately comes down to access and convenience. While the network is broad, access depends on maintaining an account with a participating financial institution. For some consumers, a traditional bank or credit union may meet their needs. Others may prefer platforms designed to support individuals who face barriers to accessing traditional banking services. If Zelle access is important to you, it may be helpful to consider not only which financial institutions support the service, but also which ones best fit your individual needs.

Instant payments
How to send money to someone using Zelle from Común: 2026 guide
8 min de lectura
With Común you can link a debit card from another U.S. bank to your account — no Común physical card required — to send and receive money right away, even if you don't have funds in your balance.
How do I link an external card to my Común account?
In the app, go to the external cards section and add your debit card from another U.S. bank (Bank of America, Wells Fargo, Chase, or another). Común verifies the card is yours with a micro-deposit of less than $1.00 that you confirm in the app — we'll never ask for your bank password.
What can I do once the card is linked?
Send and receive payments and remittances using that card, even if your Común balance is $0. This is useful if you just opened your account and don't have your physical card yet, or if you prefer to keep your main money in another bank while using Común to move payments.
What cards can I link?
Valid debit cards, issued in the U.S., in your name, that allow sending and receiving funds. You can add up to 2 cards during your first 60 days with the account. Credit and prepaid cards aren't accepted.
Frequently asked questions
Do I need my physical Común card to send money?
No, if you have a linked external card, you can send and receive money right away without it.
Which banks can I link?
Any U.S. bank that issues debit cards in your name — Bank of America, Wells Fargo, Chase, and many others.
How does Común verify the card is mine?
With a micro-deposit of less than $1.00 to the linked account, which you confirm in the app. That money is yours to keep.
How many external cards can I add?
Up to 2 debit cards during your first 60 days with the account.
Why was my card rejected?
The most common reasons: the name doesn't match your account, it's a credit card, or it wasn't issued in the U.S.
Is it safe to link an external card?
Yes — Común never asks for your bank password or sensitive information during the process.
International Money Transfers
Sending money to Latin America? What you need to know about the new 1% tax
8 min de lectura
Sending Money to Latin America? What You Need to Know About the New 1% Tax
If you send money home to Mexico, Guatemala, Colombia, El Salvador, Honduras, or anywhere else in Latin America, a new federal law may affect the fees you pay per money transfer, depending on how you send it.
On July 4, 2025, the United States enacted the One Big Beautiful Bill Act (OBBBA), Public Law 119-21, which introduced a new federal excise tax on certain international money transfers. The tax, set at 1% of the transfer amount, applies to remittances made on or after January 1, 2026. However, not all transfers are taxable.
If you send money from a US bank account or using a US-issued debit or credit card, your transfer is exempt from the tax by statute. The tax applies only when you pay with cash, a money order, a cashier's check, or a similar physical instrument.
Understanding whether this tax applies to you and how it may affect your transfers can help you send money home with fewer surprises.
What Is the New 1% Remittance Tax?
It imposes a 1% federal excise tax on certain outbound remittance transfers, meaning money sent from a sender in the United States to a recipient in a foreign country, through a remittance service provider.
The tax is codified under IRC Section 4475, added to the Internal Revenue Code by Section 70604 of the OBBBA. It applies to all senders, regardless of citizenship or immigration status.
The tax was effective for transfers made after December 31, 2025, with collection beginning January 1, 2026.
Who Pays the Tax? Who Doesn't?
The key factor is how you fund the transfer, not how much you send, not where it goes, and not your immigration or citizenship status.
| Subject to the 1% Tax | Exempt from the 1% Tax |
|---|---|
| Transfers funded with cash (e.g., paying cash at a remittance service provider) | Transfers funded from a US bank account at a BSA-compliant institution |
| Transfers funded with money orders | Transfers funded with a US-issued debit card |
| Transfers funded with cashier's checks | Transfers funded with a US-issued credit card |
| Transfers funded with similar physical instruments | Transfers of $15 or less (under EFTA threshold) |
Source: IRS.gov, RSM US. This information is for informational purposes only and does not constitute legal or tax advice.
This means that if you often send money back home with a remittance service provider with physical locations (for example Western Union or MoneyGram) and pay with cash, a 1% tax will be added to your total transfer amount.
However, if you send money through a digital app or bank account linked to your US checking or savings account, or pay with a US-issued debit or credit card, the transfer is exempt from the tax under Section 4475.
How Is the Tax Collected?
The tax is collected at the point of transfer. When a taxable transaction occurs, the remittance transfer provider is responsible for collecting the 1% from the sender at the time the transfer is made.
Providers must then deposit the collected taxes with the IRS on a semimonthly schedule and file quarterly returns.
The Remittance Landscape in 2026
For millions of families across Latin America, the money that arrives from a relative in the United States can pay the rent, cover school fees, or put food on the table. In 2024, Latin America and the Caribbean received an estimated $161 billion in remittances, the vast majority sent from the US. Mexico alone received over $63.3 billion. In countries like El Salvador, Guatemala, Nicaragua, and Honduras, remittances represent between 19% and 26% of GDP.
For people already stretching every dollar between their own expenses in the US and the needs of family back home, an additional cost on each transfer can have an impact. How much it affects you depends largely on the tools available to you.
Cash agent networks (Western Union, MoneyGram, Intermex):
These are the traditional in-person options, often used by senders who mostly manage cash. Transfers funded with cash at these locations are subject to the 1% tax.
Digital apps (Remitly, Wise, Xoom, Común, and others):
These platforms typically process transfers from a linked US bank account or US-issued debit or credit card. These payment methods are exempt from the tax under Section 4475. However, fees and exchange rate margins may vary by provider.
Bank wire transfers:
Transfers sent directly from a US bank account at a Bank Secrecy Act–compliant institution are exempt from the tax by statute. Bank wire fees can be higher than digital app fees.
What This Means for You
If you send money home regularly, you already know that there are costs involved: transfer fees, exchange rate margins, sometimes a fee on the receiving end. Now, depending on how you send money, there may also be a new 1% federal tax. That may not sound like much in isolation, but if you're someone already careful about managing what to keep and what to send, it can add up.
There is no single right answer for everyone. Some people that have a US bank account can shift to a digital transfer method. Others who don't have that option yet, or may have reasons for continuing to send through an agent location. Whatever your situation is, a few things may help:
Know what you're being charged:
Before confirming any transfer, you should be able to see the fee, the exchange rate, any applicable taxes, and the exact amount your family will receive. Review everything before you hit send. Some service providers, like Común, offer in-app tools to help you calculate the costs before sending anything.
Compare the total cost:
A provider that charges no transfer fee but offers a weaker exchange rate can potentially cost more than one with a modest flat fee and a fair rate. The number that matters is what arrives on the other end.
If you have a US bank account or debit card, ask your provider about your options:
Transfers funded from a US bank account or US-issued debit or credit card are exempt from the tax under the current statute.
Ask your provider directly how they handle the tax:
Some providers may have updated their apps, websites, or agent instructions. If you're sending via a digital channel linked to your US bank account or debit or credit card, ask whether that payment method qualifies for the statutory exemption.
Manage your remittances confidently with Común
Having an account to receive electronic payments, track your spending, and send money directly may help make managing your financial life in the U.S. more convenient. Común accepts more than 100 valid Latin American IDs to open a debit account. With Común you get:
- A $2.99 flat fee per remittance transfer, with no hidden charges
- A checking account held at Community Federal Savings Bank, Member FDIC. Deposits are FDIC insured up to the applicable limits
- Transparent, in-app pricing where you can see exactly what each transfer will cost, including fees and the exchange rate, before you confirm
- 24/7 customer support in Spanish
- Cash pickup options for your recipient
- The ability to send transfers from the comfort of your phone
To learn more about Común's remittance services, visit comun.app/remittances.
FAQ
What is the new 1% Remittance Tax?
It is a federal excise tax introduced by the One Big Beautiful Bill Act (OBBBA), Public Law 119-21, codified as IRC Section 4475. It imposes a 1% tax on certain outbound money transfers from the United States to recipients in foreign countries. It applies only to transfers funded with cash, money orders, cashier's checks, or similar physical instruments.
When does the new remittance tax take effect?
The tax applies to remittance transfers made on or after January 1, 2026. It was signed into law on July 4, 2025, as part of the OBBBA. The IRS granted penalty relief to providers for the first three quarters of 2026, with full enforcement expected beginning Q4 2026.
Who has to pay the 1% tax?
The tax is owed by the sender, but it is collected and remitted to the IRS by the remittance transfer provider at the time of the transfer. It applies to all senders, regardless of citizenship or immigration status.
Are all money transfers from the US subject to the new tax?
No. The tax applies only to transfers funded with cash or physical instruments. Transfers funded from a US bank account at a Bank Secrecy Act–compliant institution, or paid with a US-issued debit or credit card, are exempt from the tax by statute.
How is the tax collected?
The remittance transfer provider collects the 1% tax from the sender at the time of transfer. Providers must deposit collected taxes with the IRS on a semimonthly schedule and file quarterly returns using Form 720.
How can I tell if my transfer is taxable?
It depends on how you're funding the transfer. If you are paying with cash, a money order, or a cashier's check at a remittance agent, the 1% tax likely applies. If you are sending money through a digital app or bank account using your US checking account or a US-issued debit or credit card, the transfer may be exempt under the current statute. Ask your provider directly to confirm how your specific payment method is classified.
International Money Transfers
Remittance services: how to send money to Latin America
8 min de lectura
Remittance services: sending money to Latin America
For millions of Latin Americans living in the United States, sending money back home is part of everyday life. For many, their families and friends back home often depend on fast and reliable remittances from the United States. Today, there are many service providers for sending money to Latin America available in the market, each offering different advantages and disadvantages and choosing the right one is key to make the most out of your hard-earned money. A useful approach is to understand how remittance pricing works, what factors affect the total cost, and how to compare the services based on your specific needs.
How to measure the real cost of a remittance?
The real cost of a remittance is determined by different elements:
- The transfer commission.
- The exchange rate being offered at the moment.
- Additional service fees.
- Delivery method.
- Transfer speed.
- Promotional pricing conditions.
In practice, the exchange rate often has the biggest impact on how much money the recipient actually receives. For example, two providers may advertise similar fees while delivering noticeably different final amounts because of the FX spread built into the exchange rate.
What is the FX spread?
The FX spread is the difference between:
- The real market exchange rate (this is also called the mid-market or interbank rate)
- The exchange rate the service provider gives you
This difference is where some remittance service providers generate revenue. The same reason why two services with the same "$0 fee" can have very different final costs.
The most popular remittance services used by Latin Americans in the U.S.
Different services work better for different types of users. Here you can find a general overview of the providers most commonly used by the Latino communities in the United States.
Western Union
Western Union is one of the largest remittance companies in the world, with an extensive cash pickup network across thousands of locations in Latin America.
Strengths:
- Large global network
- Cash pickup availability
- Multiple delivery methods
Limitations:
- Exchange rates may vary significantly
- Fees depend on payment method and destination
Ria Money Transfer
Ria Money Transfer offers payments from the US to more than 165 countries across the world, with delivery options including cash collection and delivery to either a mobile money wallet or bank account.
Strengths:
- Wide coverage
- Competitive options in some corridors
- Cash pickup availability
Limitations:
- Pricing varies depending on country and delivery method
- Exchange rate competitiveness changes daily
MoneyGram
MoneyGram is a service provider of international remittances that enables individuals to send and receive money internationally and domestically.
Strengths:
- Extensive cash pickup network
- Fast transfers in some cases
- Availability in multiple countries
Limitations:
- Fees and FX spreads can vary widely
- Final cost depends heavily on transfer method
Félix Pago
Félix Pago is a WhatsApp-based platform focused on servicing the Latino community in the U.S. to send money throughout Latin America.
Strengths:
- Mobile-first experience
- Speed and convenience
Limitations:
- Coverage and features may vary by destination
- Transfer economics depend on corridor and timing
- Not every user prefers chat-based transfers
Común
Común offers the possibility to open a debit account in the USA and send money home from Común's app or WhatsApp.
Strengths:
- Spanish-first app and customer support
- Convenient with a mobile-focused experience
- Promotional FX rate available on the first transfer
- Accepts more than 100 Latin American IDs to open a debit account
- Transparent fees
Limitations:
- Exchange rates and transfer costs vary daily
- The final recipient amount depends on the destination country, transfer method, and market conditions
Remittance services: a general comparison
Today, the remittance service provider market in the U.S. can be divided into two major categories:
Traditional remittance agencies
Companies that offer physical networks and cash pickup infrastructure. For example: Western Union, Ria Money Transfer or MoneyGram.
Fintech alternatives
These platforms focus on mobile experience, transparent pricing, digital account management, accessibility for immigrants in the U.S. and some offer Spanish-first experiences. Examples: Común and Félix Pago.
Why do comparisons matter?
Exchange rates change every day and promotional offers can also change. This is why it's important to compare what's the best service provider for your current situation. If possible, it is recommended to use a tool to have a better perspective on your remittance costs. For example Común has a live calculator at comun.app/compara designed to help you understand the exact conditions of your transfer.
Beyond the exchange rate
For many immigrants in the United States, choosing the best remittance services is not just based on who offers the best exchange rate. The accessibility to the services can shape the entire experience of sending money. Some people may not have a Social Security Number, a traditional U.S. bank account, or an easy way to verify their identity through conventional financial systems. Language can also play an important role for navigating financial apps especially with customer support and understanding the specific transfer policies. Being able to do financial transactions in a native language can make transactions feel less stressful.
The competitive market landscape in the U.S. makes it possible for Latin American immigrants to compare options for their remittances. Today, you can look beyond the exchange rate and consider factors like Spanish-language support, flexible identification requirements, mobile accessibility and transparency around fees and/or transfer conditions. The best remittance service provider is the one that offers pricing, services and access that fit your needs. Común's app is available in Spanish, accepts more than 100 Latin American IDs and offers transparent fees.
How to choose the right remittance service for your situation?
There is no universal "best" remittance provider. The right option depends on how often you send money, where you are sending it, how your recipient receives the funds, and what kind of financial access you have in the United States. Choosing based on your own priorities is often the best path.
If this is your first transfer
Many remittance services offer promotional pricing or preferred exchange rates for first-time users. These promotions can temporarily improve the amount received by your family, but they do not always reflect the long-term cost of using the platform.
For example, some digital services may offer stronger FX rates on the first transfer, while traditional providers occasionally waive transfer fees for new customers. However, the total value still depends on the exchange rate, transfer speed, and delivery method.
Before sending your first remittance, it is important to consider:
- The final amount your recipient will receive
- If the promotion applies to your destination country
- Delivery times
- Bank deposit vs cash pickup options
To compare exchange rates you can always use a tool, for example, comun.app/compara is designed to help people understand the cost of their transfer.
If you do not have an SSN
Access to financial services can vary significantly for immigrants in the United States, especially for people who do not have a Social Security Number. This can make onboarding slower or more complicated for recent immigrants, ITIN holders, or people primarily using foreign identification documents.
Some remittance service providers have adopted more flexible verification models. Común, for example, accepts more than 100 Latin American IDs. It is recommended to check with every institution their specific verification requirements.
If you send money regularly
People who send remittances every month can benefit more from consistency than from temporary promotions. For frequent senders, it can be useful to review:
- Ongoing exchange rates
- Fee transparency
- Recurring transfer options
- Convenience: for example mobile app or WhatsApp transfers
- Customer service availability
If your family depends on cash pickup
Cash pick-up continues to play a major role across many parts of Latin America, especially in smaller cities or rural communities where bank access may be limited.
Traditional remittance companies like Western Union, Ria Money Transfer, and MoneyGram offer large physical networks that allow recipients to collect money in person at supermarkets, convenience stores, banks, and local partner locations.
Before choosing a provider, it is helpful to verify:
- Whether cash pickup is available in the destination city
- Pickup hours and accessibility
- Transfer speed
- Identification requirements for recipients
- Maximum transfer limits
In some cases, the best service is simply the one your recipient can access easily. Común offers cash pick ups with options in some stores and banks.
If you prefer convenience: mobile-first experiences
Over the past years, mobile-first experiences have become popular given the convenience of being able to send remittances from one's mobile phone.
Digital-first services can offer:
- Faster onboarding
- Mobile transfers
- Real-time notifications
- Simpler account management
Platforms like Común and Félix Pago are examples of services designed around mobile experiences for Latino immigrants. For people who feel more comfortable managing their transfers from their phones, these platforms can feel faster and more convenient.
FAQ
What is the cheapest service to send remittances to Latin America?
There is no single service that is always the cheapest. Costs depend on exchange rates, transfer fees, destination country, payment method, and whether you qualify for a first-transfer promotion. The best way to verify your exact case is to compare providers.
What is the FX spread and why does it matter when sending remittances?
The FX spread is the difference between the real market exchange rate and the exchange rate offered by the remittance provider. A weaker exchange rate can reduce the amount your recipient receives.
How can I verify the real cost before sending a remittance?
The best way is to compare the total recipient amount, exchange rate, fees, and promotional conditions before sending money. Some service providers offer tools that calculate the costs before sending the remittance. Común's live comparison calculator is designed to help users verify this information in real time.
Do all remittance services offer cash pickup options?
No. Some remittance providers specialize in bank deposits or digital wallet transfers, while others maintain extensive cash pickup networks across Latin America. Before sending money, it is important to confirm how your recipient prefers to receive funds and whether pickup locations are accessible in their area.
Why do exchange rates change between remittance providers?
Each provider sets its own exchange rates based on market conditions, operating costs, transfer corridors, and promotional strategies. Because rates can change daily, comparing providers before each transfer can help users better understand the total cost of sending money.
Final thoughts
The remittance industry has changed significantly over the past decade, today sending money to Latin America is no longer limited to one type of service or provider. Immigrants in the United States can choose between traditional cash pickup networks, digital-first platforms, and hybrid financial services depending on what works best for their families.
For many people, the real value comes from the full experience from the convenience of usage, accessibility to the services and knowing exactly how much money will arrive can matter just as much as costs. Común offers transparent pricing, an app available in Spanish and a comparison tool that helps users review transfer costs before sending money.
Financial Education
How to fill out a check in the United States in 5 simple steps (+ Example)
8 min de lectura
Have you ever filled out a check? Although most transactions today are digital, knowing how to fill out a check is essential—especially if you are just beginning your financial life.
According to recent data, one-third of Americans paid by check in 2024, demonstrating that checks still play an important role in the U.S. economy.
You might consider checks an outdated payment method; the reality is that they are useful in specific situations. For that reason, we will explain what a check is, the different types of checks, and how to complete them properly.
What Is a Check and What Is It Used For?
Despite the digital era, checks remain a relevant traditional payment method due to their formality and traceability. They are used for rent payments, purchases, and service payments.
Additionally, checks are a common payment method among the immigrant community, who often use them while adapting to the U.S. banking system.
But what exactly is a check and what are its characteristics? It is a physical document issued by an individual or business (the drawer) to order a bank to pay a specified amount to a third party. For the payment to be processed, the drawer must have sufficient funds in their checking account.
In general, a check contains the following information:
- Name of the drawer, whether an individual or a business
- Name of the payee
- Financial institution where the money will be drawn
- Amount to be paid, both in numbers and in words
- Signatures of the drawer
What Are the Different Types of Checks?
There are different types of checks in the United States. In this case, we will focus on the personal check, although you may choose the option that best suits your needs.
Personal Check
A personal check is a payment order issued by an individual to another individual using the funds in a checking account.
What Is a Personal Check Used For?
The most common uses for personal checks include:
- Rent and utility payments
- Purchase of everyday goods
- Legal agreements requiring documentary support
Certified Check
A certified check serves the same purpose as a personal check but is reviewed and guaranteed by the issuing bank, which verifies that the drawer has sufficient funds and holds them until the check is cashed.
A certified check provides certainty of available funds, making it a more secure method for making and receiving payments.
Cashier’s Check
Unlike a personal check, a cashier’s check is issued directly by the bank, offering greater security for the payee, as the bank is responsible for issuing and safeguarding the funds.
To obtain a cashier’s check, the drawer must visit a bank branch and pay the amount to be transferred. The bank then issues the check in the name of the payee, guaranteeing that it can be cashed using the institution’s own funds and not a personal account.
It is commonly used for high-value purchases such as homes and vehicles.
Money Order
While not strictly a check, it is a traditional payment method with similar functionality.
A money order is a financial instrument that allows funds to be sent via traditional mail using a certified check, which must be purchased and paid for by the drawer at an authorized location.
It allows secure money transfers without requiring a bank account.
How to Fill Out a Check in the U.S.
Before issuing this type of payment order, you must know how to do it properly. Below is an example of how to fill out a check easily, starting from step one:
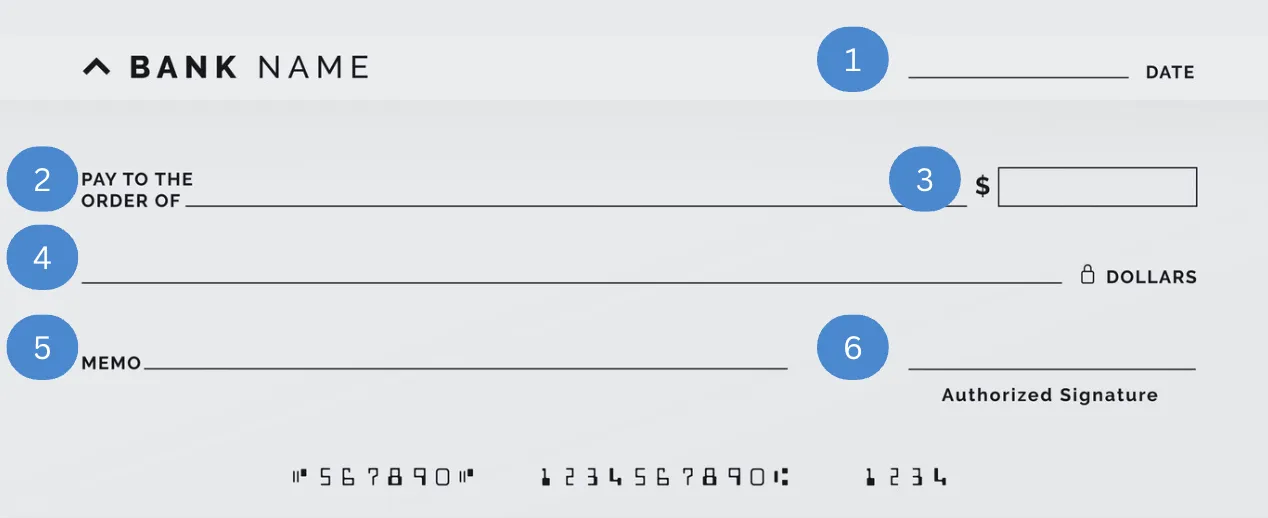
1. Write the Date
Remember that in the United States, the date format is mm/dd/yyyy.
2. Payee’s Name
Write the full name of the person to whom you are issuing the check, exactly as it appears on their official identification.
3. Amount in Numbers
Write the numerical amount clearly.
4. Amount in Words
Write the amount in words, including cents.
5. Add a Memo
You may include a note specifying the reason for the payment.
6. Sign the Check
Sign the check legibly in the space designated for the drawer.
7. Review the Information
Ensure that all information is accurate to avoid issues for the payee when cashing the check.
It is essential to complete checks legibly, without strike-throughs or corrections, as these may invalidate the document.
How to Correctly Write Numbers in Words on a Check
Writing amounts in words may be confusing when dealing with U.S. dollars. The following points should be kept in mind:
- Dollar amounts must be written in full words
- Cents must be written as fractions
- Avoid using dollar symbols or similar notations
- If there is leftover space at the end of the line, draw a line to prevent fraud
- For example, $1,000.75 is written as: One thousand and 75/100 dollars
Cash Checks and Manage Your Money Easily with Comun
As you can see, knowing how to fill out a check is useful for sending and receiving money in the United States. It is a reliable and accessible alternative if you do not have a banking account.
However, issuing and cashing a check can also require significant time and effort. That’s why you can skip the trip to the bank, avoid wasting time or money on gas, and cash your check directly from your phone using Comun—no lines, no questions, no complications.
Discover Comun, the only platform designed to serve the needs of immigrant communities in the United States, with support available in Spanish.
Why Choose Comun?
- Open your account with an official ID from your country
- Access a mobile app specifically designed for immigrants in the U.S.
- Make payments, receive your salary, and manage your finances
- Send money to your loved ones in LATAM for just a $2.99 transfer fee
Frequently Asked Questions
Still have questions about how to fill out a personal check? See our FAQ section.
What if I Make a Mistake Filling Out a Check?
If there are strike-throughs or inconsistencies in the amounts, the check must be voided and a new one used.
How Do I Void a Check?
Write the word VOID in large letters on the front of the check.
What Information Appears on the Back of a Check?
The back of the check contains the endorsement, meaning the payee’s signature for cashing the check.

Checking account
How to Identify Where to Deposit Cash
8 min de lectura
To deposit cash with Común, open the app, go to the "Cash" section and then "Deposit" to see all nearby locations on the map. You can generate a barcode and deposit without needing your physical card.
Depositing cash into your Común account is simple and convenient. Whether you prefer using your physical card at an AllPoint+ ATM or generating a barcode in the app, here is a step-by-step guide to help you understand both methods.
Using a Physical Card
Step 1: Wait for Your Physical Card
After opening your online bank account, your physical debit card will be mailed to your home. This usually takes 7 to 10 business days.
Step 2: Activate Your Card
Before you can use your card, make sure to activate it through the Común app. Your card must be active for any transaction.
Step 3: Locate an AllPoint+ ATM
AllPoint+ ATMs are part of a broad network of ATMs, perfect for cash deposits. Here is how to find one:
- Open the Común app.
- Go to the "Move Money" section.
- Use the map to locate the nearest AllPoint+ ATM. These machines are usually found at popular retail locations.
Step 4: Deposit Cash at an AllPoint+ ATM
Once you are at the ATM:
- Insert your activated card.
- Follow the on-screen instructions to deposit cash into your checking account. Please note that deposits can only be made into checking accounts, not savings accounts.
- Make sure your deposit is within the limits: up to $250 per deposit and up to $1,000 per day, including deposits and withdrawals.
Tip: If there are no AllPoint+ ATMs near you, do not worry. You can also deposit cash using a barcode at many other locations!
Using the Barcode in the App
Step 1: Generate a Barcode
Here is how to generate a barcode in the Común app:
- Open the app and go to the "Cash" section.
- Select the option to generate a barcode for deposit.
- The barcode will appear on your screen, ready to use.
Step 2: Find Locations That Accept the Barcode
To find a nearby location that accepts the barcode:
- In the "Cash" section, look for the list of participating locations.
- You can also use the map feature to find the nearest store.
Step 3: Using the Barcode
Take your barcode to a participating location and show it to the cashier. They will scan the barcode, allowing you to deposit your cash.
Important Details:
- Expiration: The barcode expires after 15 minutes, but you can generate as many as you need.
- Limits: Keep in mind the deposit limits that may apply when using the barcode method.
Troubleshooting ATM Transactions
Problems Depositing Money
When troubleshooting ATM transactions, especially problems depositing money, it is important to make sure you are using an AllPoint+ ATM, since these machines do not charge fees for deposits. Your physical card must be activated; if it is not, you can easily activate it from the app. Also, make sure you enter the correct PIN. If you do not remember your PIN, you can view it or change it in the app settings section. Verify that your deposit is within the limits, which are up to $250 per deposit and up to $1,000 per day. Finally, always select "checking account," since Común accounts are checking accounts, not savings accounts.
Problems Withdrawing Money
If you run into problems withdrawing money, first make sure you have enough balance by checking your balance in the app before making a withdrawal. Use an AllPoint+ ATM to avoid withdrawal fees, since other ATMs may charge a fee. Enter the correct PIN; if you do not remember your PIN, you can view it or change it in the app settings section. Verify that your withdrawal is within the limits, which are up to $250 per withdrawal and up to $1,000 per day, including deposits and withdrawals. If you continue having problems, contact us through the chat in your app for more help.
Alternative Deposit Methods
If you cannot find a nearby store to deposit cash, Común offers other options:
- Receive Money: Use apps like Zelle, CashApp, Venmo, or PayPal.
- Direct Deposit: Set up direct deposit with your employer.
- External Transfers: Send money to your Común account from an external bank or other financial institutions.
Additional Tips and Information
Fraud Prevention
Always keep your account number and PIN secure. Do not share this information with anyone to avoid unauthorized transactions.
Know Your Limits
Be aware of the deposit amount limits. For example, you can only deposit up to $250 per deposit and up to $1,000 per day. This helps you manage your funds and avoid any unexpected issues.
Use Común Features
The Común app provides a map to find the nearest ATMs and stores that accept barcodes for deposits. This feature helps you quickly locate convenient deposit points.
Stay up to date with the latest features and benefits offered by Común through the app, ensuring you get the most out of your online banking experience.
Cash Deposit Fees
Depositing cash at an AllPoint+ ATM has no fees, while other ATMs may charge a fee. Always check for possible fees before making a deposit.
Mobile Check Deposits
In addition to cash deposits, Común also supports mobile check deposits, adding more flexibility to the way you manage your money..
Conclusion
In short, depositing cash into a bank account is a practical decision driven by safety, convenience, possible earnings, financial management, and legal compliance. By understanding these reasons, people can make informed decisions about how to handle and manage their cash effectively, ensuring financial stability and growth.
Whether you use your physical card at an AllPoint+ ATM or a barcode in the app, depositing cash into your Común account is simple and convenient. Always make sure your card is activated, check nearby locations, and keep deposit limits in mind. With these steps, you will be able to manage your cash deposits effortlessly.
Do not worry, if there are no locations near you, you can also deposit with a barcode at many more locations! Visit Común for more details and get started with your deposits today.
By understanding the process and using the tools provided by Común, you will be able to handle your cash deposits effectively and ensure your funds are always accessible.
How do I find where to deposit cash near me?
In the app, go to "Cash" → "Deposit" to see the map with all available locations. Choose the closest one; if the location allows it, you can generate a code to deposit without a card.
Is there a limit on how much cash I can deposit?
Most stores have a $500 limit per transaction, though some allow higher amounts. If you deposit more than $300 at Walgreens or Walmart, you'll be asked for a U.S. government-issued ID.
What do I do if there's no location near me?
Check other locations on the app's map, or deposit at an AllPoint+ network ATM, which also accepts cash deposits.
Frequently asked questions
Do I need my physical card to deposit cash?
Not always — at many locations you can generate a barcode in the app and deposit using only your phone.
How much cash can I deposit per transaction?
Most stores have a $500 limit, though it can vary by location.
Do I need ID to deposit cash?
If you deposit more than $300 at stores like Walgreens or Walmart, you'll be asked for a U.S. government-issued ID.
Does depositing cash cost anything?
The cost can vary by store; check the details directly on the app's map before depositing.
Can I deposit cash at an ATM?
Yes, ATMs in the AllPoint+ network also accept cash deposits.
How do I know if a nearby location accepts Común deposits?
The map inside the "Cash" → "Deposit" section of the app shows you in real time which nearby locations accept deposits.
Living in the United States
How to Save on Groceries: 10 Tips for 2026
8 min de lectura
Saving on groceries without sacrificing quality is possible with simple strategies: comparing unit prices, taking advantage of seasonal deals, and using a fee-free account so you don't lose money to bank charges while you shop.
The impact of inflation on our food budget is no joke. Rising food prices make us look for more affordable alternatives. Discover how to save on food with these 10 tips to spend less at supermarkets and restaurants.
Set a supermarket budget:
- Set a limit for your supermarket purchases and look for deals before entering the store. Plan your meals and snacks based on the week's discounts. Try generic brands to save even more.
Be aware of sales tactics:
- Avoid marketing strategies that make you spend more. Do not shop when you are bored, tired, or hungry. Stay focused and stick to your shopping list.
- These are some of the aggressive tactics supermarkets use:
- Minimum purchases to receive a discount. Supermarkets advertise a cheap price when you buy a minimum quantity of a product. Sometimes it is two, three, or five. Many times the store honors the price if you buy individually. This is sorted out at the register.
- Anchoring. This happens when the sale price is strategically placed next to the regular price, making you feel like you are getting a bargain.
- Placing impulse buys at the end of each aisle and at checkout. You may add something to your cart that you do not need.
- Loss leaders. These are items advertised at very low prices. While you may get a deal on the sale item, the intention is for you to enter the store and buy more items at regular prices.
- These are some of the aggressive tactics supermarkets use:
Use coupons:
- Take advantage of apps and browser extensions to find coupons and discounts on your purchases, such as Honey, Dosh, or Ibotta.
Buy only essentials in bulk:
- Buy in large quantities only non-perishable and regularly used products, such as toilet paper or diapers.
Check the discount shelf offers:
- Look for discounted products in the meat and produce sections, as well as on your local supermarket's clearance shelves.
Check your pantry:
- Before going to the supermarket, check what you have at home and create dishes with those ingredients. Use apps like Kiwilimon to find recipes.
Use food-saving apps:
- Apps like Too Good to Go let you buy surplus food at reduced prices. Misfit Markets, Imperfect Foods, and GrubMarket offer food with cosmetic imperfections or surplus at lower prices.
Avoid food delivery apps such as Grubhub, Doordash, and Uber Eats because they charge many fees and inflate dish prices for delivery.
Eat out during lunch hour or happy hour:
- Take advantage of deals and special menus at bars and restaurants during these hours to save money.
Reduce how often you eat out:
- Limit your visits to restaurants and fast food, and focus on preparing meals at home. Meal planning can help you save money and eat healthier.
Space out your supermarket visits and choose just one store:
- Wait until you have used up most of your food before going to the supermarket, and choose a single store to avoid extra transportation expenses.
Remember that with Común, you can take full control of your finances and manage your money from your app. Común offers a checking account with more than 57,000 ATMs around the United States. At no cost. Saving you money is what we do best.
Saving on food is possible by following these 10 practical tips. Setting a budget, taking advantage of deals, and reducing how often you eat out will help you spend less at supermarkets and restaurants without sacrificing the quality of your food. Start saving today!
How do I save money on groceries without buying lower-quality products?
Compare the price per unit (not just the total price), buy seasonal produce, and take advantage of weekly deals instead of always buying the same items out of habit.
Do bank fees affect my grocery budget?
Yes — a monthly fee or out-of-network card charges reduce the money available for your shopping. With Común there's no monthly fee or charges for using your debit card.
What other habits help save on weekly shopping?
Make a list before you go, avoid shopping while hungry, and check your transactions after each shopping trip to catch duplicate charges or errors.
Frequently asked questions
How do I compare prices more effectively at the grocery store?
Look at the unit price (per ounce, per pound) printed on the shelf tag, not just the package's total price — sometimes the "bigger" package costs more per unit.
Is it worth buying in bulk?
Only if you'll use the product before it expires; otherwise the savings are lost to wasted food.
How do I avoid overspending on groceries?
Make a list before you leave and avoid shopping while hungry, since it increases impulse purchases.
Does Común charge anything for using my debit card in stores?
No, there are no charges for using your Común debit card on purchases.
How do I know if I was overcharged on a purchase?
Check your activity in the app after each purchase — real-time notifications help you catch errors quickly.
Does saving on groceries really make a big difference?
Yes — small weekly savings add up over time; cutting $20-30 a week can add up to over $1,000 a year.
Checking account
What do I need to open a traditional bank account as an immigrant?
8 min de lectura
For immigrants in the United States, having a banking account has become a basic necessity to carry out all types of daily tasks, such as shopping in physical and online stores, receiving wages, sending transfers and remittances, opening a savings account, among other things.
Despite the importance that a banking account has for immigrants and U.S. citizens, there are still factors that hinder the immigrant community’s access to banking, such as high fees and required documentation.
According to FDIC data, among vulnerable groups without banking accounts (unbanked), Hispanics make up 9.5%. This shows a gap that disadvantages a significant portion of the population.
Access to financial services is an increasingly attainable right for immigrants in the U.S. In this article, we will explain step by step what is required to open an account at a bank and on digital platforms, as well as the advantages of these solutions.
4 Requirements to Open a Banking Account in the United States
It is true that financial services make users’ lives easier and, in some way, improve their quality of life. But, what is needed to open a banking account in the United States?
Opening a bank account, whether a checking account or another type, requires meeting a series of requirements and presenting documentation, which may vary depending on the financial institution.
Some of the difficulties immigrants face when opening a banking account are not having an SSN (Social Security Number) or tax documentation, as well as the lack of information in Spanish.
Fortunately, beyond traditional banks, there are currently alternative solutions such as Común, a financial platform dedicated to meeting the needs of people who seek accessible and efficient services.
In general, these are the most common required documents to access a banking account in the United States.
Social Security Number (SSN)
This is the most common requirement for opening an account. It is an identifier for people who reside and work legally in the United States, and it is required for banks to carry out the identity verification process.
Individual Taxpayer Identification Number (ITIN)
The ITIN is an alternative for people who do not qualify for the SSN, since some financial institutions accept it instead.
Identity Document
For this requirement, it is possible to present a passport, a driver’s license, a government-issued ID, or a consular ID card. Any of these documents must be valid and show both name and photograph.
Proof of Address
To prove your residence in the United States, you can present utility bills, such as electricity, or even a digital account statement.
Step by Step: How to Open a Banking Account in the U.S. with Foreign Identification
The number of requirements requested by traditional institutions tends to make access to banking difficult, especially for immigrants without the previously listed documentation.
If you are looking for a practical and simpler solution than traditional banking services, you can turn to options like Común, the platform that streamlines processes and offers fair financial services for everyone.
Access to these services is possible with official, qualified foreign documentation, which helps reduce the gap in access to banking for immigrants.
Choose a Secure Platform that Accepts Foreign Identifications
In general, traditional banks request the SSN or ITIN, so a convenient option is to choose a digital platform with more flexible requirements but with the same quality and seriousness in their processes.
Común is a platform that makes immigrants’ lives easier in the United States, as it allows you to open an account with official, qualified documentation from your country of origin and simplifies the sign-up process without complicated paperwork.
Download the Mobile App and Set Up Your Account available in Spanish
You only need a mobile device compatible with Android or iOS to download the application, where you will create your profile and enter your information.
Verify your identity with an official ID from your country
Then, carry out the identity verification with your official ID from your country of origin. To do this, you will need to take a picture of it and possibly take a selfie.
Activate Your Card and Start Using Your Account
Once you provide the necessary documentation, you will have access to a debit card to make purchases at various establishments and will be able to make transfers and receive payments.
Use Additional Features Such as Sending Remittances or Deposits at Stores
For immigrants, it is essential to have services that allow them to send remittances to their countries of origin, so you can also use this benefit, in addition to making direct deposits in physical stores near you.
Which Bank in the U.S. Allows Opening an Account with a Passport? More Accessible Alternatives
There are alternatives with more flexible account opening options, such as Bank of America, which accepts the ITIN in case you do not have an SSN. However, the processes tend to be longer and slower compared to other digital platforms, which facilitate the sign-up process by offering greater feasibility in their requirements.
Bank of America
Bank of America supports the opening of banking accounts in the United States for immigrants, because it allows opening an account with a valid passport or ITIN. However, it is necessary to go in person to a branch to complete the process.
Común
Común is a digital platform that allows opening an account with more than 100 foreign IDs or with a valid passport, which makes it easier to obtain an account for immigrants and send remittances to Latin America for an affordable fee; in addition to making cash deposits at more than 100 stores.
Wells Fargo
Wells Fargo also accepts a passport as the main ID, but may request an additional identification, such as a credit card or student ID.
Wise
Wise is a fintech that offers digital accounts in different currencies. It is possible to access its services with a passport, ITIN, or SSN.
Revolut
Revolut is another alternative for non-citizens in the United States, since it accepts a passport as identification; among other options, such as a driver’s license or national ID.
Why Común is Ideal for Opening Your Account in the U.S.?
Although the requirements to open an account may make it seem like an inaccessible process for many immigrants in the U.S., fortunately, there are also more accessible options.
If you are looking for a clear, reliable alternative available in Spanish, it is time to change your relationship with finances through Común: a service that truly understands your needs.
Why is Común Your Ally?
Forget about minimum deposits or monthly charges
Access a mobile app available in Spanish with a user-friendly interface
Send money to your home country for a fee starting at $2.99, up to the applicable limits
Deposit cash at a network of establishments near you
It has 24/7 customer support available in Spanish
Remember that Común offers you a service available in Spanish with simple processes. Open your account today and start using a service designed for you!
Community
What You Need to Open an Account at Comun¹ 2
8 min de lectura
Unmatched Ease of Opening an Account
Opening a checking account with Comun is simple and hassle-free, addressing the barriers to financial exclusion typically faced by the immigrant community. Accepting over 100 forms of identification², including social security numbers from Latin American countries, Comun ensures that immigrants have access to essential banking services. The application process is quick, taking less than 5 minutes, and is free of additional or hidden fees, minimum balance requirements or monthly commissions. This inclusiveness is central to Comun's mission of fostering financial stability and growth.
Mobile Deposit Options
ComunComun offers a convenient mobile deposit feature that allows users to deposit cash at more than 88,000 locations in the United States, including major retailers such as Walgreens, Dollar General and Walmart. This extensive network ensures that users can easily find a deposit location near them, making the process of adding money to their accounts simple and hassle-free.
Traditional Banking: Although many traditional banks offer mobile deposit options, they often restrict these to check deposits through a mobile app. Cash deposits typically require a visit to an ATM or bank branch, which can be less convenient and more time-consuming than Comun's extensive cash deposit network.
Utility in Today's World: In today's fast-paced environment, the flexibility to deposit cash in a wide range of accessible locations is invaluable, especially for individuals who may not have easy access to traditional banking services or who work non-traditional hours when banks are closed.
International Remittances
ComunComun excels in facilitating international remittances⁴, allowing users to send money abroad quickly and with lower fees compared to many traditional banks and remittance services. The process is enhanced with real-time notifications, keeping the sender informed from the moment the money is sent until it is received.
Traditional Banking: Traditional banks generally offer international transfer services, but these can be expensive and slow, with transfers sometimes taking several days to complete. In addition, the fees associated with traditional bank remittances can be significantly higher.
Usefulness in Today's World: In a globalized economy, the ability to send money across borders quickly and affordably is crucial. Many families rely on remittances for financial support, and businesses need efficient ways to handle international transactions. Comun's streamlined and cost-effective service effectively meets these modern demands.
Advance Salary Access
Comun: Comun offers the ability to connect wages to the application and receive payment up to two days in advance³. This feature incurs no additional fees, providing significant relief during financial emergencies or when planning ahead.
Traditional Banking: Some traditional banks have begun to offer similar features, but they are often tied to specific types of accounts or require a minimum balance. The accessibility and ease of use of early access to Comun's salary is not always matched in traditional environments.
Usefulness in Today's World: With the rise of gig economy jobs and irregular pay schedules, having early access to wages can provide a buffer against financial instability. This feature is particularly valuable for those living paycheck to paycheck, offering a cushion that can help avoid overdraft fees and late payments.
Unlike traditional banking institutions, Comun's innovative features are designed to meet the needs of today's diverse and mobile population, particularly benefiting the immigrant community in the U.S. By providing services that offer greater convenience, lower costs and greater accessibility, Comun not only addresses common challenges faced by its users, but also empowers them toward greater financial freedom and stability. As we move toward a more interconnected and fast-paced world, the importance of responsive and inclusive financial services continues to grow, something Comun is uniquely positioned to offer.
Robust Security and Customer Support
Security and customer support are paramount at Comun. With FDIC-insured accounts and Visa protection on virtual Visa debit card transactions, Comun customers can manage their funds with confidence. Innovative security features such as biometric logins and instant transaction notifications keep your money safe. In addition, Comun offers 24/7 customer support in English and Spanish, ensuring that help is always available in your preferred language.
Commitment to Zero Fees and Upward Mobility
Comun stands out not only for offering zero fees for account opening, monthly maintenance or minimum balances, but also for its commitment to helping its users move up the financial ladder. Comun acts as a financial partner, supporting financial transactions without the burden of excessive fees. This commitment aligns with the goal of enabling upward mobility for immigrants, who contribute significantly to the U.S. economy.
Customized Features and Benefits
Comun goes beyond traditional financial services by offering features designed to meet the unique needs of the immigrant community. Users can send money abroad with low or no fees, deposit cash at more than 88,000 locations nationwide, including free ATM withdrawals, and connect their accounts to popular payment apps such as Zelle, CashApp and Venmo. Comun's platform also allows customers to receive their paychecks up to two days early through direct deposit, further enhancing their financial flexibility and stability.
Conclusion
Comun is not just a financial services provider, but a platform dedicated to transforming the banking experience for immigrants in the U.S. With its user-focused design, commitment to financial freedom and robust features, Comun is destined to become a vital tool for achieving financial stability and growth for its users. Whether you are looking to manage your daily finances or send money to loved ones abroad quickly and securely, Comun offers a reliable, inclusive and efficient banking solution.
Foundational Moment: Did you know?
Founded by entrepreneurs Mark Selcow and Andres Santos in New York, Comun was built to empower families and enable upward mobility, particularly for the immigrant family. The company has garnered significant investment from prominent firms such as Costanoa Ventures, FJ Labs and South Park Commons, underscoring the tremendous opportunity to serve the financial needs of immigrant families and improve the lives of every individual.
Checking account
Prepaid card vs. debit card: what's the difference?
8 min de lectura
A prepaid card is loaded with money in advance and generally is not linked to a traditional checking account. A debit card is linked to a checking account, and money is taken directly from the available balance in that account. A debit card is generally connected to additional banking features, such as account statements, direct deposit, and other account services.
The main difference is their connection to a bank account, as a debit card draws funds directly from a checking account, while a prepaid card requires you to load money onto it in advance. Neither prepaid cards nor debit cards typically help you build a credit score because they generally are not reported to the major credit bureaus.
What is a prepaid card?
A prepaid card is a payment card that must be loaded with funds before it can be used. Spending is limited to the amount loaded onto the card. They are commonly available through retail stores and financial service providers.
Prepaid cards are commonly used for everyday purchases, online payments, and sending or receiving limited funds. Prepaid cards can be reloadable, meaning you can add money again after spending the balance. Some also allow direct deposit, but the features available depend on the provider.
Because prepaid cards are generally not linked to a traditional checking account, they may not include features such as full account statements, overdraft services, or other banking features. Available services vary by provider.
What is a debit card?
A debit card is linked to a checking account. When a purchase is made, the money is taken directly from the account balance.
Debit cards are commonly used for daily spending, online purchases, ATM withdrawals, and bill payments. They are also commonly used for receiving income through direct deposit from employers or other payment sources.
Because the card is connected to an account, all transactions are recorded in account statements. These statements can be used to track spending, income deposits, and account activity over time.
A debit card generally reflects your available account balance as transactions are processed.
Prepaid card vs. debit card: main differences
Prepaid cards and debit cards can look similar in everyday use, but they operate in different ways behind the scenes. The comparison below breaks down how each one works across key features such as account access, fees, deposits, and financial tools. Común’s debit card is included to be used as an example of a debit card.
| Feature | Prepaid Card | Debit Card | Común Debit Card |
|---|---|---|---|
| Linked to checking account | No | Yes | Yes |
| FDIC insured | Varies by provider | Yes, if linked to an FDIC insured checking account | Yes, through Community Federal Savings Bank, Member FDIC |
| Direct deposit | Limited | Available, depending on the account | Yes, with early access options |
| Monthly fees | May apply, depending on the provider | Varies by provider | No monthly fee |
| Reload fees | May apply, depending on the provider | Not applicable | None |
| Account statements | Not available | Available through account | Available through account |
| Open without SSN | Many prepaid cards require SSNs | Varies by provider | Yes, eligible customers may apply using a passport or certain Latin American IDs |
| Overdraft protection | Generally no | Varies by account | Generally no |
This comparison shows how prepaid cards and debit cards differ in structure, cost, and financial features, especially when it comes to account access and long-term use. A debit card linked to a checking account can offer more functionality, including direct deposit and account statements. Eligible customers can open a Común checking account using a Passport or certain Latin American IDs.
What are the disadvantages of prepaid cards?
Prepaid cards can be useful for basic spending, but they can have limitations depending on how they are used.
One common limitation is cost structure. Many prepaid cards may charge fees for adding money, withdrawing cash, or maintaining the card. The types and amounts of fees vary by provider.
Some prepaid cards also have limits on deposits, withdrawals, or transfers.
Another limitation is access to financial features. Prepaid cards usually do not include all of the features available with a traditional checking account, such as detailed account statements, bill payment tools, or other banking services.
Can immigrants get a debit card without a Social Security Number?
Some financial institutions and service providers allow individuals to open accounts using alternative identification instead of a Social Security Number. Accepted identification varies by institution and may include a passport or other forms of government issued identification.
Verification is still required to confirm identity under U.S. financial rules, but the documents accepted can vary by provider.
Once the account is approved, a debit card is issued and linked to the checking account. It can then be used for purchases, withdrawals, and direct deposits.
In the United States, some financial service providers accept different forms of identifications for their verification process. For example, Común accepts passports and more than 100 Latin American IDs to open an account.
When does it make sense to use a prepaid card?
A prepaid card can be useful for basic spending, short-term use, or situations where a traditional checking account is not available.
It can also be used as a budgeting tool since spending is limited to the loaded balance.
Some people use prepaid cards as a first step in the U.S. financial system before moving toward debit accounts with more features.
How to switch from a prepaid card to a debit card
Switching from a prepaid card to a debit card usually involves opening a checking account and moving recurring payments or deposits to the new account.
Once the account is open, money can be added through direct deposit, transfers, or other supported methods depending on the provider.
Some users keep their prepaid card active during the transition period while updating payment information across services.
If you’re considering switching from a prepaid card, Común offers a checking account with a debit card that eligible customers can open using a passport or accepted Latin American IDs. The account doesn’t have any minimum balance requirements or monthly maintenance fees.
FAQ
Is a prepaid card the same as a debit card?
No, a prepaid card is loaded with money in advance and is not connected to a checking account. A debit card is linked to a checking account and uses the available balance in that account.
Can I use a prepaid card to build credit?
Prepaid cards generally do not build credit because purchases are not typically reported to the major credit bureaus.
What are the fees on a typical prepaid card?
Fees can include monthly maintenance charges, reload fees, and ATM withdrawal fees. The exact cost depends on the provider.
Can I get a debit card without a Social Security Number?
Some services allow account opening using alternative identification such as a passport or national IDs, depending on verification requirements.
What do I need to open a debit card account as an immigrant?
Requirements typically include a valid form of identification, personal information, and verification steps required by the financial provider.
Común is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank, Member FDIC. The Común Visa® Debit Card is issued by Community Federal Savings Bank, pursuant to a license from Visa U.S.A. Inc. and may be used everywhere Visa Cards are accepted.
No minimum balance requirements or monthly maintenance fees. ATM or transfer fees may apply. See app for fee details.
Direct deposit funds are typically available when we receive the payment file, up to two days before the scheduled payment date. This early availability is not guaranteed.
Funds in your account are FDIC insured up to applicable limits by ownership category through Community Federal Savings Bank (CFSB), Member FDIC, in the event CFSB fails.

Financial Education
How to renew your ITIN: step-by-step guide
8 min de lectura
How to renew your ITIN: step-by-step guide
Your ITIN may have expired if you have not used it on a federal tax return for three consecutive tax years. To renew it, you must submit Form W-7 to the IRS, which is the same form used to apply for a new ITIN. You do not need to wait until tax season to start the renewal process, and you can submit your renewal before filing a tax return.
When does an ITIN expire?
An ITIN (Individual Taxpayer Identification Number) is a 9-digit tax processing number issued by the IRS. It is designed specifically for individuals who need to report income and file taxes in the United States but are ineligible for a Social Security Number (SSN).
An ITIN expires when it has not been used on a federal tax return for three consecutive tax years. The IRS explains that the expiration takes effect on December 31 of the third year of non-use.
An ITIN does not expire because time has passed, but because it has not been used for federal tax filing. Once expired, the number remains the same and can usually be renewed rather than replaced. An expired ITIN does not erase previous tax filings or financial records associated with it.
How do you know if your ITIN has expired?
One sign that an ITIN may have expired is not having filed a federal tax return with that number for several years. If three consecutive tax years have passed without using the ITIN, the number may no longer be active according to current IRS rules.
The IRS may also send a notice informing you that your ITIN needs to be renewed. Receiving a renewal notice does not mean there is a problem with your record. It simply means the IRS has determined that renewal is required before the number can be used again for tax filing purposes.
Tax software may also indicate that an ITIN has expired when preparing a return. If you are unsure if your ITIN has expired, checking IRS correspondence or reviewing past tax filings can also be a way to confirm status.
What happens if your ITIN expires?
An expired ITIN can delay the processing of a federal tax return. According to the IRS, certain tax credits and benefits associated with a return may not be available until the ITIN has been renewed.
An expired ITIN does not cancel previous tax filings, change your tax history, or create a new tax identity. The IRS maintains records associated with the original number even if that number has expired due to non-use.
An expired ITIN also does not automatically affect financial accounts that were opened using that number. However, an active ITIN may be required when completing future tax-related paperwork or applying for certain financial products and services.
If your ITIN has expired, the most practical step can be to start the renewal process before filing your next federal tax return. Taking action early can help avoid delays and additional paperwork during tax season.
What do you need to renew your ITIN?
To renew an ITIN, you must complete Form W-7 and mark it as a renewal application.
You also need documentation that proves identity and foreign status. The IRS lists acceptable documents in its official instructions, which include: passport, U.S. Citizenship and Immigration Services (USCIS) photo identification, visa issued by the U.S. Department of State, U.S. driver's license, foreign driver's license, foreign military identification card, national identification card (must contain name, photograph, address, date of birth, and expiration date), among others.
If your legal name has changed since your ITIN was issued, supporting documentation such as a marriage certificate or court order may be required.
How to renew your ITIN: step by step
1. Complete Form W-7
Fill out Form W-7 and indicate that you are renewing an existing ITIN. Make sure all personal details match your official documents.
2. Gather required documents
Collect identification documents that prove identity and foreign status. The IRS outlines acceptable documents in the Form W-7 instructions.
3. Attach supporting documentation
Include any additional documents required for your situation, such as name change records or prior IRS notices.
4. Submit your application
You can submit Form W-7 by mail, through an IRS-certified Acceptance Agent, or at select IRS Taxpayer Assistance Centers.
5. Wait for IRS processing
The IRS reviews the application and supporting documents before issuing confirmation. Keep copies of everything submitted for reference.
How long does ITIN renewal take?
Processing times vary throughout the year, but the IRS currently advises applicants to allow approximately seven to eleven weeks to receive notification regarding an ITIN application or renewal. Processing may take nine to eleven weeks during peak tax season or when applications are submitted from outside the United States.
Submitting a complete application can help prevent unnecessary delays. Applications that are missing required documents may take longer because the IRS must request additional information before processing can continue.
Can Común help me renew my ITIN?
Yes. Común's ITIN service helps with both new ITIN applications and ITIN renewals.
Común's ITIN service costs $199 and includes guidance throughout the renewal process. The service works with IRS-certified agents who help prepare the required paperwork, explain the requirements, and answer questions in Spanish.
The process can be completed from your phone, making it easier to organize documents and track progress without visiting multiple offices. Común also offers a money-back guarantee if the ITIN application is not approved according to the program terms.
FAQ
Do all ITINs expire?
Not all ITINs expire immediately or at the same time. An ITIN expires if it has not been used on a federal tax return for three consecutive tax years.
Can I renew my ITIN without filing taxes?
In some cases, yes. The IRS allows exceptions where Form W-7 can be submitted without a tax return depending on eligibility.
What form do I use to renew my ITIN?
You use Form W-7 for both new applications and renewals.
How long does it take to renew an ITIN in 2026?
The IRS estimates about seven weeks for processing. Processing may take approximately nine to eleven weeks during tax season or for certain international applications.
Can I still use my Común account if my ITIN expires?
An expired ITIN does not erase your financial history. If you have questions about how an expired ITIN may affect your specific account, contact Común directly for guidance.
What happens to my tax refund if my ITIN expires?
If an ITIN is expired, the IRS may delay processing a return until it is renewed. Certain tax benefits may not be available until the ITIN has been renewed, which can affect the timing of a refund.
Común is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank, Member FDIC. The Común Visa® Debit Card is issued by Community Federal Savings Bank.
International Money Transfers
How much does it cost to send money to Guatemala from the United States? A 2026 guide
8 min de lectura
The total cost may depend on three main factors: the transfer fee, the exchange rate used to convert USD to Guatemalan quetzales (GTQ), and any charges applied when the recipient receives the money. The total cost can vary from one transfer to another, depending on the provider and delivery method.
For many Guatemalans living in the United States, sending money back home is important. Some people support their families by covering everyday expenses or helping during emergencies. According to the World Bank, Guatemala is the second-largest recipient of remittances in the Latin America and Caribbean region, after Mexico. Remittances play a vital role in supporting rural communities in Guatemala, which receive over half of total flows.
Today, there are many ways to send money to Guatemala from the United States, including banks, cash pickup services, and apps and digital platforms. Comparing costs, delivery times, and exchange rates before sending can help your family receive more money overall.
How much money can you send to Guatemala?
The amount you can send to Guatemala may depend on the provider you choose, your account verification level, and the payment method used for the transfer.
In general, there is no single universal limit imposed on personal remittances from the United States. However, money transfer companies and financial institutions usually apply their own transfer limits as part of fraud prevention and regulatory compliance requirements.
For example:
- Some providers may limit new accounts to smaller daily or monthly transfers.
- Verified users may qualify for higher transfer limits.
- Cash-based transfers sometimes have different limits than bank transfers.
- Certain services may request additional identification for larger transactions.
Before sending money, it is recommended to review the provider’s limits, accepted identification documents, and delivery methods available in Guatemala.
What determines the real cost of sending money to Guatemala?
The real cost of sending money to Guatemala may depend on three main factors:
Transfer fee
The transfer fee is the amount charged to process the remittance.
Some services use a flat fee structure, while others may adjust the pricing depending on the amount sent, payment method, or delivery speed. Some service providers may also offer promotional pricing for first-time transfers.
Although low fees can help reduce costs, they may not always represent the lowest total transfer cost once exchange rates and other charges are considered.
Exchange rate spread (USD to GTQ)
Another important factor is the exchange rate used to convert U.S. dollars into Guatemalan quetzales.
Some providers may apply a margin (also known as a spread) on top of the market exchange rate. Even small differences in the USD to GTQ conversion rate can affect how many quetzales your family receives, especially on larger transfers.
Comparing the final amount received in GTQ may provide a more accurate picture of the total transfer cost.
Recipient charges or withdrawal costs
In some cases, the recipient may face additional costs when receiving the money. These depend on the provider and delivery method.
There could be charges related to ATM withdrawals, cash pickup locations, bank processing, or currency conversion. These costs may vary depending on the institution or pickup network used in Guatemala.
What is the best way to send money to Guatemala from the United States?
The best way depends on your context and priorities. Today, there are many ways to send money to Guatemala from the United States, with different service providers offering features such as faster delivery times, multiple delivery methods, or lower overall transfer costs depending on the type of transaction.
Traditional banks
Some people choose to send money through traditional bank wire transfers. This option is available for people who already use a U.S. bank account.
However, international bank transfers can sometimes involve higher fees, slower processing times, special considerations such as banks in the U.S. generally being closed for federal holidays or additional requirements such as SWIFT codes and recipient banking information.
Cash transfer agencies
Cash pickup services continue to play an important role for many families in Guatemala, especially for recipients who primarily manage their finances in cash or who may not have easy access to traditional banking services.
Companies such as Western Union, MoneyGram, and Ria Money Transfer can offer extensive pickup networks across Guatemala through local banks, convenience stores, supermarkets, and remittance partners.
This option can be convenient for recipients who prefer immediate access to cash, although some traditional cash transfer services may involve higher fees or exchange rates that are less favorable compared to other options.
Digital apps and platforms
Another option is using apps and digital platforms specialized in international transfers.
Services such as Común, Félix Pago, Ria Money Transfer, and MoneyGram offer options to send money directly from your phone, either through an app or even WhatsApp. These services often include multiple delivery options available in Guatemala.
While some of these service providers focus mainly on remittances, others may also include features such as debit cards, mobile banking access, or account management tools. For example, Común (https://www.comun.app) offers a debit card that accepts more than 100 Latin American IDs for account verification, it also offers the option to send money on the app or using WhatsApp, and offers cash pickup options in Guatemala.
Comparing services for sending money to Guatemala
There are services available for sending money to Guatemala, but the fees, exchange rates, transfer speeds, and delivery methods can vary depending on the provider and transfer type. This table was created to provide a visual aid for comparing 5 popular remittance service providers in the United States to Guatemala.
| Service | Payment Options | Fee | Delivery Options | Exchange Rate | Speed |
|---|---|---|---|---|---|
| Común | Bank account, debit card, cash | Starting at 2.99 USD | Bank account or cash pickup | Competitive | Minutes to hours |
| Western Union | Bank account, card, cash | Varies depending on amount and method | Cash pickup, bank deposit, wallet | Varies with applicable spread | Minutes to days |
| Ria Money Transfer | Bank account, debit card, credit card, cash | Starting at $0.99; can be free for bank transfers up to $15,000 | Cash pickup, bank deposit, wallet | Varies with applicable spread | Minutes to days |
| MoneyGram | Bank account, debit card, credit card, cash | Varies depending on amount and delivery method | Cash pickup, bank deposit, wallet | Varies with applicable spread | Minutes to hours |
| Félix Pago | WhatsApp, debit card, cash | $2.99 USD for bank account transfers and $4.98 USD for cash pickup transfers | Bank account and cash pickup | Competitive | Instant to days |
The total amount received in GTQ is subject to change throughout the day due to exchange rate fluctuations, provider fees, and delivery methods.
To compare real-time transfer costs and exchange rates, you can use tools such as Común Compara (https://www.comun.app/compara) designed to help you have more clarity on remittance costs. If applicable, you may see a "Primer envío" toggle that reflects promotional pricing for eligible first transfers.
How does the recipient receive money in Guatemala?
It depends on the provider selected, as recipients in Guatemala can receive money through different delivery methods.
Bank deposit
Some service providers offer direct deposits into Guatemalan bank accounts in quetzales. The delivery speed can vary depending on the receiving bank and transfer verification process.
Cash pickup
Depending on the provider and the recipient's location, they can collect money from local banks, remittance agencies, supermarkets, or retail stores.
To receive the money, recipients often require a valid identification document and the transfer reference number.
Delivery times
Transfer times can vary depending on the provider, payment method, verification requirements, holidays, and delivery option selected.
Some digital transfers can arrive within minutes, while bank transfers or certain cash pickup options could take longer.
How can I send money to Guatemala with Común?
With Común, people can send money to Guatemala directly from the mobile app. To send money, you can follow the steps:
- Open your Común mobile app.
- Select "Send a Remittance."
- Choose or register the recipient.
- Enter the recipient's information, including bank details if needed.
- After registering the recipient, enter the amount you want to send.
- Review the exchange rate, transfer fee, and delivery method.
- Confirm the transaction.
- You can check the transfer status in your Común mobile app by clicking on the transaction.
Transfer fees start at 2.99 USD per transaction, up to applicable limits.
Why choose Común to send money to Guatemala?
Común’s vision is to become the leading financial platform for immigrants in the U.S. Therefore, it can include elements that are helpful for people sending money to Guatemala from the United States.
Some of the services include:
- Acceptance of more than 100 Latin American IDs for verification.
- Spanish-language app experience.
- Ability to send money directly from the app or WhatsApp.
- Multiple delivery methods available in Guatemala.
As with any financial service, transfer costs, delivery speeds, and availability may vary depending on the transaction details. You can learn more about Común on our website (https://www.comun.app/about-us) or in the app (https://www.comun.app/).
FAQ
How much does it cost to send money to Guatemala?
The total cost may depend on the provider, transfer fee, exchange rate, delivery method, and whether the recipient faces additional charges.
How long does it take for money to arrive in Guatemala?
Transfer times can vary depending on the provider and delivery method selected. Some digital transfers may arrive within minutes, while others could take several business days.
What is the best app to send money to Guatemala?
The best app may depend on what matters most to you, whether that's lower fees, exchange rates, delivery speed, or cash pickup availability.
Do I need an SSN to send money to Guatemala?
Some providers may require an SSN, while others may also accept an ITIN or alternative identification documents depending on their verification policies. It is important to check each service provider’s verification requirements.
How much money can you send to Guatemala from the United States?
Transfer limits may vary depending on the provider, payment method, and verification level.
Where can my family receive money in Guatemala?
Depending on the provider, recipients may receive money through bank deposits, cash pickup locations, mobile wallets, or other delivery methods available in Guatemala.
Living in the United States
The cheapest states to rent in the United States in 2026
8 min de lectura
The cheapest states to rent in the United States in 2026
Based on recent rental market data, West Virginia continues to rank among the lowest-cost states for renters, with a 2025 Fair Market Rent of approximately $801 per month for a one-bedroom apartment. Arkansas and Mississippi also remain among the most affordable states to rent, with estimated one-bedroom Fair Market Rents of roughly $811 and $910 per month respectively. Other states frequently appearing among the cheapest states to rent include Oklahoma, Kansas, Iowa, Alabama, Indiana, Wyoming, and Ohio.
The national average asking rent for a one-bedroom apartment in the US sits at around $1,576 per month — a figure that can consume a significant share of the household's income. However, the average masks the variations across the country.
Why do rent prices vary so much by state?
Rent prices are not a single national market, they are thousands of local ones. The gap between the cheapest and most expensive states may be more than $1,600/month for a comparable unit. Several structural factors explain why a one-bedroom in Iowa can cost a fraction of what it does in California:
- Housing supply and construction pace. States with fewer building restrictions and lower land costs tend to have more available units, which keeps prices more accessible.
- Local economy and wages. Higher-income cities attract more renters competing for the same units, pushing prices up.
- Urban vs. rural mix. A state dominated by mid-sized cities will register lower averages than one anchored by major coastal cities.
- Regulatory environment. Zoning laws, permitting processes, and landlord-tenant regulations influence how fast housing supply can respond to demand.
- Climate and geography. Desirable coastal cities or warmer climates attract more people, which drives up rents over time.
The 10 cheapest states to rent in the U.S. in 2026
1. West Virginia — 1BR FMR: ~$801/month
West Virginia holds the lowest 1-bedroom Fair Market Rent of any state in the US at $801/month. The median rent statewide sits around $883/month across all unit types, with West Virginia apartments running roughly 41.6% less expensive than the national 2BR average. In 2024, 64.8% of leased homes in West Virginia rented for less than $1,000/month.
2. Arkansas — 1BR FMR: ~$811/month
Arkansas is consistently cited among the states with the lowest rent in the US. The 2025 HUD Fair Market Rent for a 1-bedroom is $811/month, and the state's apartments run roughly 41.4% less expensive than the national 2BR average. In 2024, 51.9% of leased homes in Arkansas rented for less than $1,000/month.
3. Mississippi — 1BR FMR: ~$910/month
The 2025 HUD Fair Market Rent for a 1-bedroom is $910/month, and some market-rate data places average 1BR asking rents lower, around $785–$825/month. In Jackson, the state capital, a 1-bedroom apartment may average around $785/month. The state has a notable Latino community in agricultural and food-processing hubs.
4. Oklahoma — 1BR avg: ~$850–$875/month
Oklahoma may offer some of the most affordable urban rent in the country. Oklahoma City's average 1BR rent sits around $875/month, ranking among the cheapest large cities to rent in the US. The state's housing index sits at approximately 67.9, meaning homes and rentals cost about 32% less than they do nationally.
5. Kansas — 1BR FMR: ~$885/month
Kansas delivers consistent affordability, with a 2025 HUD Fair Market Rent for a 1-bedroom at $885/month, roughly 35.6% below the national 2BR average. The median home price in Wichita, Kansas' largest city, was approximately $198,000 in Q1 2026.
6. Iowa — 1BR FMR: ~$839/month
The 2025 HUD Fair Market Rent for a 1-bedroom is $839/month, with Iowa apartments running 38.3% less expensive than the national 2BR average. Iowa households spend just 17% of their income on housing, the lowest share of any state in the country.
7. Alabama — 1BR FMR: ~$905/month
Alabama's apartments run roughly 36.4% less expensive than the national 2BR average. The 2025 HUD Fair Market Rent for a 1-bedroom is $905/month. The median home price of approximately $179,400 is among the lowest in the country. In 2024, 42.8% of leased homes in Alabama rented for less than $1,000/month.
8. Indiana — 1BR avg: ~$900–$950/month
Indiana sits comfortably in the affordable tier, with average 1BR rents well below $1,000/month in most markets. Indianapolis offers sub-$1,000 rents in a metro with a job market ranging from logistics, healthcare, technology, to life sciences. Indianapolis' growing Latino community has made the city an increasingly relevant destination for immigrant families relocating to the Midwest.
9. Wyoming — 1BR FMR: ~$836/month
Wyoming's sparse population keeps rental demand low and rents affordable. The 2025 HUD Fair Market Rent for a 1-bedroom is $836/month. In 2024, 50.2% of leased homes in Wyoming rented for less than $1,000/month. Wyoming has no state income tax.
10. Ohio — 1BR avg: ~$950–$1,000/month
Average 1BR rents hover near $950–$1,000/month while the state's cost of living runs roughly 8–9% below the national average. Ohio's combination of major metro accessibility and rental affordability makes it a compelling option.
Comparison table of the cheapest states to rent in the US (2026)
| State | 1BR FMR / Avg. Rent | vs. National 1BR FMR (~$1,393) | Cost of Living Index |
|---|---|---|---|
| West Virginia | $801 (FMR) | ~42% less | 83.2–86.6 |
| Arkansas | $811 (FMR) | ~42% less | 87.6 |
| Mississippi | $910 (FMR) | ~35% less | 83.3 |
| Oklahoma | ~$850–$875 (market) | ~37–39% less | 85.5–88.8 |
| Kansas | $885 (FMR) | ~36% less | 89.0 |
| Iowa | $839 (FMR) | ~40% less | 90.4 |
| Wyoming | $836 (FMR) | ~40% less | 92.3 |
| Alabama | $905 (FMR) | ~35% less | 89.3 |
| Indiana | ~$900–$950 (market) | ~32–35% less | 90.1 |
| Ohio | ~$950–$1,000 (market) | ~28–32% less | 91.2 |
1BR FMR = HUD Fair Market Rent FY2025. National 1BR FMR baseline: $1,393. Market-rate averages from PropertyCEO. Cost of Living Index from costoflivingbystate.com (C2ER Q1 2026). All figures are estimates and may vary by city, unit type, and data provider.
How to choose the right State for your budget and lifestyle?
Rent-to-income ratio, not just the rent number:
Some cheap-rent states also have lower wages. Mississippi, for example, ranks near the bottom for rent in dollars, but can rank near the top in terms of what percentage rent makes up of earned income.
Job availability in your field:
Employment opportunities can vary significantly from state to state. States such as Ohio, Indiana, and Alabama tend to have more diversified economies. For remote workers, lower-cost states may provide greater financial flexibility.
Community and support networks:
For immigrants and families relocating to a new area, access to established communities can make a major difference. Cities with growing Latino populations, bilingual services, and community organizations may help newcomers feel more connected.
Climate and weather risk:
States in the Midwest can experience colder winters and higher heating costs, while Southern states may bring higher air conditioning expenses. Some regions may also face increased risks related to hurricanes, tornadoes, or flooding.
Compare the total cost of living:
Rent is only one part of a household budget. Groceries, utilities, transportation, healthcare, childcare, and taxes can also vary significantly by state.
Manage your finances in any state with Común
Moving to a more affordable state may help reduce financial pressure, but managing your money efficiently remains important no matter where you live. Visit Común's website or download the app to learn more.
FAQ
What is the cheapest state to rent in the US in 2026?
Based on HUD Fair Market Rent data, West Virginia has the lowest 1BR FMR of any state at $801/month and the lowest median rent overall at approximately $883/month.
Which states have the lowest average rent for an apartment?
The states with the lowest average apartment rent in 2026 are West Virginia, Arkansas, Iowa, Wyoming, Mississippi, Oklahoma, Kansas, Alabama, and Indiana. Average 1-bedroom rents in these states range from approximately $785 to $950/month.
How much should I budget for rent in the US?
The commonly cited guideline is to spend no more than 30% of gross monthly income on rent. In the cheapest states, where 1BR rents may run $800–$900/month, the same guideline requires roughly $2,667–$3,000/month in gross income.
Living in the United States
Cheapest cities to live in the United States in 2026
8 min de lectura
Cheapest Cities to Live in the United States (2026)
Living in large metropolitan areas such as New York City, Los Angeles, or Miami can be expensive, especially when it comes to housing, transportation, and everyday expenses. For many people, including recent immigrants, young professionals, and families trying to build financial stability, the affordability of a place may play an important role when deciding where to live in the United States.
There are cities across the country where the overall cost of living can be lower while still offering access to jobs, public services, universities, and established communities. Cities such as Cleveland, Detroit, Toledo, Wichita, and Memphis are often recognized among the more affordable cities to live in the United States due to their relatively lower housing costs and cost-of-living indexes.
This guide explores some of the more affordable cities to live in the U.S., the factors that influence affordability, and considerations that may help when choosing a city that fits your budget, lifestyle, and long-term goals.
Factors that influence the cost of living in cities in the U.S.
Housing and rent
Housing is usually one of the largest expenses for households in the U.S. The national median home price ranges from approximately $408,800 to $437,000. In major metropolitan areas, average rents can exceed $2,000/month. In the most affordable cities, median home prices can be as low as $75,000–$150,000, and one-bedroom apartments often rent for $600–$900/month.
Utilities and groceries
Utility costs such as electricity, water, internet, and heating can vary depending on the region and climate. Grocery prices can also differ between cities depending on transportation costs, local agriculture, and overall demand.
Transportation and mobility
In some larger cities, public transportation may reduce the need for a car. In smaller or more spread-out cities, owning a vehicle may be more needed, which can add costs such as gas, insurance, parking, and maintenance.
Job Opportunities and Salaries
A lower cost of living may not always translate into greater affordability if local salaries are significantly lower. According to the U.S. Census Bureau, the national median household income was approximately $83,730 in 2024.
The 10 most affordable cities to live in the United States
1. Cleveland, OH
Cleveland consistently ranks among the most affordable large cities in the United States. Its overall cost of living runs approximately 7–17% below the national average, with housing costs particularly low. Median home prices range from roughly $105,000 to $150,000, a fraction of the national median. The city's economy is anchored in healthcare and advanced manufacturing, with the Cleveland Clinic and University Hospitals serving as two of the region's largest employers. Cleveland is also home to approximately 49,500 Hispanic residents, making it the second-largest Latino community of any city in Ohio, with established Puerto Rican, Mexican, and Central American communities.
2. Detroit, MI
Detroit stands out for its exceptionally low housing purchase prices. Houzeo reports a median sale price of $82,000, while Redfin records a higher median of $104,000 as of March 2026. Significant investment in downtown revitalization, automotive industry jobs, and a growing startup scene have improved its economic outlook.
3. Toledo, OH
Toledo is one of the lower-cost cities in the Midwest. Redfin puts Toledo's median sale price at $111,000 as of February 2026, noting that Toledo's median is 68% lower than the national average. Manufacturing, healthcare, and logistics remain important parts of the local economy, and the city has an established Latino community with access to Spanish-speaking services.
4. Wichita, KS
Wichita's cost of living is 12% lower than the national average, with housing 35% cheaper than the U.S. average. The median household income is $63,072. Redfin reports a median sale price of $235,000 in March 2026. The aerospace and manufacturing industries are major employers.
5. Memphis, TN
Memphis's overall cost of living is 11% lower than the national average. Redfin reports a median sale price of $170,000 in February 2026, noting Memphis's median is 51% lower than the national average. Average rents for a one-bedroom are typically in the $800–$950 range. Memphis is a logistics and distribution hub — FedEx is headquartered there.
6. Tulsa, OK
Tulsa is often viewed as one of the more affordable cities in the South-Central United States, with housing costs remaining below those in many larger U.S. metros. The city gained national attention through the Tulsa Remote program. Energy, healthcare, and finance continue to be important industries in the local economy.
7. Knoxville, TN
Knoxville's cost of living is 14% lower than the national average. The city combines lower overall costs with access to universities, healthcare systems, and outdoor recreation in the Appalachian region. Redfin reports a median sale price of $307,000 in March 2026.
8. Birmingham, AL
Birmingham is frequently recognized as one of the more affordable cities in the Southeast. Healthcare remains one of the city's largest industries, particularly because of the University of Alabama at Birmingham and its medical network. Housing prices and rental costs may remain lower than those found in many larger Southern metropolitan areas.
9. Indianapolis, IN
Indianapolis is often categorized as a lower-cost mid-sized city. The city has continued expanding in sectors such as logistics, healthcare, and technology, while maintaining housing prices that are often lower than those in coastal metropolitan areas. Indianapolis also has a growing Latino community and multiple immigrant support organizations.
10. Brownsville, TX
Brownsville is often highlighted for its affordability and strong connection to Latin American culture. Located within the U.S.-Mexico border, the city has one of the largest Spanish-speaking populations in the country (94% Hispanic), which may make everyday life more accessible for recent immigrants and bilingual families.
Comparison Table: Cost of Living by City (2026)
| State | 1BR FMR / Avg. Rent | vs. National 1BR FMR (~$1,393) | Cost of Living Index |
|---|---|---|---|
| West Virginia | $801 (FMR) | ~42% less | 83.2–86.6 |
| Arkansas | $811 (FMR) | ~42% less | 87.6 |
| Mississippi | $910 (FMR) | ~35% less | 83.3 |
| Oklahoma | ~$850–$875 (market) | ~37–39% less | 85.5–88.8 |
| Kansas | $885 (FMR) | ~36% less | 89.0 |
| Iowa | $839 (FMR) | ~40% less | 90.4 |
| Wyoming | $836 (FMR) | ~40% less | 92.3 |
| Alabama | $905 (FMR) | ~35% less | 89.3 |
| Indiana | ~$900–$950 (market) | ~32–35% less | 90.1 |
| Ohio | ~$950–$1,000 (market) | ~28–32% less | 91.2 |
1BR FMR = HUD Fair Market Rent FY2025. National 1BR FMR baseline: $1,393. Market-rate averages from PropertyCEO. Cost of Living Index from costoflivingbystate.com (C2ER Q1 2026). All figures are estimates and may vary by city, unit type, and data provider.
How to choose the ideal city?
An affordable city may look attractive on paper, but the best option can still vary depending on your personal situation, work opportunities, and long-term goals.
Family budget:
For most households, housing remains the largest monthly expense. Neighborhood-level costs may vary significantly within the same city.
Community and support networks:
For many immigrants, having access to a strong community network can make the transition to a new city easier. Cities with established Latino communities may offer more Spanish-speaking services, cultural organizations, churches, restaurants, and local businesses.
Job availability:
A lower cost of living may not always translate into greater financial stability if local salaries and job opportunities are limited. For remote workers, choosing a lower-cost city may also provide more flexibility.
Access to services and education:
Before moving, it may help to consider commute times, fuel costs, access to public transit, and proximity to schools, grocery stores, and healthcare services.
Manage your finances in the US with Común
Choosing an affordable city is only one part of building a stable life in the United States. Común offers a debit account that can be opened with more than 100 valid Latin American IDs. The app and services are available in Spanish and users can conveniently send money from their phone to 10+ countries in Latin America. Visit comun.app to learn more.
FAQs
What is the cheapest city to live in the US?
Based on 2026 cost-of-living data, Cleveland, OH and Detroit, MI rank among the cheapest large cities in the United States, with cost-of-living indexes well below the national average.
Where can you find the most affordable housing in the US?
The most affordable housing markets in 2026 tend to be in the Midwest and South, particularly in Ohio, Michigan, Tennessee, Alabama, and Oklahoma.
Which cities offer a balance between employment and affordability?
Indianapolis, IN and Knoxville, TN are frequently cited for combining affordability with strong job markets.
How do I calculate the cost of living before moving to a new city?
Start with the three largest expenses: housing, transportation, and food. Use tools like the C2ER Cost of Living Index or Numbeo's city comparison tool to compare cities side by side.
Which cities have the largest Latino communities and affordable cost of living?
Brownsville, TX has a 94% Hispanic population and a cost of living approximately 12–16% below the national average. Toledo, OH, Cleveland, and Indianapolis also have established Latino communities and Spanish-language services.

International Money Transfers
How can I receive money from the United States? 3 reliable and fast methods
8 min de lectura
Knowing how to receive money from the United States is essential, as remittances have become a key part of the economy for thousands of immigrant households. According to estimates, by 2030, migrant workers will send a total of $5 billion to their country of origin.
The growing need to send and receive money from abroad has encouraged the creation of new methods specifically designed for countries like Latin America. Below, we present the fastest, easiest, and safest options for receiving your money without complications.
You will learn everything about receiving money from the United States and Latin America: key aspects such as costs and security, requirements to open an account, and different applications for sending money from the United States. By the end of this article, you will know exactly which option is best suited to your needs.
5 Key Aspects to Consider When Receiving Money from the United States
Thanks to technological advances and financial openness, sending and receiving money through digital means is increasingly simple and accessible.
However, immigrant families still face various obstacles, such as high transfer fees, bank-imposed restrictions, and weak security measures.
Undoubtedly, this is not a decision to be taken lightly. Before accepting the terms and conditions of any provider, pay attention to the following key aspects:
Transfer Speed
Access to cash quickly is a fundamental need for users receiving money from the United States. The reception time varies depending on the sender and other important factors:
- Type of bank: If the transaction is carried out through a traditional bank, it may take up to 5 business days. It is therefore advisable to opt for a company specialized in international transfers.
- Holidays or non-business days: These can also affect the speed of money reception.
- Receiving bank conditions: Each financial institution sets its own rules for receiving remittances, so it is advisable to consult your bank's specific conditions.
Cost/Fees
A fundamental aspect to consider when receiving money from the United States is the fees, which can exceed 10% of the total amount and significantly reduce household support.
Consider an option that offers affordable costs and a favorable exchange rate.
Security and Reliability
The theft of personal data, commonly known as phishing, is the primary risk in international money transfers. To avoid becoming a victim of such fraud, make sure to use a reliable service through an official website or mobile app. Additionally, do not share passwords or sensitive information with third parties.
Ease of Use
According to the study Remittances to Latin America and the Caribbean 2024, 60% of migrant workers in the United States send money to their mothers. It is important to choose a provider that understands your needs and offers reliable, secure, and easy-to-use platforms.
Receiving Options
If for any reason you cannot receive money through bank transfers, look for an option that offers cash pickup locations near you, such as Oxxo or Walmart.
What Do You Need to Receive Money from the United States?
Regardless of the bank you choose the requirements for receiving money can be summarized as your basic personal information:
- Full name of the beneficiary
- Account number
- Name and address of the receiving bank
- SWIFT/BIC code of the receiving bank
- Address of the beneficiary
- Name of the intermediary bank
The requested data may vary depending on the receiving country, so you may be asked for more or less information. Remember, no reputable institution will ask for passwords or access information to complete transfers or send money.
3 Methods to Receive Money from the United States Without Complications
If you need to send and receive money from the United States to Mexico, you can choose from the following options:
1. Receiving Money into Your Account
This is a simple way to receive money from the United States, as it allows you to do so from the comfort of your home via a mobile application.
In the case of Mexico, most traditional banks tend to receive transfers from the United States under their own terms and conditions. This means that fees and exchange rates vary by financial institution.
For Banorte and BBVA, the cost for international transfers is $30 plus VAT, regardless of the amount sent.
Receiving money through traditional financial institutions can be expensive; fortunately, there are more affordable alternatives.
2. Receiving Money Through Comun
Comun allows you to send money from the United States to Latin America with no charge on your first transfer and accessible fees thereafter. It is the preferred option among the immigrant community, offering shared language, interests, and goals: bringing families closer together through secure and affordable financial solutions.
Open your account with Comun and start sending money from the United States to your home without complications. Your family can receive it in local bank accounts or collect it physically at partner locations.
3. Receiving Money on Other Platforms
Wise
Wise is another platform that offers international money transfers. It is geared toward independent workers around the world who earn income from the United States.
Although it is a common alternative for receiving money digitally from abroad, it does not offer physical pickup options, which may be a drawback for migrant families.
Western Union
Western Union is one of the most popular options among migrant workers in the United States, as it allows for cash transfers without the need for a bank account, including to rural or hard-to-reach areas.
It is a suitable option in certain circumstances, but be aware that Western Union’s commission fees are typically high, and it uses a lower exchange rate than the market.
The cost of sending money depends on several factors, such as the method used and the destination country. However, the fee can reach up to 6%, not including the exchange rate difference.
MoneyGram
Finally, MoneyGram is an international money transfer service operating in over 200 countries, including Mexico.
Your Family Gets More for Less: Send Money with Comun from the United States.
As you can see, sending and receiving money from the United States does not have to be complicated. Today, there are financial services that aim to bridge the gaps that hinder communication between businesses and individuals.
Comun is an accessible option for all, offering the best benefits for immigrant families:
- Access to a debit card and mobile app
- Account opening with official ID from your country
- Competitive fees for International money transfers, starting at $2.99 transfer fee
- No opening fees or monthly charges
Compare and choose the option that best fits your needs. Remember that you have an ally in Comun to receive money from the United States without complications.
Frequently Asked Questions
How long does it take for money to arrive from the U.S. to Mexico?
With Comun, your money arrives in minutes via bank transfers. Cash pickups at partner locations take as little as 1 hour.
What are the typical fees for receiving money?
Fees usually depend on the amount and destination country. Comun offers a transfer fee starting at $2.99, regardless of the amount sent up to the applicable limits.
Do I need a checking account to receive money?
Comun provides a checking account that includes a debit card and mobile application. However, it is not required, since you can receive money at physical locations.
Is it safe to receive money through digital platforms?
Absolutely. Comun is backed by major financial institutions. Your Comun account funds are insured by the FDIC up to $250,000 per ownership category through Community Federal Savings Bank (CFSB), member of the FDIC, in the event of CFSB’s failure.

Instant payments
How do I send money through Xoom? Your complete 7-step guide
8 min de lectura
Today, sending money to other countries has become a basic need for millions of immigrants living in the United States.
According to the IDFR ( International Day of Family Remittances) campaign in 2025, over the last decade, immigrants sent around 5 trillion dollars in remittances to their countries of origin, which are essential for food, housing, health, and other basic expenses.
To meet this need, there are applications such as Xoom, a PayPal service for transferring money using various payment methods and in a secure manner.
In this guide, we will review how to send money with Xoom step by step, its main features, and some alternatives to connect with your family outside the U.S.
What is Xoom, and is it safe to send money with this service?
Xoom is a digital transfer network owned by PayPal that operates entirely online and offers different sending options to facilitate transactions.
It has become one of the most popular options for making international digital money transfers, due to the backing provided by PayPal, which gives users a sense of security.
In addition to PayPal’s backing, Xoom has high security standards for transferring money, such as SSL encryption and the VeriSign seal.
Additionally, its services are available to send money from the United States to more than 70 countries, including Mexico, Guatemala, Honduras, Peru, among others.
7 detailed steps to send money with Xoom
To send money through Xoom, just follow the steps below.
Access Xoom (web or mobile application) and sign in or register
You can choose to log in via the website www.xoom.com or the mobile application. Once there, sign in or open an account with your email address. You can also use your PayPal account to access.
Select the destination country and the amount to send
Choose the country to which you want to send the transfer. Then you will see the sending options available for the selected destination.
Choose the sending method
Xoom offers the following payment methods:
- Bank deposit
- Cash pickup at physical locations, such as Oxxo or Elektra
- Mobile top-up
- Bill payment
- Cash delivery
Provide the recipient’s details
The information you must enter is:
- Full name, as it appears on their official ID
- Address
- Phone number
- Bank account (if applicable, depending on the sending method)
Select your payment method
Next, enter the amount you want to send and select the payment method, among which are:
- Linked bank account
- Debit card or credit card
- Available balance in your PayPal account
Review and confirm the transaction
Before confirming the transfer, Xoom will display the details so you can verify they are correct, along with the amount corresponding to fees, as well as the exchange rate used for the currency conversion.
Track your transfer with the tracking number
Obtain a tracking number and check the status of your transfer directly in Xoom’s application or website.
Key aspects to consider when using Xoom
Although Xoom is a popular alternative for making fast and secure transfers, it is important to consider several aspects before choosing this option.
Sending fees
Xoom’s sending fees are not fixed; they depend on the destination country, the amount to send, and the payment method.
Generally, the most expensive method is with a credit card and the least expensive is through an account.
| Platform | Fee | Exchange rate | Delivery time | Delivery options |
|---|---|---|---|---|
| Xoom | From 2.99 USD, depending on the sending type | Less favorable | Minutes to hours | Bank deposit, cash pickup, home delivery |
| Común | Fee starting at 2.99 USD, up to the applicable limits | Competitive (Clarification: Results may vary depending on destination country and sending method) | Minutes | Cash pickup, bank deposit |
Exchange rate
The exchange rate can be another drawback because, in addition to being calculated directly on Xoom’s platform, it varies depending on the selected transfer method.
Sending limits
Xoom imposes sending limits that depend on each account’s verification level. For unverified users residing in the U.S., the daily limit is $2,999 USD. By contrast, verified users can send up to $10,000 or $50,000 USD per day, depending on their verification level.
Receiving options
Xoom has different receiving options, but they may vary depending on the destination country.
In general, it is possible to send money for cash pickup at different payout locations, by bank deposit, top-up, or bill payment.
Security and reliability
Xoom is backed by PayPal, in addition to SSL/TLS encryption to protect your financial information and anti-fraud monitoring to ensure your money reaches its destination.
Delivery times
Generally, money transfers via debit card and cash are reflected within minutes. However, other sending methods, such as bank deposit, can take from 1 business day.
The total time will appear before you confirm your transaction in Xoom’s application or on its website.
Accessibility
Xoom is also available in Spanish and, overall, is easy for migrants in the United States to use.
Modern alternatives to sending money with Xoom: Why is Común a smart choice?
Sending money outside the U.S. is essential, as is having efficient international transfer services such as Xoom. However, there are also more innovative options that offer you greater advantages and lower costs so that your family and friends receive much more.
Común is an innovative and comprehensive financial service that meets the financial needs of users living in the United States, especially immigrants. Unlike Xoom, Común has a specialized focus and transparent fees.
With Común:
- Open your account with an official ID from your country; more than 100 identifications are accepted.
- After your first free transfer, pay a fee starting at $2.99 USD per transfer, up to the applicable limits.
- Access customer service in Spanish and English, available 24/7.
- Get a Visa debit card to make purchases at physical merchants.
- Manage your finances from Común’s mobile platform, where you can sync your external bank account and manage your finances from the Común platform.
Still unsure which option is most convenient for sending money? Discover Común and get to know the easy and safe side of finance.
Frequently asked questions
If you want to learn more, see our FAQ section
How do I send money from Mexico to the United States using Xoom?
It is not possible to send money from Mexico through Xoom, since it only allows transfers from the United States, Canada, and other European countries.
How long does it take for money to arrive via Xoom?
Depending on the sending method, it ranges from minutes to up to 3 business days.
Is it safe to use Común to send money to Latin America?
Yes, Común has the necessary security measures in place to keep your money and personal data safe.
Can I use Común even if I don’t have a PayPal account?
Yes, Común is an independent platform from PayPal, and you can open an account with official ID from your country.
Can I make cash deposits if I don’t have a bank account in the U.S.?
Yes, Común allows you to deposit cash at numerous locations near you.







Thousands of immigrants are already achieving more with their money. You can too.
Comun is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank; Member FDIC. The Comun Visa® Debit Card is issued by Community Federal Savings Bank, pursuant to a license from Visa U.S.A Inc. and may be used everywhere Visa Cards are accepted.
Comun is a fintech company and not a bank or licensed money transmitter.
* Results may vary. For a complete list of eligible IDs and application requirements, follow this link.
^ No minimums, no maintenance fees. ATM or transfer fees may apply. See app for fee details.
‡ Direct deposit funds are typically available when we receive the payment file, up to two days before the scheduled payment date. This early availability is not guaranteed.
** A service provided by Service UniTeller, Inc. Service UniTeller, Inc. is licensed in all states that require a license. Remittance fees start at $2.99 but may vary. Please check the app for more details. Comun Inc. may earn revenue from the conversion of foreign currencies.
† Funds in your account are FDIC insured up to $250,000 by ownership category through Community Federal Savings Bank (CFSB), Member FDIC, in the event CFSB fails.


