
Financial Education
Practical guide: what proof of income is and how it works in the U.S.
What is proof of income and how does it work in the United States? Types of accepted documents for renting, loans, and credit applications.
8 min read

20 Nov 2025
As an immigrant in the United States, you have likely been asked for proof of income to complete a procedure such as obtaining a loan, renting an apartment, or verifying financial solvency and ability to pay.
Such proof is a document that verifies the amount of your income as well as its source.
This time, we explain what proof of income is in the USA, what it is for, how to make an income letter if you are paid in cash, and everything you need to know to handle your procedures in the United States without complications.
What is proof of income?
Broadly speaking, proof of income is an official or informal verification of how much money a person earns and the sources from which that income comes.
This document is commonly used for both salaried employees and independent or freelance workers.
These are the most common types of documents used to verify income:
Pay stub:
This is an official document that serves as a payment receipt and is provided by the employer along with wages for the relevant pay period. It includes both parties’ details, base pay, hours worked, overtime (if applicable), and deductions for taxes.
Tax return:
The tax return is a document a person files annually with the Internal Revenue Service (IRS). It must include income earned, taxes withheld, deductions or credits, and the total tax due or refund.
Bank statements:
This is a report issued by a bank or financial institution detailing a customer’s transactions and balances in their bank account over a given period. It serves as an official document to corroborate a person’s solvency as well as other personal data.
What is proof of income used for in the U.S.?
Having proof of income is very useful for various procedures in the United States, as well as to access helpful benefits and simplify your life—for example, signing a lease, obtaining a loan, and completing relevant immigration procedures. Proof of income is essential in these processes because it gives the requesting party assurance.
Housing rental:
Landlords commonly request proof of income to sign a lease, as it helps ensure tenants can cover the monthly rent without delays.
Loan or certain credit card applications:
Banks and other financial institutions usually verify applicants’ income before approving credit, since this reduces the risk of nonpayment or delinquency.
Immigration or social security procedures:
Immigration procedures—such as obtaining permanent residence—and other social security benefits also require proof of income. This is a measure implemented by the U.S. government to ensure applicants will not become a public charge.
What can I use as proof of income?
Whether you have formal employment or are self-employed, there are several documents you can use as proof of income.
For employees with formal jobs
If you have a formal job, obtaining proof of income will be easier. As noted, you can present a pay stub, bank statement, or an employer letter.
For independent workers
If you are self-employed, verifying income may be a bit more challenging than for formal employees. In this case, you can present your annual tax return and bank statements.
If none of these options are available, you can draft an income letter, which should include the following information.
- Full name.
- Address.
- Description of independent economic activity.
- Average monthly income.
- Signed statement of truth.
- If possible, attach a bank statement.
How can I verify my income if I’m paid in cash?
If you receive your pay in cash, you can generate formal proof of income.
The first option is to create a signed income letter. You can also keep an income log in a spreadsheet. To make the process easier, it is advisable to seek support from an accountant.
How can you make an income-verification letter?
Fortunately, drafting an income-verification letter is not complicated, since it can be adapted to your work situation—even if you are paid in cash.
It is also a simple path for immigrants because it lets them use day-to-day documents.
Follow these steps to draft your income letter.
Step 1: Gather your documents
Any document that can help verify your income, even if it is not strictly a pay stub—such as a bank statement, fee receipts, invoices, etc.
Step 2: If you are self-employed, draft a self-employment income letter with basic data
Don’t forget to include your average income and signature.
Step 3: Verify that it includes your personal data and the income period you are declaring
It is very important to include your full name, address, and the dates that the declared income covers.
Step 4: If necessary, consult an accountant to make it more formal
An accountant will help you formalize your letter and gain better control of your personal finances and tax obligations.
Sample income letter
I, (full name), residing at (address), declare under penalty of perjury that I work as an independent contractor in the field of (description), with an average monthly income of (amount).
Copy this text and create your letter easily.
Use Común account statements as your proof of income
As you can see, proof of income is a formal document to verify a person’s income level as well as their ability to pay and financial solvency. You can use several documents for this purpose, such as a pay stub, annual tax return, and bank statement from traditional banks.
Común is the financial platform that can also help you record and organize your income, and generate account statements that can serve as valid proof in many situations.
It also offers a more accessible way to complete procedures through an easy-to-use mobile app available in Spanish, where you can quickly open an account using qualifying official identification from your country of origin.
Discover Común, a convenient financial option for those seeking simple and accessible solutions.
Frequently Asked Questions (FAQ)
If you still have questions, consult our FAQs.
What if I don’t have formal proof of income in the U.S.?
You can draft an income letter including your personal data, a description of your activity, average income, and signature.
Do proof-of-income documents from my country work in the U.S.?
Proof-of-income documents from your country can be accepted in the United States as long as they are official; in some cases, a certified translation may be required.
Which type of proof of income is most widely accepted?
The most widely accepted proof-of-income documents are pay stubs, tax returns, and bank statements.
About Común
Común aims to support the Latino community in the United States. It offers a debit account that can be opened with more than 100 valid Latin American IDs and an app available in Spanish.
Visit Común's website or download the app for free to learn more about the full offer and applicable terms.
Olivia Rhye
Community Partner

Checking account
What Is a Debit Card and How Does It Work?
8 min de lectura
A debit card is a bank card that lets you make purchases and withdraw money using funds available in your bank account. A debit card looks a lot like a credit card, but it works differently. When you use a debit card, the money is deducted directly from your bank account. That means you can only use the card if you have enough available funds — otherwise, the transaction won't go through.
Who Issues Debit Cards for Consumers?
Debit cards are issued by banks and are linked to individual checking accounts. You can get a debit card by opening a bank account at any bank or credit union that offers this service.
Many banking institutions also offer other digital services, like mobile and online banking, that let you manage your account over the internet or through a mobile device. In general, all banks offer services designed for people with different needs and income levels, giving nearly every adult access to banking.
Even though debit cards are easy to use, you should be careful with them. If you lose your card or it's stolen, report it to your bank immediately to prevent fraud or misuse. You should also regularly check your statements for fraudulent transactions or errors. With a bit of care, debit cards can be a useful tool for managing your money and making purchases online and in person.
How Can You Use Your Debit Card to Make Purchases or Withdraw Money From an ATM?
There are many ways to use a debit card to make purchases or withdraw money from an ATM.
To make a purchase, you can insert your card into the point-of-sale (POS) terminal and select "debit" as your payment method. Then enter your PIN and select the purchase amount.
To withdraw money from an ATM, insert your card into the machine's slot and select "checking/savings." Then enter your PIN and select the amount you want to withdraw.
You can also use your debit card to make payments online or by phone. To make an online payment, enter your card details on the merchant's website. To make a payment by phone, call the merchant's customer service number and provide your card details when asked.
What Protection Do Visa Debit Cards Have Against Unauthorized Charges?
If you have a Visa card, you're protected by Visa's Zero Liability policy. This policy guarantees you won't be held responsible for any unauthorized charges made with your card. That means if someone steals your card or uses it without your permission, you won't have to pay for those charges.
Visa's Zero Liability policy applies to all Visa cards, including debit and credit cards. It also applies to all transactions, including online and in-person transactions. This policy was put in place to help protect consumers against fraud and identity theft.
If you're a victim of fraud or identity theft, be sure to report it right away. You can call Visa's toll-free number 24/7 to report any incident. Visa will work with you to resolve the issue and help protect your money and identity.
What Are Virtual Debit Cards?
A virtual card is a card that isn't physical — it exists only in the digital world. Virtual cards are often used for online purchases, since they offer more security than using a regular debit card.
One of the benefits of virtual cards is that they can be used to limit how much money is spent on a purchase. For example, if you're buying something online and want to make sure you don't go over budget, you can use a virtual card instead of your regular credit or debit card. This can help you stay within budget and avoid racking up debt. Likewise, if your information is stolen during a transaction, the thief won't be able to access your other cards. This can help prevent fraud and keep your personal information safe.
If you're interested in getting a virtual card, there are a few things you should know. First, not all banks offer virtual cards, so you may need to open a new account at a bank that offers this service. Second, not all merchants accept virtual cards, so there may be some places where you can't use them. Finally, virtual cards sometimes come with associated fees, so be sure to read the terms and conditions before using one.
The Benefits of Común
When you get a checking account with Común, you'll get two debit cards: a physical one and a virtual one.
The physical card lets you make purchases at any business, and offers security thanks to its contactless capability and chip. This prevents your card details from being cloned or used for fraud.
The virtual card lets you make online purchases with more confidence, since contactless technology and chip protection aren't available on the internet — but if fraud does happen, the card can be canceled and replaced immediately. You can contact our support team anytime to report these cases.
Común debit cards work at more than 55,000 ATMs across the United States for deposits and withdrawals, and are protected by Visa's Zero Liability policy. That means any unauthorized charge won't be deducted from your checking account balance.
Financial Education
What is a certified check and how does it work?
8 min de lectura
What is a certified check and how does it work?
Certified checks are a common form of payment for thousands of immigrants living in the United States, especially for major purchases such as rent payments, buying a car, and legal settlements.
However, it is not always clear why the certification process matters and how it differs from other types of checks.
A certified check is a physical payment order that has been reviewed in advance by a financial institution to ensure there are sufficient funds in the issuer’s bank account. This is the fundamental reason it’s considered a safer form of payment than a personal check.
Below, we explain in detail what a certified check is, how it works, and why it’s important to understand the differences from other types of checks.
What is a certified check?
A certified check is a type of check with guaranteed funds, since the issuing bank has verified the money exists in the checking or personal account.
This makes it a safer form of payment than personal checks, because the bank sets aside the amount to be paid so it can be collected by the payee.
How is a certified check issued?
Issuing a certified check is a straightforward process you can complete directly at the financial institution of your choice.
- The customer requests the check
The account holder must go to a bank and request a certified check, specifying the payee and the amount.
- Customer identification
You must present an official ID to verify that you are the holder of the savings or checking account from which the funds will be drawn.
- The bank freezes the amount in the account
The bank then certifies there are sufficient funds to cover the check and freezes them to ensure the payee can cash it.
- Signature certification
You must sign the check before finishing the process so the bank can confirm the signature matches the one on file.
Affixing the certification stamp
Finally, once the bank has verified the funds and the signature, it places a certification stamp to document completion of the process.
Differences between a certified check and a cashier’s check
A cashier’s check is another way to make secure payments using a physical instrument. In this case, the bank branch issues the check after receiving the customer’s payment, so the funds come from the bank itself.
Below is a comparison between a cashier’s check and a certified check.
Cashier’s check
Certified check
Security
High; the bank verifies sufficient funds and places a hold for the payee.
Very high; the check is backed by the bank and does not depend on the issuer’s account.
Cost
At some banks they have no cost at others up to approximately $15.
Depends on the bank; typically $10–$20.
Issuance time
At the branch, after funds are verified.
Immediate.
When is a certified check typically required?
A certified check is commonly used for significant transactions or large amounts. This gives the recipient assurance that funds are available.
- Paying an apartment security deposit.
When finalizing a lease or purchasing an apartment, the landlord or agent may request payment via certified check to guarantee funds.
- Buying a used car.
Whether dealing directly with owners or dealerships, a certified check can be a suitable option because of the security it provides.
- Closing an important contract or legal settlement.
For example, to pay fees, settlements, or indemnities, certified checks provide security for both parties.
- For tuition or school fees.
Some educational institutions accept certified checks as a form of payment, especially for international or first-time payments.
Do you know what to do if a check is stolen or lost? We explain it here!
Practical tips for using certified checks safely
While certified checks are among the safest payment methods due to the bank’s verification process, there are still fraud attempts using forged documents.
With this in mind, keep these tips in mind to avoid becoming a victim of check fraud.
How to know if a check has funds and avoid scams
- Verify with the issuing bank.
Call the bank directly and provide the check number, account holder, and amount; ask them to confirm authenticity and that funds are guaranteed. Make sure you call the bank’s official number, not the one printed on the check.
- Be alert if you receive an overpayment check.
A common scam is sending a check for more than the amount due and asking for the difference in cash. Confirm the check’s validity with the bank before proceeding.
- Wait for the check to clear before handing over any goods.
Clearing can take 3–10 days. Make sure the funds have fully settled and are not just on hold.
- Avoid accepting checks from unknown parties.
Whenever possible, accept checks only from people you trust. If you must take a check, follow the security measures above.
Manage your money securely with Común
In this article we explained what a certified check is, how it’s issued, how it differs from cashier’s checks, and how to use this payment method safely.
While certified checks can be a good payment option, a checking account in the U.S. is a much more secure and practical way to manage money.
Meet Común, your financial ally in the United States!
Send, receive, and cash money within and outside the United States. Our platform lets you move your money easily, quickly, and securely. You need a qualifying official ID from your country of origin to get started.
Open your account with Común today and discover a financial platform tailored to you.
Frequently Asked Questions (FAQ)
Where can I get a certified check in the United States?
You can request certified checks at financial institutions such as banks, credit unions, and some digital banks.
How much does it cost to get a certified check at the bank?
The cost depends on the bank but is typically between $10 and $15.
What other types of checks exist in the U.S. besides certified checks?
Other types of checks in the United States include: Money order; Personal check; Cashier’s check.
Living in the United States
Step by step: how to file taxes for the first time as an immigrant in the U.S.
8 min de lectura
Basic requirements to file taxes for the first time in the United States
Although getting a job in the United States brings a series of benefits for the quality of life of immigrants and their families, it also means committing to fulfilling the obligations required by the country's laws.
Filing a tax return is one of the processes everyone who has earned income must complete. This is done by submitting a report of annual income to the Internal Revenue Service (IRS).
Filing a tax return is particularly important for everyone, as it opens the door to access financial services such as mortgage and personal loans, which in turn help build a financial record especially for immigrants.
Filing taxes is a stressful and often confusing process for most people, especially when it involves understanding the tax institutions of another country.
Below, we show you a step-by-step guide to help you fulfill your tax obligations in the U.S. and access the benefits that come with it, such as receiving refunds and building a financial record in the country.
What documents do you need to file your taxes?
The first thing you should know to file your tax return in the U.S. is the documentation required by the IRS to process your information.
Make sure you have the following documents:
- Tax Identification Number: if you do not have a Social Security Number (SSN), you must apply for an Individual Taxpayer Identification Number (ITIN).
- Qualifying official identification from your home country: valid passport, driver’s license, or any official document that verifies your identity.
- Proof of income: W-2 forms if you are a salaried employee and your employer withholds taxes, and Form 1099 if you are self-employed.
- Proof of address in the United States: utility bill or rental agreement.
- Financial information: checking account and routing number to receive your refund through direct deposit, if any.
Tax preparation: step by step for your first filing
It is important to stay alert during tax season and prepare in advance to meet the deadlines established by law.
Follow these steps to ease the stress of tax obligations.
Step 1. Gather all your documents
The first step is to gather all the necessary documents to file your annual tax return.
- Form W-2: this document details your salary and the amount of taxes already withheld; request it directly from your employer.
- Form 1099: used by people who work independently.
- Benefit or assistance letters: if you receive any government benefit or tax credit, the IRS sends letters to include in your tax return.
Step 2. Choose how to file
Once you have your documentation in order, you must decide how you will file your return: on your own or with professional help.
- Self-prepared tax filing: you can use various IRS-approved tax preparation software such as IRS Free File, TaxSlayer, or TurboTax, which simplify the process by automatically calculating your taxes.
- With the help of a tax preparer, if you have multiple income sources or are self-employed, the best option is to hire an authorized preparer to ensure everything is filed correctly. You can also go to a community organization that offers low-cost assistance.
Step 3. File your tax return in the United States on time
Keep in mind that the deadline to file your tax return is usually April 15 each year. It is essential to submit your tax return within the deadline to avoid penalties and delays in receiving your refund.
How much does it cost to file taxes, and which option is best for you?
As mentioned before, there are different ways to file your tax return, which vary in cost and level of support offered. The best option depends on several factors, such as your income level and how familiar you are with tax topics.
Below is a comparative table of the different ways to file taxes in the United States.
Method
Approximate cost
Level of support
Doing it yourself with IRS-approved software
Free or up to $25
Low. Although the platform guides you step by step, you must enter all the information yourself.
With the support of community organizations
Free or up to $50
Medium. You receive assistance from certified volunteers.
With private preparers or accountants
$150 to $500, depending on complexity
High. The preparer does all the work and answers your questions.
Practical tips to avoid mistakes in your first tax filing
If this is your first time filing taxes in the United States, it may seem like a very complex task. Keep these tips in mind to ease the stress associated with the process.
- Don’t wait until the last minute to file: keep the deadline in mind and prepare several weeks in advance.
- Verify that all forms match your income: remember that the required form depends on your type of work. Make sure your income matches what you report.
- Keep copies of all submitted documents: create both a physical and digital file to have every record handy.
- Check official IRS resources for immigrants: always access official websites ending in .gov.
- Avoid relying on third parties that promise higher refunds: remember that tax preparers or community organizations must be certified by the IRS to ensure your filing is done properly and your personal data remains secure.
Común, your financial support after filing your taxes
We’ve shown that the tax filing process is not as complicated as it seems. Now you know which steps to take and which method to use based on your situation.
Just as filing taxes helps you organize your financial situation, Común helps you manage your day-to-day finances.
Discover all the benefits of Común!
- Open a checking account with a qualifying official identification from your home country.
- Mobile app available in Spanish and English, specially designed for the immigrant community.
- Ability to receive your tax refund directly into your account.
- Debit card for daily expenses and international money transfers to Latin America.
Discover Común, the option dedicated to serving the needs of immigrant communities in the United States, with support available in Spanish.
Frequently Asked Questions (FAQ)
If you still have questions, check this section.
What happens if I don’t file my taxes in the U.S.?
Not filing your tax return may result in IRS penalties, accumulated interest, and withheld future refunds.
Can I file taxes without a Social Security Number?
If you do not have a Social Security Number, you can apply for an ITIN.
Is it better to file my taxes myself or with a tax preparer?
It depends on your situation: if you have only one source of income, you can use software, but if your income is higher or more complex, the best option is to consult a professional.

Immigration
Benefits of Having an ITIN in the U.S. for Non-Citizens
8 min de lectura
How to get an ITIN
The ITIN is obtained through IRS Form W-7 along with identity and foreign status documentation. A passport is the only document that satisfies both requirements on its own. The process takes between 7 and 11 weeks.
1. It allows federal tax filing
The ITIN allows you to file tax returns with the IRS, including claiming credits such as the Child Tax Credit and the Earned Income Tax Credit.
2. Access to credit and financial services
Some banks and credit unions accept an ITIN as an alternative ID to an SSN for opening accounts. Platforms like Común do not require either an SSN or an ITIN.
3. It facilitates business operations
For entrepreneurs, the ITIN is vital for filing business taxes and applying for an Employer Identification Number (EIN).
4. It supports residence and immigration processes
Consistently filing taxes with an ITIN can demonstrate good moral character, a factor considered in some immigration cases.
5. It helps establish identity and secure income
In the absence of an SSN, the ITIN is recognized by financial institutions and government agencies as a valid identification number.
6. Access to state services and benefits
In some states, the ITIN allows access to a driver’s license, health insurance, or in-state college tuition rates.
7. It protects against tax identity theft
Using the ITIN consistently links your tax data to your identification number, reducing the risk that someone files a return in your name.
Frequently asked questions about ITIN benefits
What is the ITIN used for in daily life?
The ITIN allows you to file tax returns with the IRS, claim tax credits such as the Child Tax Credit, open bank accounts at institutions that accept it, and in some states access services such as driver’s licenses or in-state tuition. It is the tax identification number for those who do not qualify for an SSN.
Does the ITIN give me the same rights as an SSN?
No. The ITIN is exclusively for tax purposes. It does not authorize you to work legally in the U.S., does not generate Social Security credits, does not provide automatic access to federal benefits such as Medicare or unemployment, and is not equivalent to an SSN for most government procedures. It is a tool for tax inclusion, not immigration status.
Does filing taxes with an ITIN affect me in an immigration process?
In general, filing taxes with an ITIN can be beneficial in immigration processes because it demonstrates a history of tax compliance and “good moral character,” one of the criteria evaluated in some adjustment-of-status cases. However, the impact varies by case — consult an immigration attorney before using it as an immigration strategy.
Can I open a bank account with an ITIN?
Some banks do accept an ITIN. Bank of America and certain local banks have specific programs for ITIN holders. However, many large banks require an SSN. Alternatives like Común do not require either an SSN or an ITIN — they accept a passport, consular ID, or other Latin American IDs for immediate account opening.
Does the ITIN help me access credit in the U.S.?
Yes, partially. Some credit card issuers and lenders accept an ITIN. Certain mortgage programs (ITIN loans) allow you to buy a home without an SSN. Building credit history with an ITIN is possible, although more limited than with an SSN. Credit built with an ITIN generally does not automatically transfer if you later obtain an SSN.
How do I apply for an ITIN if I have never had one?
You submit IRS Form W-7 along with identity and foreign-status documentation — a passport is the only document that satisfies both requirements on its own. You can mail it with your tax return, go in person to an IRS Taxpayer Assistance Center, or apply through an authorized Certifying Acceptance Agent (CAA), which is the fastest and safest method.
Financial Education
How to fill out a check in the United States in 5 simple steps (+ Example)
8 min de lectura
Have you ever filled out a check? Although most transactions today are digital, knowing how to fill out a check is essential—especially if you are just beginning your financial life.
According to recent data, one-third of Americans paid by check in 2024, demonstrating that checks still play an important role in the U.S. economy.
You might consider checks an outdated payment method; the reality is that they are useful in specific situations. For that reason, we will explain what a check is, the different types of checks, and how to complete them properly.
What Is a Check and What Is It Used For?
Despite the digital era, checks remain a relevant traditional payment method due to their formality and traceability. They are used for rent payments, purchases, and service payments.
Additionally, checks are a common payment method among the immigrant community, who often use them while adapting to the U.S. banking system.
But what exactly is a check and what are its characteristics? It is a physical document issued by an individual or business (the drawer) to order a bank to pay a specified amount to a third party. For the payment to be processed, the drawer must have sufficient funds in their checking account.
In general, a check contains the following information:
- Name of the drawer, whether an individual or a business
- Name of the payee
- Financial institution where the money will be drawn
- Amount to be paid, both in numbers and in words
- Signatures of the drawer
What Are the Different Types of Checks?
There are different types of checks in the United States. In this case, we will focus on the personal check, although you may choose the option that best suits your needs.
Personal Check
A personal check is a payment order issued by an individual to another individual using the funds in a checking account.
What Is a Personal Check Used For?
The most common uses for personal checks include:
- Rent and utility payments
- Purchase of everyday goods
- Legal agreements requiring documentary support
Certified Check
A certified check serves the same purpose as a personal check but is reviewed and guaranteed by the issuing bank, which verifies that the drawer has sufficient funds and holds them until the check is cashed.
A certified check provides certainty of available funds, making it a more secure method for making and receiving payments.
Cashier’s Check
Unlike a personal check, a cashier’s check is issued directly by the bank, offering greater security for the payee, as the bank is responsible for issuing and safeguarding the funds.
To obtain a cashier’s check, the drawer must visit a bank branch and pay the amount to be transferred. The bank then issues the check in the name of the payee, guaranteeing that it can be cashed using the institution’s own funds and not a personal account.
It is commonly used for high-value purchases such as homes and vehicles.
Money Order
While not strictly a check, it is a traditional payment method with similar functionality.
A money order is a financial instrument that allows funds to be sent via traditional mail using a certified check, which must be purchased and paid for by the drawer at an authorized location.
It allows secure money transfers without requiring a bank account.
How to Fill Out a Check in the U.S.
Before issuing this type of payment order, you must know how to do it properly. Below is an example of how to fill out a check easily, starting from step one:
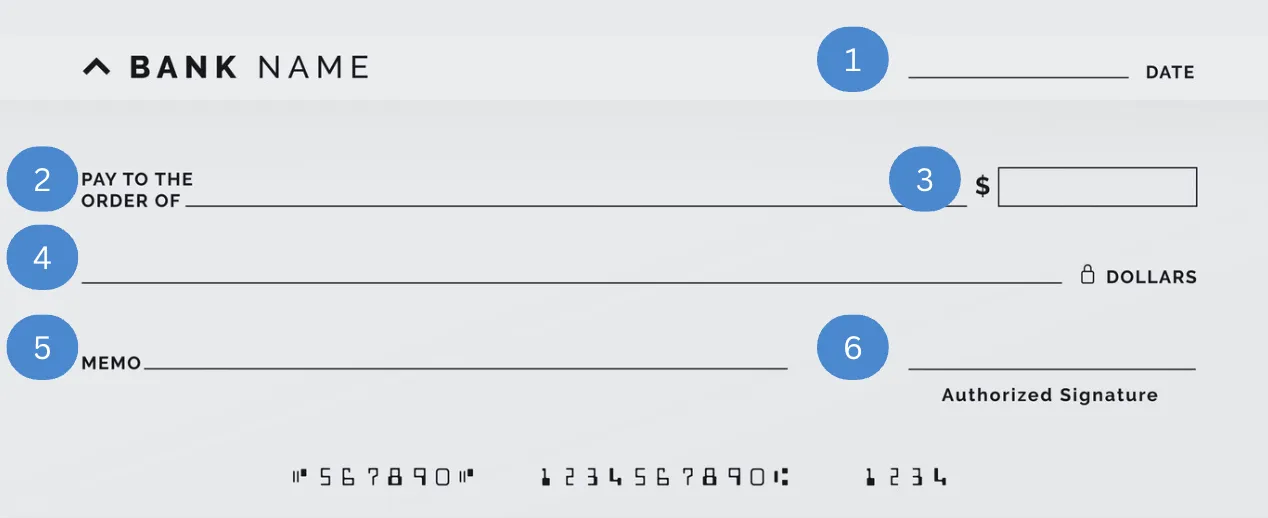
1. Write the Date
Remember that in the United States, the date format is mm/dd/yyyy.
2. Payee’s Name
Write the full name of the person to whom you are issuing the check, exactly as it appears on their official identification.
3. Amount in Numbers
Write the numerical amount clearly.
4. Amount in Words
Write the amount in words, including cents.
5. Add a Memo
You may include a note specifying the reason for the payment.
6. Sign the Check
Sign the check legibly in the space designated for the drawer.
7. Review the Information
Ensure that all information is accurate to avoid issues for the payee when cashing the check.
It is essential to complete checks legibly, without strike-throughs or corrections, as these may invalidate the document.
How to Correctly Write Numbers in Words on a Check
Writing amounts in words may be confusing when dealing with U.S. dollars. The following points should be kept in mind:
- Dollar amounts must be written in full words
- Cents must be written as fractions
- Avoid using dollar symbols or similar notations
- If there is leftover space at the end of the line, draw a line to prevent fraud
- For example, $1,000.75 is written as: One thousand and 75/100 dollars
Cash Checks and Manage Your Money Easily with Comun
As you can see, knowing how to fill out a check is useful for sending and receiving money in the United States. It is a reliable and accessible alternative if you do not have a banking account.
However, issuing and cashing a check can also require significant time and effort. That’s why you can skip the trip to the bank, avoid wasting time or money on gas, and cash your check directly from your phone using Comun—no lines, no questions, no complications.
Discover Comun, the only platform designed to serve the needs of immigrant communities in the United States, with support available in Spanish.
Why Choose Comun?
- Open your account with an official ID from your country
- Access a mobile app specifically designed for immigrants in the U.S.
- Make payments, receive your salary, and manage your finances
- Send money to your loved ones in LATAM for just a $2.99 transfer fee
Frequently Asked Questions
Still have questions about how to fill out a personal check? See our FAQ section.
What if I Make a Mistake Filling Out a Check?
If there are strike-throughs or inconsistencies in the amounts, the check must be voided and a new one used.
How Do I Void a Check?
Write the word VOID in large letters on the front of the check.
What Information Appears on the Back of a Check?
The back of the check contains the endorsement, meaning the payee’s signature for cashing the check.

Community
Investment Basics for Immigrants in the U.S.
8 min de lectura
The Importance of Investing for Immigrant Families
Investing is one of the most powerful tools for building long-term wealth. For immigrant families in the U.S., understanding investment basics can make the difference between merely surviving and financially thriving. In this guide, we explain the fundamental concepts you need to know before you start investing.
What is investing?
Investing means putting money into assets with the goal of growing it over time. Unlike saving, which keeps money safe but with low returns, investing takes on some risk in exchange for the possibility of higher gains. The most common assets are stocks (ownership stakes in companies), bonds (loans to governments or companies), mutual funds (diversified portfolios), and real estate.
Key concepts you need to understand
Risk and return
The higher the potential risk, the higher the return can be. Individual stocks are more volatile than government bonds. Index funds offer a balance between reduced risk through diversification and historically positive long-term returns.
Diversification
Do not put all your eggs in one basket. Spreading investments across multiple assets, sectors, and geographies reduces the risk that one bad investment will ruin your entire portfolio.
Compound interest
Compound interest is the phenomenon of earning interest on previously earned interest. An investor who starts at age 25 will reach retirement with significantly more money than someone who starts at 35, even if they contribute the same monthly amount.
Investment horizon
The length of time you plan to hold your investments affects which assets to choose. For goals more than 5 years away, you can take on more risk. For short-term goals, prefer more conservative options. Never invest money you need in the short term.
Frequently asked questions about investing for immigrants in the U.S.
Can an immigrant invest in the U.S. stock market?
Yes. Most brokers in the U.S. allow non-citizens to invest, including permanent residents and people with work visas (H-1B, L-1, etc.). Some brokers also accept non-residents. To open an investment account, you generally need a tax identification number (SSN or ITIN) and a U.S. bank account.
How much money can I start investing with in the U.S.?
Most modern brokers like Fidelity, Charles Schwab, and Robinhood have no minimum amount to open an account. You can buy fractional shares starting at $1. What matters is not the starting amount but consistency—investing $50-100 per month regularly produces better results than irregular large sums thanks to dollar-cost averaging (DCA).
What is an index fund and why is it recommended for beginners?
An index fund is a fund that tracks the performance of a stock market index such as the S&P 500. Instead of selecting individual stocks, you invest in a “basket” of the 500 largest companies in the U.S. They are popular for their low cost (fees of 0.03-0.20%), automatic diversification, and historical returns that have outperformed most active managers over the long term.
What happens to my investments if I move back to my country?
You can usually keep your U.S. investment account while abroad, although some brokers restrict nonresident accounts. When you sell, you will pay capital gains taxes in the U.S. (and possibly in your country of residence). Consult a tax advisor before leaving the country to plan the transition properly.
Is a 401(k) account the same as a regular investment account?
No. A 401(k) is a tax-advantaged retirement account generally offered by your employer—the contributions reduce your taxable income now, and the money grows tax-deferred until retirement. A regular investment account (brokerage account) does not have special tax advantages but also no withdrawal restrictions. Both are complementary tools for building wealth.
What are the most common mistakes beginner investors make?
The most common mistakes are: investing money you need in the short term (investments require a 3+ year horizon), selling when the market drops out of panic, not diversifying (putting everything in one company or sector), paying unnecessarily high fees, and not investing because you are “waiting for the perfect moment.” Discipline and consistency matter more than perfect market timing.
Immigration
Complete guide to preparing your immigration recommendation letter
8 min de lectura
Immigration procedures in the United States are often exhausting and confusing because of the number of requirements and the associated wait times.
You don’t have to feel alone during these processes: you can rely on a recommendation letter, which gathers family, community, or workplace support from people who truly trust your integrity and are willing to offer genuine backing that could bear on USCIS’s final decision.
Below is a user-friendly, practical guide on how to write an immigration recommendation letter, what it should include, mistakes to avoid, sample letters, and tips to convey credibility and improve your chances in a visa or Green Card process.
What is an immigration recommendation letter and why it matters
A recommendation letter is a personal document that supports U.S. immigration processes and is valued by USCIS. It serves as testimonial evidence of the applicant’s moral character, work ethic, and community contribution.
This supporting letter may be requested to complement documentation for various proceedings:
Permanent residence
Applicants commonly must show “good moral character,” employment stability, and community ties.
Asylum cases
The letter helps reinforce the applicant’s credibility and show they have support in the United States as a contributing community member.
Work visas such as EB-2 NIW
Professionals or researchers often need a recommendation letter from expert peers to substantiate their track record and expertise.
Naturalization
Recommendation letters are not always requested, but they can support evidence of the applicant’s good conduct.
Don’t confuse this with an employment or academic letter; the purpose of an immigration recommendation letter is to attest to the applicant’s good behavior and moral character.
Who can write an immigration recommendation letter?
An immigration recommendation letter should be written by someone with a genuine, close relationship to the applicant who can attest to their positive impact—through family, social, or workplace ties.
These are the main profiles you can ask for a recommendation letter:
Family members
They can testify to the applicant’s role in the family and commitment to loved ones.
Close friends
A close friend can focus on qualities like loyalty, honesty, and trustworthiness to emphasize the applicant’s human side.
Employers or colleagues
They provide key testimony of the applicant’s work ethic and professional responsibility.
Community or religious leaders
These individuals can speak to the applicant’s community involvement and positive impact.
Keep in mind that what matters most is not the recommender’s title, but their sincerity and credibility in vouching for the applicant’s reputation.
Steps and structure for writing an immigration recommendation letter
Although an immigration recommendation letter focuses on the applicant’s ethics and moral character, it is still a document evaluated for order and formality by U.S. authorities.
For that reason, be sure to include the following details.
Header and formal salutation
Include the applicant’s full name, address, date, and a formal salutation to USCIS or the relevant authority.
Sender’s introduction
The sender should state their full name and then explain their relationship to the applicant, how long they’ve known them, and the letter’s purpose.
Body of the letter
This is the most important part and should reflect aspects such as:
- Values: honesty, responsibility, solidarity, etc.
- Community involvement: volunteering, neighborhood activities, or initiatives to address local issues.
- Work ethic: punctuality, discipline, professional attitude, commitment, responsibility, and the applicant’s achievements, etc.
Include concrete examples to reinforce credibility, such as: “Alicia Martínez is known in the community as someone who looks out for others’ well-being, like the times she has actively taken part in trash-collection programs and efforts to help homeless children.”
Closing and signature
The sender should reaffirm support for the applicant and be open to being contacted to clarify any point, so contact details are necessary.
At the end, they should include their name and handwritten signature.
Sample immigration recommendation letter
Below is a reference letter template to make drafting your document easier.
Sender’s full name
Address
Phone number
Date
To the attention of U.S. Citizenship and Immigration Services (USCIS):
My name is [Sender’s name], and I have known [Applicant’s name] for [number of years] through our professional relationship at [describe job title and company]. I am honored to provide my testimony in support of their U.S. immigration process.
Over the time I have known them, I have observed qualities such as punctuality in reporting to work and professionalism toward both colleagues and clients.
I am confident that [the applicant] will be a valuable member of U.S. society because of their human values and professional capabilities.
I remain at your disposal and include my contact information in case any questions arise.
[Signature][Full name]
You can use this example as a base, but you should adapt it to the relationship between you and the recommender and add any additional information to convey authenticity and sincerity. Be sure to include the introduction, qualities, examples, and a formal closing.
Común, your financial ally in the United States
Here we’ve shown what an immigration support letter is and how to write one in Spanish, who can write it, its structure, and a practical example.
The main objective of a recommendation letter is to support you in U.S. immigration procedures; likewise, Común supports your financial life upon arrival in the country.
Discover the benefits of Común!
- Open your account easily with qualifying official ID from your country of origin.
- Mobile app in Spanish and English, designed for immigrants, with intuitive, transparent processes.
- Remittances to Latin America with clear, competitive fees, without complicated processes
Común is the financial service designed for immigrant communities in the United States. Open your account today and discover the ideal support for your finances!
Frequently Asked Questions (FAQ)
If you still have questions, see the section below:
How many recommendation letters do I need for immigration?
There is no specific number. A single well-written letter may be sufficient. For extraordinary-ability visas or National Interest Waivers (NIW), more than four may be required to support the applicant’s professional record.
What if I don’t have anyone to write my immigration letter?
You can ask an immigration attorney to prepare a statement explaining why no one is available to provide a letter.
Is it acceptable to submit a recommendation letter in Spanish?
Ideally, submit the letter in English or include a certified translation to avoid issues during the visa application.
International Money Transfers
How to Make International Money Transfers: Options and Costs
8 min de lectura
As the reasons for transferring money internationally increase, so do the available methods. Whether you are sending remittances to your family, paying suppliers, or receiving payments from abroad, understanding how international transfers work will help you save time and money.
What is an international money transfer?
An international money transfer is the movement of funds from a bank account in one country to another account in a different country. It can be done through bank wire transfers, specialized remittance services (Western Union, Remitly, Wise), or platforms like Común that allow you to send money to Mexico directly from the app.
How to choose the best international transfer service?
To choose the best service, consider: the total cost (visible fee + exchange rate margin), delivery speed, available delivery methods (bank deposit, cash pickup), and whether they accept your documentation. Use comparison tools like Monito to see real-time options for your specific corridor.
Main options for sending money internationally from the U.S.
Bank wire transfer
Traditional, expensive method ($25-45 per transfer), takes 1-5 business days, requires the recipient’s full bank details: account number, SWIFT/BIC, IBAN, or CLABE (Mexico).
Specialized remittance services
Wise, Remitly, and Xoom offer fees lower than 3-5%, delivery from minutes to 3 days, and multiple delivery options. Wise uses the real market exchange rate. They require an SSN or ITIN in the U.S.
Común
Común allows you to send remittances to Mexico and Latin America starting at $2.99 without requiring an SSN. Ideal for newly arrived immigrants. Options for bank deposit, cash pickup at Oxxo or Walmart.
Frequently asked questions about international transfers
What is the cheapest way to make an international transfer?
Specialized remittance apps (Wise, Remitly, Xoom) are generally cheaper than traditional banks for international transfers. Wise is known for using the real market exchange rate with transparent fees. For specific destinations such as Mexico, platforms like Común offer transfers starting at $2.99. Use comparison tools like Monito to see the best real-time options for your specific corridor.
How long does an international transfer take?
It depends on the method and destination country. International bank wire transfers take 1-5 business days. Remittance apps can be almost instant for cash pickup, or 1-3 business days for bank deposit. Factors such as time zones, bank cutoff times, and the destination country’s compliance requirements affect arrival time.
What information do I need to make an international transfer?
For an international bank wire transfer, you need: the beneficiary’s full name, the receiving bank’s name and address, the receiving bank’s SWIFT/BIC code, and the beneficiary’s account number or IBAN. For Mexico, the interbank CLABE (18 digits) is used. For remittance apps like Común, sometimes the recipient’s phone number or bank name is enough.
Are there amount limits for international transfers?
Yes. Limits vary by service and user verification level. Remittance apps typically allow between $2,999 and $10,000 per day for verified users. Bank wire transfers can be larger but cost more ($25-45 per transaction). Anti-money-laundering regulations require reporting transfers over $10,000 to the IRS (CTR form).
Do I need an SSN to send money abroad from the U.S.?
It depends on the service. Wise, Remitly, and traditional banks require an SSN or ITIN for regulatory compliance. Platforms like Común do not require an SSN — they accept a passport or consular ID — and allow you to send remittances to Mexico and Latin America starting at $2.99. This is especially useful for newly arrived immigrants who do not yet have an SSN.
Are international transfers taxable?
Sending money abroad itself does not generate taxes in the U.S. However, if the money comes from undeclared income, that is the tax obligation to address. The IRS may require reporting foreign accounts (FBAR/FATCA) if you have more than $10,000 in foreign accounts at any point during the year.
Financial Education
What is cashback and how does it work? A 2026 Guide
8 min de lectura
What is cashback and how does it work? A 2026 Guide
Cashback is a rewards system that gives you back a percentage of the money you spend on eligible purchases. In simple terms, when you buy something using certain credit cards, debit cards, apps, or rewards programs, you may get a percentage of your money back on purchases, though it is usually credited to your account rather than handed over as physical cash.
If you recently moved to the United States or are learning how the financial system works, you may have heard the term 'cashback' while shopping at places like Walmart, Target, gas stations, supermarkets, or online stores.
For many people, cashback can become a practical tool to manage everyday expenses such as groceries, transportation, gas, and household purchases. While the amounts may seem small at first, they can add up over time when used consistently and responsibly.
What is cashback?
Cashback is a type of financial reward that returns a percentage of your purchase after you spend money with a participating payment method or rewards platform.
For example:
- If you spend $100 at the supermarket using a card that offers 2% cashback, you may receive $2 back
- If a cashback app offers 5% cashback at a participating gas station and you spend $60 on fuel, you may receive $3 back
Unlike traditional discounts, cashback usually happens after the purchase is completed. The Consumer Financial Protection Bureau (CFPB) explains that cashback rewards are commonly offered through credit cards and loyalty programs as an incentive for spending.
How does cashback work?
Cashback programs generally follow a simple process:
- You make an eligible cashback purchase using the participating card, app, or rewards account
- The transaction is recorded by the provider
- A percentage of that purchase is returned to you as cashback
The reward may appear as:
- Statement credit
- Bank deposit
- Gift card
- Rewards balance
- Redeemable points
- Store credit
Some cashback rewards appear within a few days, while others may take an entire billing cycle or longer to process. There are often minimum redemption thresholds before you can claim your cashback. Certain programs may include expiration dates. It is also important to understand that not every purchase qualifies for cashback.
Cashback vs. traditional discounts
While cashback and traditional discounts can both help consumers save money, they work in different ways. A traditional discount lowers the price immediately at checkout, while cashback returns part of the money after the purchase has already been completed.
| Cashback | Traditional Discount |
|---|---|
| Money is returned after the purchase | Price is reduced before purchase |
| Usually linked to cards, apps, or loyalty programs | Usually available directly in-store |
| Rewards may take days or weeks to process | Savings are immediate |
| May help track expenses digitally | Does not usually include tracking tools |
| Often limited to eligible categories or stores | Depends on store promotions |
Types of cashback in 2026
Not all cashback programs work the same way. Before signing up for a cashback program, it is important to review details such as annual fees, interest rates, minimum redemption, expiration policies, and spending categories.
Fixed-rate cashback
This type gives the same cashback percentage on all purchases. Example: 1.5% cashback on everything you buy. This structure is simple because you do not need to track categories or rotating offers.
Category-based cashback
Some cards or apps offer higher cashback percentages in specific categories such as supermarkets, restaurants, gas stations, or streaming subscriptions. For example: 3% on groceries, 2% on gas, 1% on all other purchases.
Rotating cashback categories
Some providers change cashback categories every few months. One quarter may focus on gas stations and grocery stores; another may include online shopping and travel purchases. These programs sometimes require manual activation each quarter.
Welcome bonuses
Certain credit cards offer introductory cashback bonuses if you spend a minimum amount during the first months after opening the account. For example: spend $500 in the first 3 months and receive $150 cashback bonus. The Federal Trade Commission recommends reviewing terms carefully before applying for financial products with promotional offers.
Where can you get cashback in the United States?
Credit cards:
Many credit cards in the U.S. include cashback rewards. Some examples include products from Discover, Chase, Capital One, and American Express. Some cards focus on categories like dining or travel, while others offer flat-rate cashback.
Debit cards:
Some financial institutions offer cashback debit cards, although rewards are usually smaller than those offered by credit cards. This may appeal to people who prefer avoiding debt or credit card interest.
Cashback apps:
Several mobile apps partner with retailers and offer cashback rewards for purchases. Examples include Rakuten, Ibotta, Upside, and Honey. These apps may provide cashback for grocery shopping, online purchases, gas stations, and restaurants.
Store loyalty programs:
Retailers sometimes offer cashback or store rewards through membership programs. For example, supermarkets, pharmacies, and warehouse stores may return store credit or savings points after purchases.
Cashback vs. points vs. miles: Which is better?
Although they are often grouped together under the category of 'rewards,' each one works differently and can be useful depending on a person's spending habits, financial goals, and lifestyle.
Cashback programs generally return a percentage of the money spent on eligible purchases. Points systems usually assign a numerical value to purchases that can later be redeemed for products, gift cards, discounts, or services. Travel miles are typically associated with airlines, hotels, or travel-focused credit cards.
| Cashback | Points | Miles |
|---|---|---|
| Returns money | Rewards system value | Travel-focused rewards |
| Flexible spending | Often redeemed in specific ecosystems | Usually tied to airlines or hotels |
| Reward after spending | Redemption values vary | Best for frequent travelers |
| Common for everyday purchases | May include gift cards or products | Often used for traveling |
For many people, especially those focused on getting some value on their everyday expenses such as groceries, transportation, gas, or household purchases, cashback can feel more useful as the reward is directly connected to money rather than conversion systems or travel programs.
3 practical tips for using cashback responsibly
1. Use cashback for purchases you already planned
Focus on recurring expenses such as groceries, gas, transportation, and utility bills. This helps you avoid overspending simply to earn rewards.
2. Don't buy things you don't need
A cashback offer does not automatically make a purchase worthwhile. For example, spending $200 to earn $4 cashback may not help your finances if the purchase was unnecessary.
3. Track your cashback earnings
Many apps and financial platforms allow you to monitor spending categories, cashback totals, and monthly rewards. Tracking your rewards can help you understand your spending patterns and maintain financial goals.
Does Común offer cashback?
No. Común does not currently offer cashback programs.
However, Común provides tools and resources that offer guidance for Latin American immigrants navigating the U.S. financial system.
While cashback might be useful for some people, it is important to pay attention to commissions, as savings when commissions are included might not be as strong as initially perceived. When comparing financial tools in the United States, cashback is only one factor to consider. Fees, commissions, account accessibility, and transparency can also affect your financial experience over time.
Común's cost for opening a debit account is $0, same as the $0 minimum balance and $0 monthly commission for the debit account.
FAQ
What is cashback and how does it work?
Cashback is a rewards system that returns a percentage of your purchases after you spend money using eligible cards, apps, or loyalty programs.
How is cashback calculated?
Cashback is usually calculated as a percentage of the purchase amount. For example, if you spend $100 and your cashback rate is 2%, you receive $2 back.
Where can I get cashback in the United States?
Cashback is commonly available through credit cards, debit cards, shopping apps, and retailer loyalty programs.
What is the difference between cashback and points?
Cashback returns money directly, while points are part of rewards systems that may only be redeemed for specific products, gift cards, or services.
Does Común offer cashback?
No. Común currently does not offer cashback.
Is cashback taxable?
In many cases, cashback earned through purchases is generally treated as a rebate rather than taxable income. However, tax treatment may vary depending on how rewards are earned. The IRS recommends consulting a tax professional for specific situations.

Checking account
What Is Online Banking?
8 min de lectura
Online banking refers to a financial institution with a digital presence on the web, accessible from different devices. Online banking has features that set it apart from other platforms — its main characteristic is that money and account management happen entirely online. Here are the main things that set it apart from traditional banking and other platforms — keep reading!
Features of Online Banking
Now that you know what online banking is, here are the different features it offers:
Convenience: You don't need to complete part of a transaction online and finish it in person at the bank. Online banking can offer 100% online transactions, depending on the institution.
Functionality: Banking today has improved the user experience to the point that most apps are user-friendly, offering a wide range of financial products and tools so users don't have to complete some confirmations in person at the branch.
Security: This is one of the aspects online banking has focused on most, and one of the factors that limited financial products for customers in the past. Today, there's a wide range of tools that make online transactions secure, including:
Banking software: Banks have internal software that protects users — in payment methods, IP location recognition, and payment processing and authentication.
Two-factor authentication: With mobile apps, security is properly guaranteed through online banking.
Security protocols: These are the steps required to access certain financial tools. Some protocols require two-factor verification, others use randomized codes depending on the bank's criteria.
Advantages of Online Banking
Over the years, online banking has optimized its digital processes, resulting in a number of benefits for users, including:
Time savings: You don't need to go to a bank branch to complete a transaction and wait to be helped after a long wait at the branch.
Better communication: Complaints are handled promptly on many platforms. Generally, the solution is found in one of the menus within the app. This is mainly due to the standardization of solutions for the most common issues regular users face, available as options within the platform.
Streamlined processes: The ease of acquiring financial products, choosing promotional cards, making both domestic and international transactions, and checking real-time spending make online banking an ideal option.
Ease of use: The options the platform offers make navigation within the app (for smartphones) or platform extremely user-friendly.
For these reasons, it's worth understanding the different operations related to online banking, including:
Opening a bank account online.
Making transfers online.
Getting benefits through online banking.
Setting up bill pay through your bank.
Checking account
Debit Account in the United States
8 min de lectura
In this article, we'll walk you through the advantages and requirements of having a debit account in the United States. It's worth noting that the world's financial center is New York, home to the most important payment hubs where the world's top-ranked financial institutions are connected. That's why having an account in the United States is essential if you do business globally.
Why Having a Debit Account in the United States Matters
Here are the advantages of having a debit account in the United States and what it means to have one — among the most notable benefits:
Cost: The cost to open an account in the U.S. is actually minimal, largely thanks to the digital account types available today. This gives you the ability to handle financial transactions smoothly with the people you want to do business with.
Requirements: Requirements are usually basic, as long as you're of legal age and have some form of address documentation. If you're a foreigner, it's possible to open an account in the United States without a long list of requirements or needing to be physically present.
Control: You can track fees, deductions, and payments made through the platform — for that, we recommend reading: How to Manage My Money in a Debit Account.
Ideal for Freelancers: If you do remote work, global companies typically require an account on some payment platform. For that, you'll need a U.S.-based account. That's why it's worth opening one, so you can meet the requirements of that payment platform.
Security: You get the security that comes with U.S. regulation. On top of that, funds are protected by the Federal Deposit Insurance Corporation (FDIC).
Options: There's a wide variety of ways to get a U.S. account, and among the main options is starting with a debit account, which offers alternatives for people who want an account without being a U.S. resident.
General Requirements to Open an Account in the United States
The requirements listed here are for opening a general account — keep in mind that requirements vary by account type. Among the requirements U.S. financial institutions typically ask for:
ID document: Issued by your country of residence's government (passport, national ID, or identity card depending on your country of origin).
Proof of residence: A current utility bill showing your physical address. It must include a zip code.
Email address: So the confirmation email can be sent this way if you open the account through a platform or app.
Mobile device: To authenticate transactions made through the bank's platform.
If you want to open an account in the United States, there are several options and account types available. Just choose the one that fits your needs, requirements, and that you can comfortably and securely meet the requirements for.
Community
What You Need to Open an Account at Comun¹ 4
8 min de lectura
Unmatched Ease of Opening an Account
Opening a checking account with Comun is simple and hassle-free, addressing the barriers to financial exclusion typically faced by the immigrant community. Accepting over 100 forms of identification², including social security numbers from Latin American countries, Comun ensures that immigrants have access to essential banking services. The application process is quick, taking less than 5 minutes, and is free of additional or hidden fees, minimum balance requirements or monthly commissions. This inclusiveness is central to Comun's mission of fostering financial stability and growth.
Mobile Deposit Options
ComunComun offers a convenient mobile deposit feature that allows users to deposit cash at more than 88,000 locations in the United States, including major retailers such as Walgreens, Dollar General and Walmart. This extensive network ensures that users can easily find a deposit location near them, making the process of adding money to their accounts simple and hassle-free.
Traditional Banking: Although many traditional banks offer mobile deposit options, they often restrict these to check deposits through a mobile app. Cash deposits typically require a visit to an ATM or bank branch, which can be less convenient and more time-consuming than Comun's extensive cash deposit network.
Utility in Today's World: In today's fast-paced environment, the flexibility to deposit cash in a wide range of accessible locations is invaluable, especially for individuals who may not have easy access to traditional banking services or who work non-traditional hours when banks are closed.
International Remittances
ComunComun excels in facilitating international remittances⁴, allowing users to send money abroad quickly and with lower fees compared to many traditional banks and remittance services. The process is enhanced with real-time notifications, keeping the sender informed from the moment the money is sent until it is received.
Traditional Banking: Traditional banks generally offer international transfer services, but these can be expensive and slow, with transfers sometimes taking several days to complete. In addition, the fees associated with traditional bank remittances can be significantly higher.
Usefulness in Today's World: In a globalized economy, the ability to send money across borders quickly and affordably is crucial. Many families rely on remittances for financial support, and businesses need efficient ways to handle international transactions. Comun's streamlined and cost-effective service effectively meets these modern demands.
Advance Salary Access
Comun: Comun offers the ability to connect wages to the application and receive payment up to two days in advance³. This feature incurs no additional fees, providing significant relief during financial emergencies or when planning ahead.
Traditional Banking: Some traditional banks have begun to offer similar features, but they are often tied to specific types of accounts or require a minimum balance. The accessibility and ease of use of early access to Comun's salary is not always matched in traditional environments.
Usefulness in Today's World: With the rise of gig economy jobs and irregular pay schedules, having early access to wages can provide a buffer against financial instability. This feature is particularly valuable for those living paycheck to paycheck, offering a cushion that can help avoid overdraft fees and late payments.
Unlike traditional banking institutions, Comun's innovative features are designed to meet the needs of today's diverse and mobile population, particularly benefiting the immigrant community in the U.S. By providing services that offer greater convenience, lower costs and greater accessibility, Comun not only addresses common challenges faced by its users, but also empowers them toward greater financial freedom and stability. As we move toward a more interconnected and fast-paced world, the importance of responsive and inclusive financial services continues to grow, something Comun is uniquely positioned to offer.
Robust Security and Customer Support
Security and customer support are paramount at Comun. With FDIC-insured accounts and Visa protection on virtual Visa debit card transactions, Comun customers can manage their funds with confidence. Innovative security features such as biometric logins and instant transaction notifications keep your money safe. In addition, Comun offers 24/7 customer support in English and Spanish, ensuring that help is always available in your preferred language.
Commitment to Zero Fees and Upward Mobility
Comun stands out not only for offering zero fees for account opening, monthly maintenance or minimum balances, but also for its commitment to helping its users move up the financial ladder. Comun acts as a financial partner, supporting financial transactions without the burden of excessive fees. This commitment aligns with the goal of enabling upward mobility for immigrants, who contribute significantly to the U.S. economy.
Customized Features and Benefits
Comun goes beyond traditional financial services by offering features designed to meet the unique needs of the immigrant community. Users can send money abroad with low or no fees, deposit cash at more than 88,000 locations nationwide, including free ATM withdrawals, and connect their accounts to popular payment apps such as Zelle, CashApp and Venmo. Comun's platform also allows customers to receive their paychecks up to two days early through direct deposit, further enhancing their financial flexibility and stability.
Conclusion
Comun is not just a financial services provider, but a platform dedicated to transforming the banking experience for immigrants in the U.S. With its user-focused design, commitment to financial freedom and robust features, Comun is destined to become a vital tool for achieving financial stability and growth for its users. Whether you are looking to manage your daily finances or send money to loved ones abroad quickly and securely, Comun offers a reliable, inclusive and efficient banking solution.
Foundational Moment: Did you know?
Founded by entrepreneurs Mark Selcow and Andres Santos in New York, Comun was built to empower families and enable upward mobility, particularly for the immigrant family. The company has garnered significant investment from prominent firms such as Costanoa Ventures, FJ Labs and South Park Commons, underscoring the tremendous opportunity to serve the financial needs of immigrant families and improve the lives of every individual.







Thousands of immigrants are already achieving more with their money. You can too.
Comun is a financial technology company and not a bank. Banking services are provided by Community Federal Savings Bank; Member FDIC. The Comun Visa® Debit Card is issued by Community Federal Savings Bank, pursuant to a license from Visa U.S.A Inc. and may be used everywhere Visa Cards are accepted.
Comun is a fintech company and not a bank or licensed money transmitter.
* Results may vary. For a complete list of eligible IDs and application requirements, follow this link.
^ No minimums, no maintenance fees. ATM or transfer fees may apply. See app for fee details.
‡ Direct deposit funds are typically available when we receive the payment file, up to two days before the scheduled payment date. This early availability is not guaranteed.
** A service provided by Service UniTeller, Inc. Service UniTeller, Inc. is licensed in all states that require a license. Remittance fees start at $2.99 but may vary. Please check the app for more details. Comun Inc. may earn revenue from the conversion of foreign currencies.
† Funds in your account are FDIC insured up to $250,000 by ownership category through Community Federal Savings Bank (CFSB), Member FDIC, in the event CFSB fails.


